
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
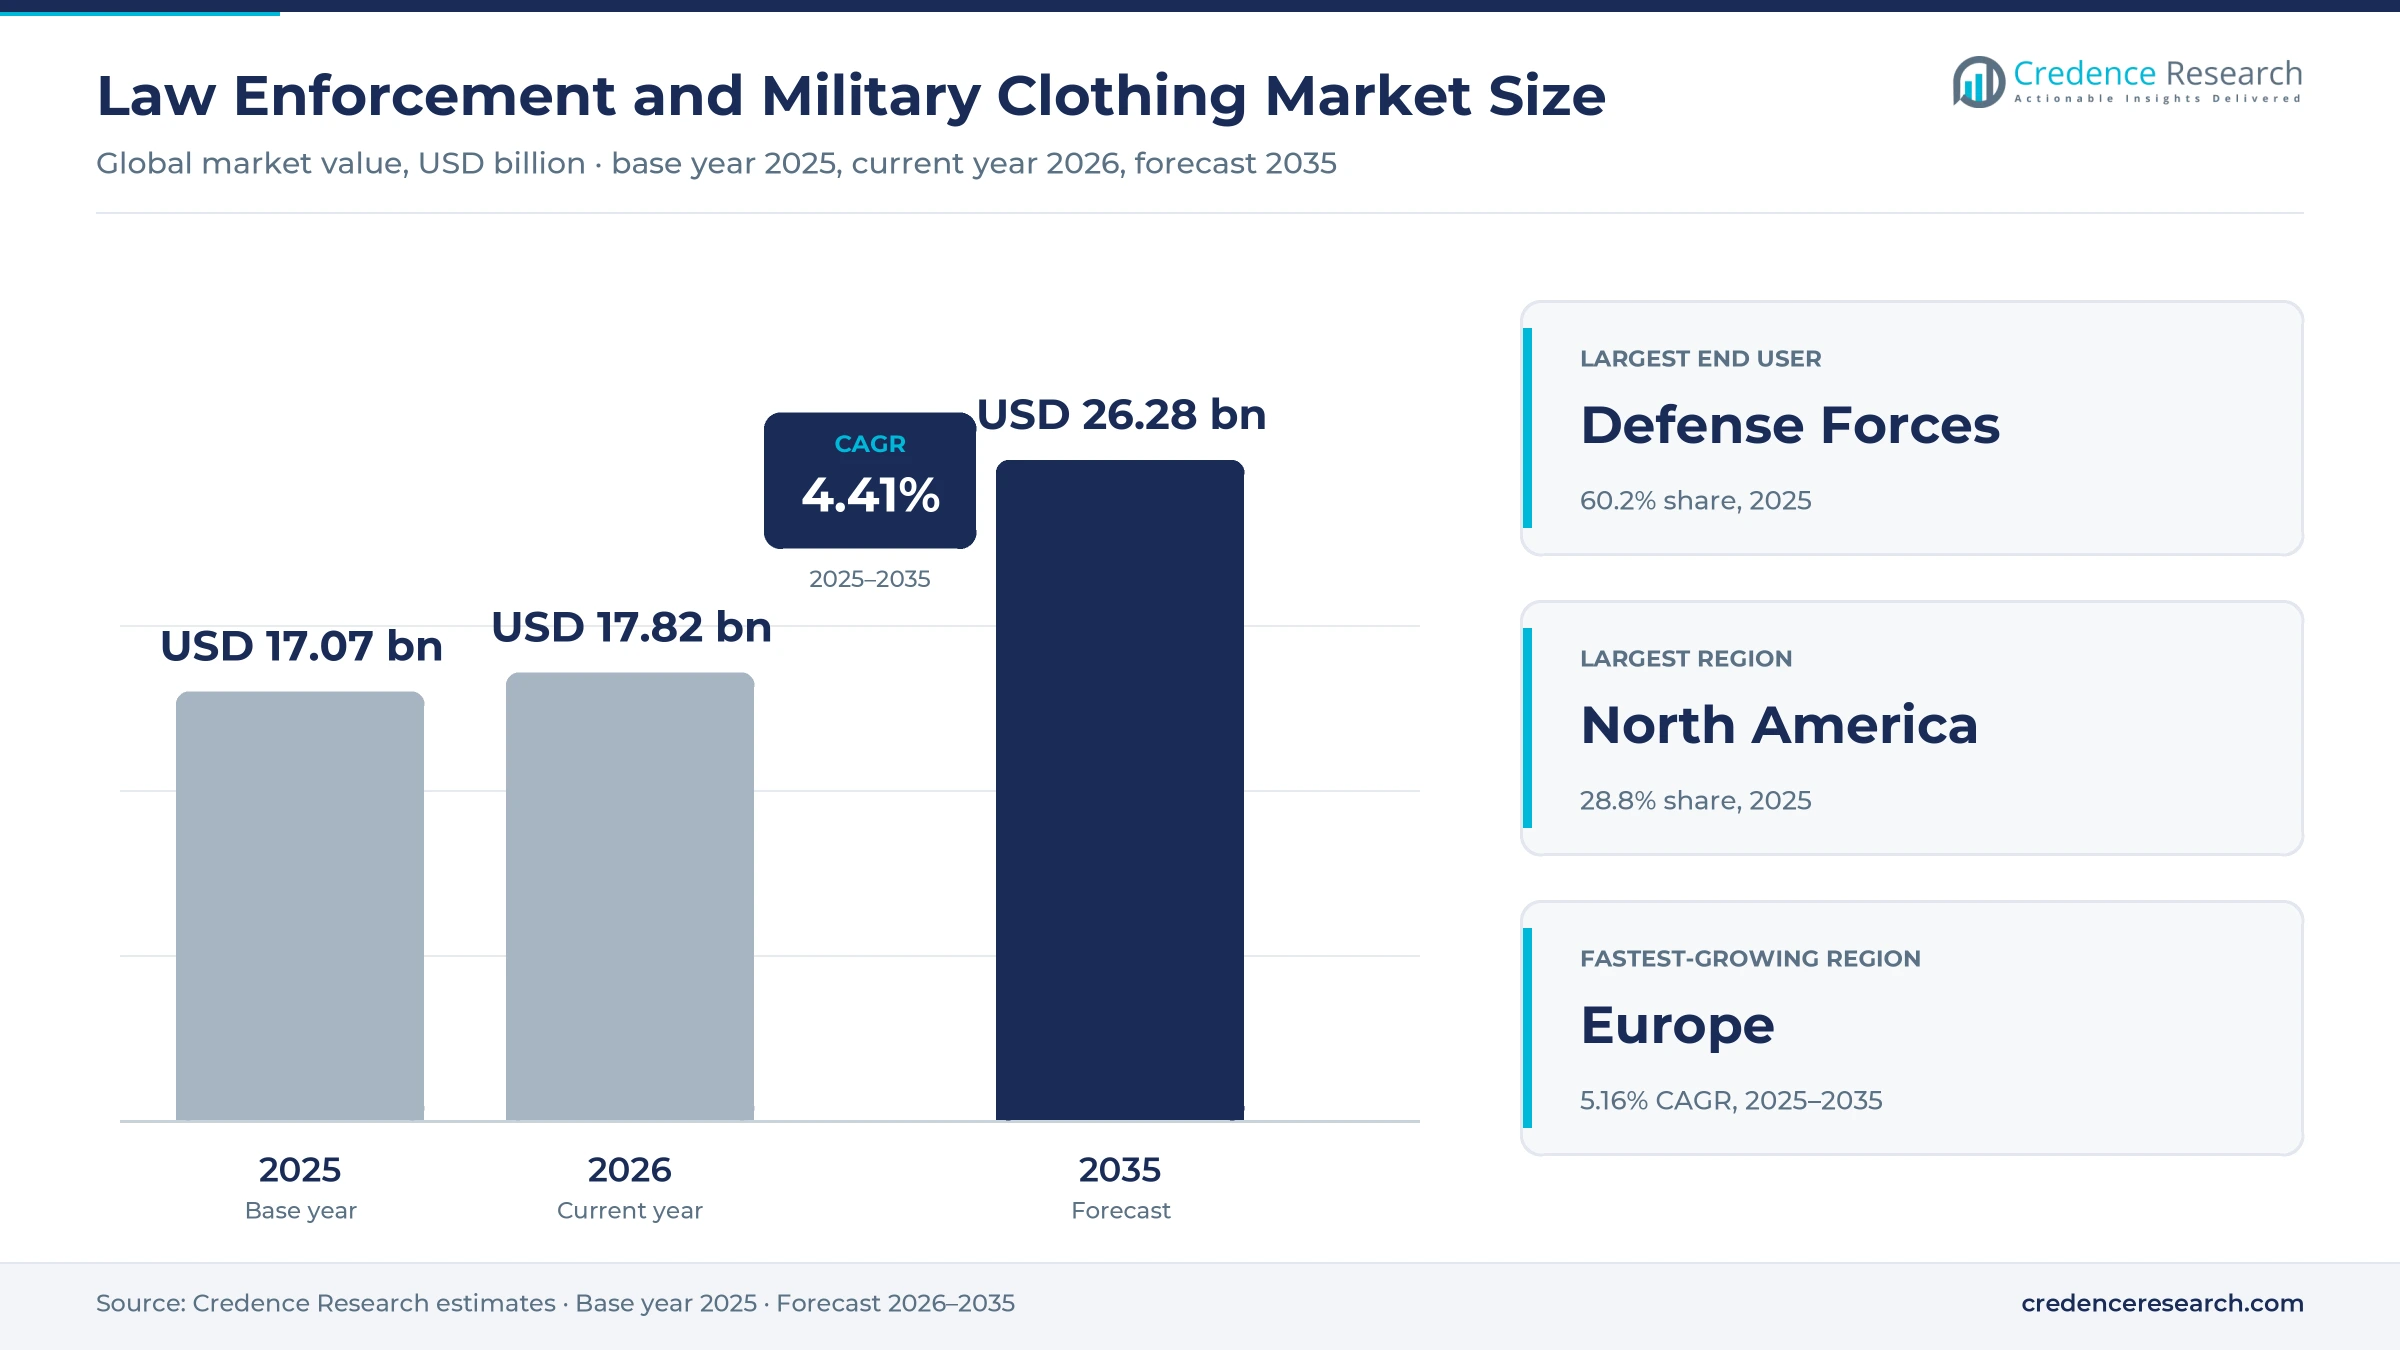
| Law Enforcement and Military Clothing Market Size 2023 | USD 1,690 million |
| Law Enforcement and Military Clothing Market, CAGR | 79.70% |
| Law Enforcement and Military Clothing Market Size 2032 | USD 183,768.61 million |
Market Overview
The Law Enforcement and Military Clothing Market is projected to grow from USD 1,690 million in 2023 to an estimated USD 183,768.61 million by 2032, with a remarkable compound annual growth rate (CAGR) of 79.70% from 2024 to 2032. This substantial growth highlights the increasing demand for high-performance clothing and gear designed to enhance the safety, comfort, and operational effectiveness of personnel in law enforcement and military roles.several factors are driving this market’s rapid growth, including advancements in fabric technology, heightened security concerns, and a rising focus on enhancing personnel safety. Trends such as the adoption of smart textiles, integration of lightweight materials, and environmentally sustainable production methods are also shaping the market. The increasing demand for body armor and tactical gear, combined with the growing emphasis on defense modernization programs globally, further accelerates market expansion.Geographically, North America and Europe are the dominant regions due to their high defense budgets and focus on innovation in military apparel. However, the Asia-Pacific region is experiencing robust growth, attributed to increased defense spending in countries like China and India. Key players in the Law Enforcement and Military Clothing Market include companies such as 3M, BAE Systems, Honeywell International Inc., DuPont, and ArmorSource LLC. These players are consistently investing in research and development to improve product offerings and meet the evolving needs of military and law enforcement personnel worldwide.
Market Drivers
Rising Global Security Threats and Increasing Defense Budgets
One of the primary drivers of the Law Enforcement and Military Clothing Market is the increasing number of security threats worldwide, including terrorism, regional conflicts, and geopolitical tensions. Governments across the globe are ramping up their defense budgets to strengthen their military and law enforcement capabilities in response to these challenges. The growing need for specialized clothing that provides protection, durability, and comfort for personnel in high-risk environments is critical in these scenarios.For instance, the U.S. military spent approximately $820.3 billion in 2023, with a significant portion allocated to advanced protective gear and specialized clothing for personnel operating in extreme climates and hostile environments. Similarly, the introduction of ballistic vests in the 1970s significantly reduced officer fatalities in shootouts, highlighting the critical need for protective clothing in law enforcement. Military operations in extreme climates or hostile environments demand advanced fabrics that are resistant to both environmental hazards and ballistic threats. Similarly, law enforcement personnel, especially in urban environments, require clothing that offers mobility, protection against blunt force, and adaptability to various weather conditions. As nations allocate more resources to their security apparatus, the demand for high-performance clothing that meets the rigorous standards of defense and law enforcement agencies has risen substantially.
Advancements in Textile and Material Technologies
Another key factor driving the growth of this market is the significant advancements in textile and material technologies. Innovations in fabric technology have enabled the development of lightweight, durable, and multifunctional materials that offer superior protection against various threats, such as ballistic impacts, fire, and chemical hazards. These materials are not only strong and protective but are also designed for comfort and flexibility, essential for soldiers and law enforcement personnel who need to remain agile during operations. For instance, the Intelligence Advanced Research Projects Activity (IARPA) launched the SMART ePANTS program in 2023, aiming to develop smart textiles that integrate audio, video, and geolocation sensors into clothing. These innovations provide real-time monitoring and enhanced safety for military and law enforcement personnel. Additionally, advancements in fabric technology have led to the development of self-cleaning textiles and wearable technology integration, which offer superior protection and functionality. Smart textiles, which integrate sensors and monitoring systems, are also gaining traction in the military and law enforcement sectors. These smart fabrics allow for real-time monitoring of the wearer’s vital signs, providing critical data on their health and performance in the field. Additionally, these fabrics can detect environmental hazards, such as chemical or biological threats, enhancing the safety of personnel. With continuous research and development efforts, the capabilities of these advanced materials are expected to grow, further driving demand in the market.
Focus on Personnel Safety and Protection
The increasing emphasis on the safety and protection of military and law enforcement personnel is another major market driver. Governments and defense organizations are placing a higher priority on ensuring that personnel are equipped with the best protective gear available. The risk of injury or death in combat or law enforcement operations can be significantly reduced with the use of specialized clothing designed to withstand harsh conditions and protect against various threats. For instance, the FBI’s Law Enforcement Officers Killed and Assaulted (LEOKA) statistics show that from 1987 through 2015, more than 70,000 officers were assaulted with firearms, and of the 1,708 officers feloniously killed in the line of duty during that period, 1,574 were killed by firearms. This highlights the critical need for advanced protective gear. Additionally, the National Law Enforcement Officers Memorial Fund reported that 136 officers died in the line of duty in 2023, emphasizing the ongoing risks faced by law enforcement personnel. This focus on safety extends beyond traditional bulletproof vests or helmets. Modern military and law enforcement clothing incorporates a range of protective features, including flame resistance, moisture-wicking properties, and protection against chemical and biological agents. Furthermore, body armor and tactical vests are being designed with modular components, allowing personnel to adapt their gear based on the specific mission or threat they face. As these safety requirements become more stringent, the demand for innovative and highly protective clothing is set to rise.
Modernization and Technological Integration in Defense Forces
Another significant driver is the ongoing modernization of military and law enforcement forces across the globe. As defense forces seek to update their equipment and enhance operational effectiveness, clothing and personal protection equipment have become critical areas of focus. This trend includes not only the adoption of advanced materials but also the integration of wearable technology into uniforms and gear.Wearable technology, such as communication systems, body cameras, and integrated heads-up displays, is becoming more common in modern military uniforms. These technologies provide real-time data to commanders and enhance situational awareness for soldiers on the ground. Similarly, law enforcement officers are increasingly relying on body cameras and other wearable tech to document interactions and improve accountability. The integration of these technologies into clothing is driving innovation in the market, as manufacturers work to create garments that can seamlessly incorporate electronic components while maintaining comfort and durability. In addition to technological integration, defense forces are also looking to modernize their clothing to enhance operational efficiency. Lightweight and versatile uniforms, which reduce the physical strain on soldiers and officers, are becoming a priority. For instance, the ability to carry more equipment without sacrificing mobility is crucial for personnel in the field. As modernization efforts continue, the demand for clothing that supports these technological and operational needs is expected to grow.
Market Trends
Integration of Smart Fabrics and Wearable Technology
One of the most prominent trends in the market is the increasing adoption of smart fabrics and wearable technology in military and law enforcement clothing. These advanced textiles are designed to improve situational awareness, enhance communication capabilities, and monitor the health and performance of personnel in real-time. For example, uniforms embedded with sensors can track vital signs such as heart rate, body temperature, and hydration levels, which are essential for monitoring a soldier’s or officer’s well-being during high-stress operations. This capability not only helps ensure personnel safety but also enables commanders to make informed decisions based on the physical state of their teams. Wearable technology is also becoming more integrated into uniforms, with features such as GPS tracking, heads-up displays, and built-in communication systems. These advancements provide personnel with critical information without requiring additional bulky devices. Additionally, with the increasing adoption of body cameras and other monitoring devices, manufacturers are designing clothing that can seamlessly incorporate such equipment, further enhancing the functionality of uniforms. The trend toward multifunctional and tech-enabled clothing reflects a growing need for efficient, adaptable, and high-performance gear in the field.
Focus on Lightweight, Durable, and Environmentally Sustainable Materials
There is a strong emphasis on developing lightweight and durable materials that can withstand extreme environments and provide better protection. Innovations in textile technology have enabled the creation of fabrics that are not only resilient but also lighter, offering improved mobility and comfort for military and law enforcement personnel. For example, advancements in ballistic-resistant fibers have led to protective clothing that offers the same level of protection as traditional materials but with reduced weight, which is critical in high-mobility situations. For instance, body armor made from Kevlar and Ultra-High-Molecular-Weight Polyethylene (UHMWPE) provides high protection while being lightweight and durable. Additionally, body armor recycling programs have been implemented to repurpose materials like Kevlar and UHMWPE, reducing environmental impact and conserving resources. Sustainability has also become a key consideration in material selection. Defense organizations and law enforcement agencies are increasingly interested in environmentally friendly materials as part of broader efforts to reduce their ecological footprint. Recycled fibers, biodegradable fabrics, and water-efficient manufacturing processes are gaining popularity. This shift reflects a growing commitment to sustainability in the defense and law enforcement sectors, which aligns with broader trends toward greener practices. As organizations prioritize sustainability, they are likely to adopt eco-friendly clothing options, further driving innovation and competition within the market.
Market Restraints and Challenges
High Production Costs and Budget Constraints
The development and manufacturing of advanced military and law enforcement clothing require significant investments in specialized materials, innovative technologies, and extensive research and development. Smart textiles, ballistic-resistant fabrics, and integrated wearable technologies all come at a premium. These advanced materials and technologies are often costly to produce, leading to higher overall production costs, which can impact the affordability of the final product. For government agencies and defense organizations, budget constraints may limit their ability to invest in the latest protective clothing solutions. Budget limitations are particularly challenging for smaller countries or municipalities with limited defense or law enforcement funding. While large nations with robust defense budgets can accommodate these expenses, smaller organizations may struggle to provide their personnel with high-quality, modern clothing. Additionally, fluctuations in global defense budgets due to economic factors or shifting political priorities can impact the market, leading to uncertainty for manufacturers and suppliers.
Complex Regulatory and Compliance Requirements
The Law Enforcement and Military Clothing Market is highly regulated, with stringent standards governing product safety, durability, and effectiveness. Manufacturers must adhere to numerous national and international regulations, such as ballistic resistance certifications and environmental compliance standards, which can vary significantly across regions. Meeting these requirements often involves complex testing, certification processes, and documentation, adding both time and cost to the production process. Navigating these regulatory landscapes can be challenging, especially for companies seeking to expand their products to new markets with different compliance standards. Failing to meet regulatory requirements can lead to significant penalties, loss of government contracts, and reputational damage. Moreover, as new materials and technologies are developed, regulatory bodies may update their standards, requiring companies to continually adapt and comply. These compliance challenges can hinder innovation and slow the pace at which new, advanced products are brought to market, impacting the overall growth of the industry.
Market Segmentation Analysis
By Function
Function-based segmentation in the Law Enforcement and Military Clothing Market categorizes apparel by specific protective features, with flame-resistant clothing emerging as a key segment due to its critical role in safeguarding personnel exposed to fire hazards in combat, training, or hazardous material handling. This segment is gaining momentum as the demand for high-performance gear that can withstand extreme heat grows, with flame-resistant apparel offering essential protection by reducing burn injuries and prolonging escape time during fire incidents-a standard requirement in various military branches and specialized law enforcement units. The “Others” category encompasses a broad range of functional clothing addressing needs like chemical resistance, moisture-wicking, UV protection, and ballistic resistance, which are increasingly integrated into standard-issue uniforms and tactical gear. This reflects a trend toward adaptable, multifunctional protective clothing, designed to provide versatile protection for personnel in diverse environments.
By Material
Material-based segmentation in the Law Enforcement and Military Clothing Market reflects the use of textiles tailored to specific performance needs. Aramid fibers, with their exceptional heat resistance and strength, are crucial for flame-resistant and ballistic-resistant gear, including body armor and tactical vests, making them a defense sector staple. Nylon is popular for its durability, lightweight nature, and abrasion resistance, making it ideal for tactical gear and outerwear where mobility and longevity are essential. Cotton fibers, prized for comfort and breathability, are often blended with other materials for uniforms suited to warm-weather and training environments. Viscose and polyester, both synthetic, are gaining traction for their moisture-wicking and resilient properties; polyester, especially, is valued for its quick-drying ability, which is ideal for outerwear. Finally, wool remains important for cold-weather gear, offering insulation and breathability, and is especially useful for providing warmth in extreme climates.
Segments
Based on Function
- Flame-Resistant Apparel
- Others
Based on Material
- Aramid
- Nylon
- Cotton Fibers
- Viscose
- Polyester
- Wool
Based on End-use
- Law Enforcement
- Defense
Based on Distribution Channel
- Direct sales
- Online Platforms
- Third-party Retailers
Based on Region
- North America
- US
- Canada
- Mexico
- Europe
- Germany
- France
- UK
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
Regional Analysis
North America (35%):
North America holds a significant share of the Law Enforcement and Military Clothing Market, accounting for approximately 35% of the global market share. The United States, with one of the largest defense budgets in the world, drives the region's market growth. A strong focus on national security and a high level of investment in military and law enforcement personnel are primary drivers in this region. Furthermore, North America has a well-established base of companies specializing in advanced protective clothing and technologies, enabling continuous innovation. Demand for advanced materials such as flame-resistant and ballistic-resistant fabrics is high, driven Based on rigorous safety standards and frequent modernization initiatives within the U.S. military and law enforcement agencies.
Europe (25%):
Europe represents around 25% of the global market share and is a significant player due to its focus on enhancing defense capabilities and updating military gear. The United Kingdom, France, and Germany are the primary contributors, each with substantial defense budgets and active involvement in international security initiatives. European defense forces emphasize modernization programs that prioritize protective gear incorporating smart textiles and eco-friendly materials, aligning with broader sustainability goals. As a result, the demand for technologically advanced, sustainable, and durable clothing solutions is growing in this region. Europe also benefits from strict regulatory standards that drive high-quality production and innovation in the protective clothing market.
Key players
- Ansell Ltd
- 3M
- DAIKIN
- VF Corporation (U.S.)
- L. Gore & Associates Inc.
- Honeywell International Inc.
- Kimberly-Clark Corp
- DuPont
- International Enviroguard
Competitive Analysis
The Law Enforcement and Military Clothing Market is highly competitive, with established players focusing on innovation, quality, and performance. Companies such as 3M, DuPont, and Honeywell International Inc. lead the market with their extensive experience and investment in advanced material technologies, particularly in flame-resistant and ballistic-resistant fabrics. W. L. Gore & Associates Inc. and Ansell Ltd are also key contributors, known for their innovative approaches to protective clothing, including breathable, weather-resistant, and durable gear. Additionally, VF Corporation and Kimberly-Clark Corp emphasize multifunctional clothing, incorporating lightweight, comfortable materials for enhanced mobility. DAIKIN and International Enviroguard are notable for their focus on specialized protective solutions for extreme environments, showcasing a range of offerings tailored to the specific needs of military and law enforcement personnel. This competitive landscape drives continuous product development and differentiation as companies strive to meet evolving safety standards and operational requirements.
Recent Developments
- In November 2023, Ansell introduced the Trellchem ACT protective suit for law enforcement responders dealing with Chemical, Biological, Radiological, and Nuclear (CBRN) terrorism incidents.
- In January 2024, DuPont and Point Blank Enterprises announced an exclusive partnership to offer body armor made with Kevlar EXO aramid fiber for North America State and Local Law Enforcement departments.
Market Concentration and Characteristics
The Law Enforcement and Military Clothing Market is moderately concentrated, with several key players holding significant market share due to their expertise in advanced material technology and strong global presence. Companies like 3M, DuPont, and Honeywell International Inc. dominate the market through continual investments in research and development, focusing on innovation in flame-resistant and ballistic-resistant fabrics. The market is characterized Based on high barriers to entry, given the stringent regulatory requirements and need for specialized manufacturing processes. Additionally, there is a strong emphasis on durability, multifunctionality, and comfort, as manufacturers strive to provide clothing that enhances personnel safety and operational efficiency in extreme environments. Market leaders typically benefit from established relationships with government agencies and defense organizations, while emerging players seek to differentiate themselves through sustainable materials and cutting-edge wearable technology
Report Coverage
The research report offers an in-depth analysis based on Function, Material, End-use, Distribution Channel and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market is expected to see a rise in demand for smart textiles that incorporate sensors and monitoring systems, allowing real-time tracking of vital signs and environmental conditions.
- As personnel prioritize mobility, manufacturers will increasingly focus on developing lightweight, durable fabrics that provide high levels of protection without sacrificing comfort.
- With growing defense budgets in countries like China and India, the Asia-Pacific region is poised for significant market expansion, driving the demand for advanced military and law enforcement clothing.
- Sustainability is becoming a priority, leading to the development of eco-friendly materials and production processes that reduce the environmental impact of protective clothing.
- Wearable technology, including body cameras and heads-up displays, will likely become standard in uniforms, enhancing situational awareness and communication capabilities for personnel
- As global security concerns persist, there will be continued demand for flame-resistant and ballistic-resistant gear to protect personnel in high-risk situations.
- The market will shift toward customizable and modular clothing options, allowing personnel to adapt their gear to specific missions or environments for greater versatility.
- With evolving safety standards, manufacturers will need to adapt to stricter regulations, ensuring their products meet enhanced protection and quality requirements.
- To maintain competitiveness, companies will invest heavily in R&D, driving innovation in advanced materials and integrated technology solutions for military and law enforcement clothing
- As security needs rise, governments worldwide will likely establish more partnerships and contracts with industry players, fostering steady growth and creating opportunities for long-term collaborations.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected market size for the Law Enforcement and Military Clothing Market in 2023 and 2032, and its CAGR?
What factors are driving growth in the Law Enforcement and Military Clothing Market?
Which regions hold the largest share in the Law Enforcement and Military Clothing Market?
What role does wearable technology play in the future of military and law enforcement clothing?
Who are the leading companies in the Law Enforcement and Military Clothing Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Law Enforcement And Military Clothing Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Law Enforcement And Military Clothing Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 1,690 million → 2032: USD 183,768.61 million)
- 2.1.2 Volume & Revenue – Global Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Law Enforcement And Military Clothing Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Law Enforcement And Military Clothing Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Law Enforcement And Military Clothing Market Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Law Enforcement And Military Clothing Market Drivers
- 3.3 Law Enforcement And Military Clothing Market Restraints & Challenges
- 3.4 Law Enforcement And Military Clothing Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Law Enforcement And Military Clothing Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Law Enforcement And Military Clothing Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Law Enforcement And Military Clothing category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Law Enforcement And Military Clothing Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Region – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Priority market opportunity scorecards reflect the geographic scope and strategic relevance of the study. Listed markets are indicative and may be adapted to the industry.
Chapter 5. Law Enforcement And Military Clothing Cross-Border Trade & Market Access Analysis
- 5.1 International Trade & Cross-Border Activity Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023) (Volume Where Applicable)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter applies where cross-border trade or delivery is relevant to Law Enforcement And Military Clothing. Goods, services, and digital offerings are assessed using applicable classifications and transaction measures. Import-export volumes, trade balances, and route analyses are included only where meaningful to the market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Law Enforcement And Military Clothing Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Law Enforcement And Military Clothing Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company (Volume Where Applicable)
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Global Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Law Enforcement And Military Clothing Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Law Enforcement And Military Clothing (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Law Enforcement And Military Clothing
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Law Enforcement And Military Clothing Market – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share (Volume Where Applicable)
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region (Volume Where Applicable)
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. North America Law Enforcement And Military Clothing Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Law Enforcement And Military Clothing Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Law Enforcement And Military Clothing Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Law Enforcement And Military Clothing Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Law Enforcement And Military Clothing Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Law Enforcement And Military Clothing Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Law Enforcement And Military Clothing Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
