
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Light Engine Market Size 2024 | USD 30,550.74 million |
| Light Engine Market , CAGR | 12.6% |
| Light Engine Market Size 2032 | USD 78,945.76 million |
Market Overview:
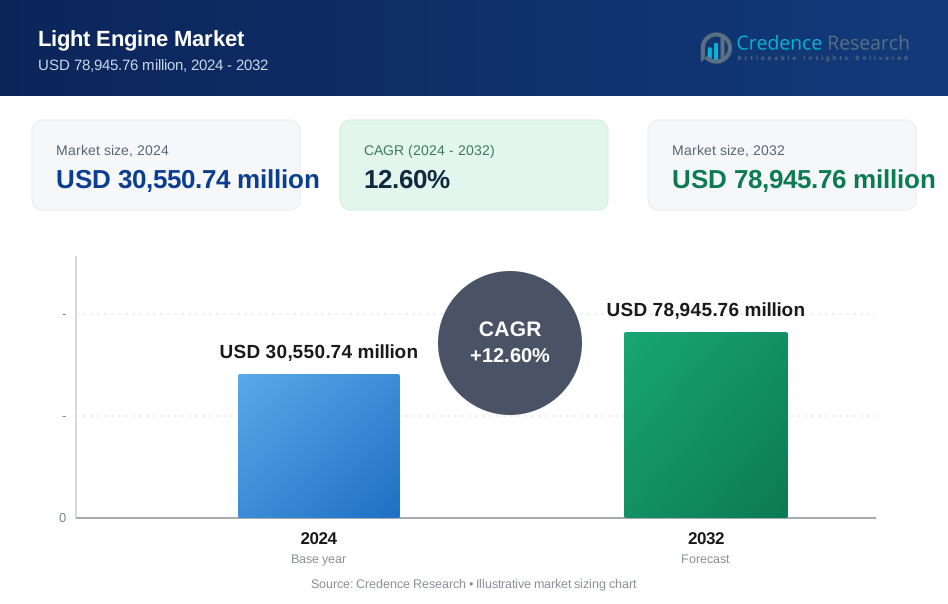
The Light Engine Market is poised for remarkable growth, with its market size projected to increase from USD 30,550.74 million in 2024 to approximately USD 78,945.76 million by 2032, registering a robust compound annual growth rate (CAGR) of 12.6% during the forecast period. This growth is driven by the increasing demand for energy-efficient lighting solutions and the widespread adoption of LED technology across commercial, industrial, and residential applications. Light engines, which consist of LEDs, drivers, and heat sinks, provide improved energy savings, enhanced longevity, and flexible design options, making them highly sought after across diverse sectors.
Key market drivers include the rising focus on energy conservation and sustainability initiatives, which are spurring demand for LED-based lighting solutions. Governments worldwide are promoting the use of efficient lighting systems by introducing stringent energy regulations and phasing out incandescent and conventional lighting sources. Technological advancements in smart lighting systems, offering features such as automation, remote control, and adaptive brightness, further contribute to market growth. Additionally, declining prices of LED components, coupled with increasing investments in infrastructure development and urbanization, are driving the adoption of light engines across multiple sectors, from commercial buildings to automotive lighting.
Regionally, Asia-Pacific holds a prominent share of the Light Engine Market due to rapid industrialization, increasing urbanization, and strong government initiatives promoting energy efficiency in countries like China, India, and Japan. North America and Europe are also significant markets, driven by the high adoption rate of smart lighting systems, a growing emphasis on sustainable infrastructure, and favorable regulatory frameworks. The Middle East & Africa and Latin America are expected to witness steady growth as rising awareness about energy-efficient lighting and ongoing infrastructure projects propel demand. This regional growth reflects a global effort to shift towards eco-friendly lighting solutions and modernized lighting systems.
Market Drivers:
Energy Efficiency and Environmental Regulations:
The increasing emphasis on energy conservation and environmental sustainability is a major driver of the light engine market. Governments worldwide are implementing stringent regulations to phase out inefficient lighting solutions in favor of energy-saving technologies. For example, the European Union’s Ecodesign Directive mandates significant reductions in energy consumption for lighting products, driving the transition to LED-based light engines. According to the U.S. Department of Energy, LED lighting was responsible for reducing energy consumption by over 17% in 2022 alone. Such measures have prompted industries and consumers alike to adopt light engines for their superior efficiency and reduced environmental impact.
Adoption of Smart Lighting Solutions:
The demand for smart lighting solutions, powered by light engines, is growing due to increasing interest in connected homes and intelligent infrastructure. Smart lighting systems offer features like remote control, adaptive brightness, and automation, which enhance energy efficiency and convenience. For instance, Signify, formerly known as Philips Lighting, has been instrumental in deploying smart lighting solutions across smart cities, resulting in substantial energy savings. In 2023, global installations of smart lighting solutions grew by 20%, reflecting strong market demand for integrated, automated light engines.
Technological Advancements in LED and OLED Technologies:
Advances in LED and organic light-emitting diode (OLED) technologies have enhanced the performance and versatility of light engines, enabling a broader range of applications. Modern light engines offer higher brightness, greater durability, and superior color rendering. Companies like Osram have invested heavily in developing innovative LED modules with longer lifespans and lower energy consumption. In 2022, the global efficiency of LEDs improved by 10% on average, further cementing their position as the go-to technology in light engine markets worldwide.
Declining Costs and Increased Accessibility:
The declining cost of LED components and associated light engine technologies has made high-performance lighting solutions more accessible across various end-user sectors. According to a 2022 report by the International Energy Agency (IEA), LED prices have fallen by 85% since 2010, encouraging widespread adoption. For instance, retail chains, offices, and municipalities are transitioning to LED-based light engines due to lower initial costs and significant long-term savings. The combination of cost reduction and improved availability continues to drive the market's growth trajectory.
Market Trends:
Growth of Human-Centric Lighting (HCL) Solutions:
A major trend in the light engine market is the increasing focus on human-centric lighting (HCL) solutions, which are designed to enhance human health and well-being by mimicking natural daylight patterns. HCL systems can influence mood, productivity, and overall well-being by adjusting color temperature and intensity. For example, studies by the National Renewable Energy Laboratory in 2022 indicated that HCL systems in workplaces improved employee productivity by 15% and reduced fatigue-related complaints. Light engines with tunable features are at the core of these solutions, driving demand across healthcare, education, and corporate environments.
Expansion of Miniaturized and Flexible Light Engines:
Another emerging trend is the development of miniaturized and flexible light engines for integration into compact and unconventional applications. Flexible OLED panels are gaining popularity due to their lightweight and bendable characteristics, making them ideal for automotive, architectural, and wearable applications. For instance, in 2023, BMW integrated flexible light engines into its concept vehicles, enhancing aesthetics and functionality. This trend underscores growing demand for customizability in light engines, driven by evolving design needs and space-saving requirements.
Increased Integration of IoT in Lighting Systems:
The integration of the Internet of Things (IoT) into lighting systems continues to shape the light engine market. IoT-enabled light engines allow for remote monitoring, predictive maintenance, and automated controls, improving efficiency and user experience. According to a 2023 survey by the IoT Analytics Group, over 40% of new lighting installations in commercial buildings featured IoT capabilities. For example, GE Current, a Daintree company, has developed smart lighting solutions for warehouses, allowing centralized control and data analytics to optimize energy consumption and maintenance.
Emphasis on Sustainability and Circular Economy Practices:
The light engine industry is witnessing a trend toward sustainable production and circular economy practices, with companies emphasizing the recyclability and lifecycle optimization of products. For instance, signify announced in 2022 that its entire range of professional lighting products would be designed for serviceability, reusability, and recycling. This shift responds to increasing consumer and regulatory demands for eco-friendly products, reflecting a broader industry move toward sustainability and responsible resource use.
Market Challenges Analysis:
High Initial Costs and Capital Investment Requirements:
One of the key restraints in the Light Engine Market is the relatively high initial cost of LED and advanced light engine solutions compared to traditional lighting technologies. Despite long-term cost savings due to energy efficiency and lower maintenance, the upfront costs can be a barrier for small and medium-sized enterprises (SMEs) and cost-sensitive markets. This challenge is particularly prevalent in regions with limited access to financing for energy-efficient upgrades. The International Energy Agency (IEA) has noted that higher initial investment requirements can deter widespread adoption, especially in emerging economies.
Complex Integration and Compatibility Issues:
Light engines, especially in advanced applications like smart and connected lighting, often require complex integration with existing infrastructure and systems. Compatibility issues can arise when incorporating new technologies with legacy lighting systems or building management platforms. The U.S. Department of Energy (DOE) has highlighted the need for industry-wide standards and interoperability to ensure seamless integration, emphasizing that these issues can slow market growth and increase installation costs for end-users.
Lack of Awareness and Expertise:
The lack of awareness and expertise in designing and implementing advanced light engine systems remains a key market challenge. While the benefits of LED and smart lighting solutions are well-documented, end-users may lack sufficient knowledge about optimal deployment and maintenance. The European Lighting Association has called for increased education and training initiatives to bridge this knowledge gap, which is critical for maximizing the performance and lifespan of light engine technologies.
Environmental and Regulatory Compliance Challenges:
Compliance with environmental and regulatory standards related to lighting efficiency, safety, and disposal presents challenges for market participants. For example, the European Union’s Restriction of Hazardous Substances (RoHS) directive and similar regulations in other regions demand strict adherence to minimize environmental impact, which can complicate production processes and raise costs. Meeting evolving standards and adapting to new regulations remains a pressing issue for industry players.
Market Segmentation Analysis:
By Type
The Light Engine Market can be segmented by type, including LED modules, lamps, and luminaires. LED modules dominate this segment due to their widespread adoption in various applications, offering high efficiency, long lifespans, and superior design flexibility. Luminaires are also gaining traction as they offer complete lighting solutions integrated with advanced light engines, suitable for commercial, industrial, and residential applications. Lamps, while increasingly being replaced by modules and luminaires, continue to hold a notable market share in retrofitting applications.
By Technology
Segmentation by technology includes LED, OLED, and other emerging technologies. LED light engines dominate the market due to their energy efficiency, cost-effectiveness, and suitability for diverse applications. OLED technology, characterized by its flexibility, uniform lighting, and aesthetic appeal, is rapidly gaining market interest, particularly in niche applications such as automotive and architectural lighting. Innovations in both LED and OLED technologies are continuously driving market advancements and expanding their use cases.
By End User
The end-user segment of the Light Engine Market covers commercial, industrial, residential, automotive, and outdoor lighting applications. The commercial sector holds a significant share due to the adoption of energy-efficient and smart lighting solutions in offices, retail spaces, and public buildings. Industrial applications are driven by the need for durable, high-performance lighting in manufacturing and warehousing. The automotive segment is experiencing growth through the integration of advanced light engines in headlamps and interior lighting systems, while residential users continue to adopt light engines for energy savings and aesthetics.
Segmentations:
By Application
- Residential
- Commercial
- Industrial
- Others
By Form
- Flexible
- Rigid
- Linear
- Round
- Others
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
Asia-Pacific
Asia-Pacific holds the largest market share, accounting for approximately 40% of the global Light Engine Market. This dominant position is driven by rapid industrialization, urbanization, and the strong push for energy-efficient lighting across countries such as China, India, and Japan. China, being the world's largest producer and consumer of LED lighting, significantly contributes to the region’s market share through government-backed energy-saving initiatives and massive infrastructure projects. In India, government programs like UJALA (Unnat Jyoti by Affordable LEDs for All) have accelerated LED adoption, further propelling market growth. Japan remains a key player, emphasizing innovative lighting technologies and high adoption rates of OLED and advanced LED solutions.
North America
North America accounts for roughly 25% of the market share and continues to be a significant region due to the high demand for energy-efficient and smart lighting solutions. The United States leads this regional market, driven by robust investments in smart buildings and IoT-enabled lighting systems. Regulatory mandates such as energy-efficiency standards set by the U.S. Department of Energy (DOE) promote widespread adoption of advanced light engines. Canada follows suit with a strong focus on sustainability and smart city initiatives, boosting demand for modern lighting technologies across commercial and industrial sectors.
Europe
Europe holds around 22% of the market share and demonstrates steady growth due to stringent environmental regulations and a strong focus on energy conservation. The European Union’s Ecodesign Directive and policies promoting the use of LED-based solutions continue to drive market demand. Key countries such as Germany, France, and the United Kingdom lead in adopting sustainable and smart lighting technologies. The demand for energy-efficient lighting in commercial, residential, and outdoor applications underscores Europe’s commitment to reducing energy consumption and carbon emissions.
Middle East & Africa
The Middle East & Africa region represents approximately 8% of the global market share, with increasing demand for energy-efficient lighting solutions driven by rapid infrastructure development and urbanization. Key countries like the UAE and Saudi Arabia are leading regional adoption, particularly in smart city projects and modern infrastructure initiatives. Investments in LED-based street lighting and commercial lighting systems contribute to steady growth.
Latin America
Latin America accounts for about 5% of the market share. The region is gradually transitioning to energy-efficient lighting solutions, supported by government incentives and public awareness campaigns. Countries like Brazil and Mexico are at the forefront of adopting light engine technologies, driven by infrastructure development and energy-saving initiatives aimed at reducing electricity consumption.
Key Player Analysis:
- OSRAM Licht Group
- Philips Lighting Holdings B.V.
- Fulham Co., Inc.
- MaxLite, Inc.
- Tridonic
- General Electric Company
- Fusion Optix, Inc.
- Thomas Research Products
- Cree, Inc.
- RS Components Pty Ltd.
Competitive Analysis:
The Light Engine Market is highly competitive, with a mix of global leaders and emerging players striving for market dominance through technological innovation, strategic partnerships, and diverse product offerings. Major companies such as OSRAM Licht Group, Philips Lighting (now Signify), and Cree, Inc. focus on research and development to deliver energy-efficient, high-performance lighting solutions tailored to commercial, residential, and industrial sectors. These market leaders leverage their extensive distribution networks and expertise in LED and OLED technologies to maintain competitive advantages. Emerging companies and niche players, such as Fulham Co., Inc., introduce specialized light engines to target evolving customer needs, particularly in smart and customizable lighting solutions. Competition is further intensified by rapid technological advancements, declining component prices, and increasing demand for sustainable lighting, compelling market participants to innovate continuously and differentiate their offerings to capture market share.
Recent Developments:
- In March 2023, OSRAM launched the OSLON® Pure 1010 LEDs, designed for high-density applications, offering superior color consistency and compactness, catering to the growing demand for miniaturized lighting solutions.
- In June 2023, signify expanded its Interact IoT platform, integrating advanced light engines with smart controls to enhance energy efficiency and user experience in commercial and industrial settings.
- In January 2024, Cree introduced the XLamp® Element G LEDs, delivering unprecedented lumen density and efficacy, aimed at high-performance lighting applications requiring compact form factors.
- In September 2022, Tridonic unveiled its fifth-generation SLE LED modules, featuring improved color rendering and efficiency, designed for retail and hospitality lighting where quality of light is paramount.
Market Concentration & Characteristics:
The Light Engine Market is moderately fragmented, with a blend of major global players and smaller specialized firms shaping the competitive landscape. Established companies such as OSRAM Licht Group, Signify (Philips Lighting), and Cree, Inc. hold significant market shares, leveraging their extensive expertise, technological innovation, and broad distribution networks to maintain competitive advantages. These key players focus on continuous research and development, particularly in LED, OLED, and smart lighting technologies, to cater to diverse consumer needs. The market is characterized by rapid technological advancements, declining costs of LED components, and strong demand for energy-efficient and customizable lighting solutions. Smaller firms and new entrants target niche applications and emerging trends, such as smart lighting and human-centric designs, driving innovation and competition. Regulatory pressures and environmental mandates further shape market dynamics, encouraging companies to prioritize sustainability and product longevity in their offerings.
Report Coverage:
The research report offers an in-depth analysis based on Application, Form, and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Increasing adoption of LED and OLED technologies will drive innovations in energy-efficient and high-performance lighting solutions.
- Demand for smart and connected lighting systems will continue to rise, driven by advancements in IoT and automation technologies.
- Miniaturization of light engines will enable new applications in compact and flexible designs for automotive, architectural, and wearable lighting.
- Human-centric lighting solutions, which prioritize well-being by mimicking natural daylight, will gain broader adoption in workplaces, healthcare, and residential settings.
- Regulatory pressures for environmental compliance and energy efficiency will accelerate the shift toward sustainable light engine designs.
- Expansion of light engines in automotive applications, such as adaptive headlamps and interior lighting, will support market growth and innovation.
- Integration of AI and data analytics in light engines will enhance lighting customization, maintenance, and predictive control capabilities.
- Increased investments in infrastructure projects, particularly in developing regions, will drive demand for energy-efficient and smart lighting solutions.
- Cost reductions in LED components and advanced manufacturing techniques will improve accessibility and stimulate market adoption across various sectors.
- Industry players will focus on sustainable and circular economy practices, emphasizing recyclability, modularity, and resource optimization in light engine designs.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Light Engine Market?
What factors are driving the growth of the Light Engine Market?
What are some challenges faced by the Light Engine Market?
Who are the major players in the Light Engine Market?
Which segment is leading the market share?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Light Engine Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Light Engine Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 30,550.74 million → 2032: USD 78,945.76 million)
- 2.1.2 Volume & Revenue – Global Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Light Engine Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Light Engine Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Light Engine Market Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Light Engine Market Drivers
- 3.3 Light Engine Market Restraints & Challenges
- 3.4 Light Engine Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Light Engine Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Light Engine Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Light Engine category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Light Engine Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Region – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Priority market opportunity scorecards reflect the geographic scope and strategic relevance of the study. Listed markets are indicative and may be adapted to the industry.
Chapter 5. Light Engine Cross-Border Trade & Market Access Analysis
- 5.1 International Trade & Cross-Border Activity Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024) (Volume Where Applicable)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter applies where cross-border trade or delivery is relevant to Light Engine. Goods, services, and digital offerings are assessed using applicable classifications and transaction measures. Import-export volumes, trade balances, and route analyses are included only where meaningful to the market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Light Engine Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Light Engine Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company (Volume Where Applicable)
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Global Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Light Engine Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Light Engine (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Light Engine
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Light Engine Market – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share (Volume Where Applicable)
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region (Volume Where Applicable)
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. North America Light Engine Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Light Engine Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Light Engine Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Light Engine Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Light Engine Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Light Engine Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Light Engine Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
