
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Light Enhancement Film Market Size 2023 | USD 214.8 Million |
| Light Enhancement Film Market, CAGR | 7.4% |
| Light Enhancement Film Market Size 2032 | USD 380.24 Million |
Market Overview:
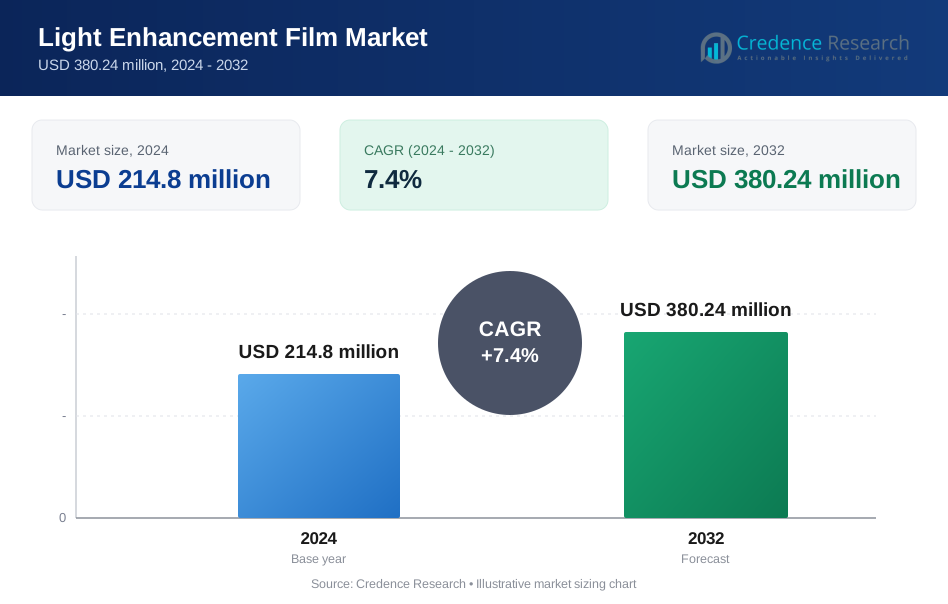
The Light Enhancement Film Market is projected to grow from USD 214.8 million in 2024 to an estimated USD 380.24 million by 2032, with a compound annual growth rate (CAGR) of 7.4% from 2024 to 2032.
Several factors drive the growth of the Light Enhancement Film market. One primary driver is the increasing demand for energy-efficient and sustainable display solutions. LEFs play a crucial role in enhancing display brightness and color uniformity while reducing power consumption, making them an attractive choice for electronics manufacturers seeking energy savings. Furthermore, the rapid advancements in display technology and the adoption of high-resolution displays across industries such as consumer electronics, automotive, and digital signage fuel market demand. The shift towards miniaturized and compact displays in devices like smartphones, tablets, and wearable technology is also spurring demand for LEF, as these films optimize display performance within limited space. Additionally, the ongoing trend towards eco-friendly products and government regulations encouraging energy-efficient solutions provide a favorable environment for LEF market expansion.
Regionally, the Asia-Pacific (APAC) market dominates the Light Enhancement Film market, driven by the high concentration of electronics manufacturers and a strong demand for advanced display solutions. Countries like China, Japan, and South Korea are leading contributors, with significant investments in research and development to support innovations in display technology. North America also holds a substantial share of the LEF market, primarily due to the presence of key technology companies and a rising demand for high-quality display systems in consumer electronics and automotive sectors. Europe is witnessing moderate growth in the LEF market, supported by the increasing adoption of eco-friendly technologies and stringent energy regulations. Emerging economies in Latin America and the Middle East and Africa are expected to contribute to market growth as they increase investments in consumer electronics and digital infrastructure, presenting new opportunities for LEF manufacturers in these regions.
Market Drivers:
Growing Demand for Energy-Efficient Display Technologies:
One of the key drivers of the Light Enhancement Film (LEF) market is the increasing demand for energy-efficient display technologies across various industries. As display devices, including smartphones, televisions, and tablets, continue to become more advanced, manufacturers are increasingly focused on enhancing energy efficiency to meet consumer demand for longer battery life and sustainable products. LEFs improve display brightness and color vibrancy, allowing devices to operate at lower power levels without sacrificing visual quality. This energy efficiency is especially critical in portable electronic devices where battery life is a top priority. For instance, LED technology can save over 1,400 million tons of CO2 and avoid the construction of 1,250 power stations. As more consumers and industries prioritize energy-saving solutions, the demand for LEF technologies is expected to grow substantially.
Advancements in Display Technology:
The rapid pace of innovation in display technology is another significant factor driving the LEF market. With the ongoing development of high-resolution screens, including 4K and 8K displays, as well as OLED and Mini-LED technologies, the need for light enhancement films has grown. LEFs are integral in optimizing the performance of these advanced display types by enhancing brightness and uniformity, which improves visual clarity and color accuracy. As the market shifts toward ultra-thin displays and flexible screens, LEFs provide the necessary enhancement while contributing to overall display thinness and durability. These technological advancements position LEFs as an essential component for manufacturers aiming to deliver premium-quality, high-performance displays.
Rising Adoption in Automotive Displays:
The automotive industry’s increasing integration of advanced displays in vehicle dashboards, infotainment systems, and head-up displays (HUDs) is a strong driver for the LEF market. Modern vehicles increasingly rely on displays for navigation, entertainment, and real-time information, creating a demand for films that enhance screen visibility and reduce glare, especially in varying lighting conditions. LEFs provide better brightness and contrast, ensuring that critical information remains clearly visible to drivers and passengers. Furthermore, as autonomous and electric vehicles continue to gain traction, automakers are investing in innovative display technologies to differentiate their offerings. This rising demand for sophisticated, energy-efficient automotive displays is driving LEF market growth, as manufacturers seek solutions that enhance visibility, reduce power consumption, and withstand the harsh conditions of automotive environments.
Government Regulations and Eco-Friendly Trends:
Government regulations promoting energy efficiency and sustainable technology practices are also influencing the growth of the LEF market. Across many regions, including North America, Europe, and Asia-Pacific, regulatory bodies are enforcing stricter energy efficiency standards for electronic devices. These regulations encourage manufacturers to integrate components that reduce energy consumption, aligning with LEF’s role in improving display efficiency. In addition, consumer preferences are increasingly shifting toward eco-friendly products, prompting manufacturers to invest in greener technologies. For example, the U.S. Department of Energy estimates that new building energy codes and proposed standards can potentially save more than $15 billion in net costs over the next 30 years and reduce emissions equivalent to the annual carbon emissions of 14.4 million homes. LEFs contribute to this trend by enabling displays to operate efficiently with reduced environmental impact, as they help lower energy usage and enhance overall device performance. As companies strive to comply with regulations and address eco-conscious consumers, the demand for LEFs that support sustainable technology will continue to increase, further propelling market growth.
Market Trends:
Increased Integration in Consumer Electronics:
The Light Enhancement Film (LEF) market is seeing heightened adoption within the consumer electronics sector, driven by the demand for brighter, more energy-efficient displays in devices like smartphones, tablets, and televisions. As consumers seek improved visual experiences, manufacturers are increasingly incorporating LEFs to enhance display brightness, color uniformity, and clarity. The rising popularity of OLED and Mini-LED technologies, particularly in high-end televisions and mobile devices, has further fueled this trend. These advanced displays require solutions like LEFs to optimize light output while minimizing power consumption. As the consumer electronics market continues to expand globally, driven by new device launches and rapid technology advancements, the role of LEFs in delivering superior display performance is expected to grow.
Rising Demand for Automotive Displays:
In the automotive industry, the integration of sophisticated displays is reshaping vehicle interiors, creating new opportunities for the LEF market. Modern vehicles now feature a range of digital displays, from infotainment and navigation systems to digital instrument clusters and heads-up displays. LEFs play a crucial role in enhancing the visibility and clarity of these screens, especially under challenging lighting conditions such as direct sunlight. Additionally, as the industry moves towards electric and autonomous vehicles, the demand for interactive and high-quality display solutions is expected to rise. Automakers are focused on incorporating displays that are not only energy-efficient but also capable of delivering a clear and engaging user experience. Consequently, LEF manufacturers are innovating to meet the specific requirements of automotive applications, driving further adoption within this sector.
Growing Emphasis on Eco-Friendly Technologies:
With the global push towards sustainability, there is an increasing focus on eco-friendly technologies within the LEF market. Consumers and manufacturers alike are becoming more aware of the environmental impact of electronic devices, leading to a shift towards components that contribute to energy efficiency and reduce carbon footprints. LEFs support this trend by improving display brightness without requiring additional power, which aligns with the energy-saving and environmental goals of electronics manufacturers. Moreover, regulatory bodies worldwide are implementing stricter guidelines on energy efficiency, further encouraging companies to adopt LEFs as part of their commitment to sustainability. This trend towards greener electronics is expected to continue shaping the LEF market, as companies seek innovative ways to enhance device performance while adhering to environmental standards.
Technological Advancements and Customization:
Technological advancements in the LEF market are driving trends toward increased customization and improved performance. Manufacturers are developing specialized LEFs tailored for specific applications, such as ultra-thin films for compact devices or films with enhanced durability for automotive and industrial displays. Additionally, research and development efforts are focused on creating films that can provide superior light enhancement while maintaining flexibility and reducing material costs. These advancements enable device manufacturers to integrate LEFs that are precisely aligned with the performance requirements of various display technologies. For instance, data from companies like Kessler Optics and Photonics Solutions and Riverdi Sp. z o.o. show the benefits of customized LEFs in different applications. Customization not only enhances the functionality of displays but also provides opportunities for LEF manufacturers to address diverse market needs, positioning them as valuable partners in the supply chain of the electronics industry. As these technologies continue to evolve, the market for LEFs is expected to grow, driven by the demand for highly specialized, high-performance optical solutions
Market Restraints and Challenges:
High Production Costs:
One of the primary restraints in the Light Enhancement Film (LEF) market is the high production cost associated with manufacturing these advanced optical films. LEFs require precise manufacturing processes and high-quality raw materials, leading to elevated production costs. These expenses are often passed on to end users, making LEFs more expensive compared to other display enhancement options. This cost factor can limit adoption, especially among price-sensitive segments, such as mid-range and budget consumer electronics manufacturers. For example, manufacturing LEFs involves complex processes like sputtering and vacuum deposition, which require costly equipment and tooling. As a result, LEF manufacturers face the ongoing challenge of optimizing production methods to reduce costs without compromising the films’ performance and quality.
Intense Competition from Alternative Technologies:
The LEF market also encounters significant competition from alternative technologies, such as quantum dot films and other advanced optical enhancement materials. Quantum dots, for example, offer benefits like improved color accuracy and enhanced brightness, making them attractive to display manufacturers. As these alternative technologies continue to advance, they may provide comparable or superior performance to LEFs, potentially reducing the market share for light enhancement films. To remain competitive, LEF manufacturers must invest in continuous research and development to differentiate their products and offer unique advantages that alternative technologies may not provide.
Dependence on Consumer Electronics Market Trends:
The LEF market’s growth is closely tied to the consumer electronics industry, which is highly dynamic and subject to rapid changes in technology and consumer preferences. Shifts in display technology trends, such as the transition from LCD to OLED or the adoption of foldable and flexible screens, can impact the demand for specific types of LEFs. Additionally, fluctuations in consumer electronics demand, influenced by economic cycles and market saturation, pose challenges for LEF manufacturers. To mitigate this risk, companies must remain adaptable and agile, continuously innovating to align with emerging trends and maintaining a diversified customer base across multiple industries.
Market Segmentation Analysis:
By Product type, the market includes Brightness Enhancement Film (BEF), Diffuser Film, Reflective Film, and Others. BEF holds a significant share due to its ability to improve brightness in display applications, making it essential in high-demand sectors like consumer electronics. Diffuser films, which help distribute light evenly across screens, are widely used in backlight units, while reflective films enhance light utilization, reducing energy consumption. These films cater to different performance needs, which helps drive adoption across various display technologies.
By Application, the LEF market spans several segments, including Backlight Units (BLUs), Televisions, Laptops and Monitors, Smartphones and Tablets, Automotive Lighting, General Lighting, and Others. The BLU segment is a prominent application area, as LEFs play a crucial role in enhancing the brightness and uniformity of displays in devices like smartphones, tablets, and laptops. Televisions also represent a significant portion, with the increasing adoption of high-resolution displays that require improved brightness and energy efficiency. In the automotive sector, LEFs are gaining traction in dashboard displays, heads-up displays, and lighting applications, driven by the growing demand for enhanced visibility in various lighting conditions. Additionally, the general lighting segment benefits from LEFs' energy-efficient properties, making these films increasingly popular for sustainable lighting solutions. As display and lighting technologies evolve, the LEF market is expected to expand across these application areas.
Segmentation:
By Product Type:
- Brightness Enhancement Film (BEF)
- Diffuser Film
- Reflective Film
- Others
By Application
- Backlight Units (BLUs)
- Televisions
- Laptops and Monitors
- Smartphones and Tablets
- Automotive Lighting
- General Lighting
- Others
- North America
- US
- Canada
- Mexico
- Europe
- Germany
- France
- UK
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
Regional Analysis:
Asia-Pacific (APAC)
The Asia-Pacific region dominates the Light Enhancement Film (LEF) market, holding the largest market share due to the presence of major electronics manufacturers and a thriving consumer electronics industry. Countries like China, Japan, and South Korea are at the forefront, with China alone contributing a significant portion of the regional market. These countries are home to leading display technology companies, which drive the demand for LEFs to enhance display performance in products such as smartphones, televisions, and laptops. The region’s strong industrial base, coupled with high investment in research and development for display technologies, makes APAC a critical hub for LEF production and innovation. With a market share of approximately 40%, APAC is expected to continue its leadership as demand for advanced displays in consumer electronics and automotive sectors grows steadily.
North America
North America is another significant market for Light Enhancement Films, accounting for roughly 25% of the global market share. The demand in this region is primarily driven by technological advancements and the increasing adoption of high-performance displays across various applications, including automotive, healthcare, and consumer electronics. The United States, in particular, is a key player due to its robust technology sector and the presence of major electronics and automotive companies that rely on LEFs for energy-efficient and visually enhanced displays. Moreover, North America’s focus on sustainability and energy-saving technologies supports the adoption of LEFs, as these films contribute to the production of more energy-efficient electronic devices. As the automotive industry in the region increasingly incorporates digital displays, the demand for LEFs in North America is expected to grow.
Europe
Europe holds a moderate share in the LEF market, contributing around 20% to the global market. The region’s demand for LEFs is influenced by stringent environmental regulations and energy efficiency standards, which encourage the use of technologies that reduce power consumption. European countries like Germany, France, and the United Kingdom are notable for their advancements in automotive and consumer electronics sectors, where LEFs play an essential role in display enhancement. Additionally, Europe’s focus on sustainable and eco-friendly technologies aligns well with the benefits of LEFs, as they enable displays to operate more efficiently. The region also invests heavily in automotive display technologies, especially as electric vehicle (EV) adoption rises, driving demand for high-performance display solutions that improve energy efficiency and visibility.
Rest of the World (RoW)
The Rest of the World, including regions such as Latin America, the Middle East, and Africa, accounts for approximately 15% of the global LEF market share. While these regions are relatively smaller markets, they present growing opportunities as investments in digital infrastructure and consumer electronics continue to rise. Latin America, in particular, is experiencing increasing demand for electronic devices, with countries like Brazil and Mexico showing notable growth in consumer electronics and automotive displays. The Middle East and Africa are also witnessing an uptrend in the adoption of advanced technologies, driven by increased investment in infrastructure and automotive sectors. Although these markets are smaller compared to APAC, North America, and Europe, they offer considerable growth potential as the global demand for LEFs expands across emerging economies.
Key Player Analysis:
- 3M
- Boyd
- DuPONT
- Fusion Optix
- Kessler Optics and Photonics Solutions
- Luminit LLC.
- Mitsubishi Chemical Corporation
- Nitto Denko Corporation
- Rina Technology Co.Ltd.
- Riverdi Sp. z O.O.
- Yongtek
Competitive Analysis:
The Light Enhancement Film (LEF) market is highly competitive, characterized by the presence of several major players and continuous innovation to meet evolving consumer demands. Key companies, including 3M, LG Chem, and Toray Industries, lead the market with strong R&D capabilities and a focus on developing high-performance LEF products for various applications such as consumer electronics, automotive, and general lighting. These companies leverage advanced manufacturing processes and strategic partnerships to enhance product quality and expand market reach. In addition to established players, smaller and regional companies are emerging, often targeting niche markets and offering specialized solutions that address specific display technologies like OLED and Mini-LED. Intense competition encourages ongoing innovation, particularly in producing thinner, more energy-efficient films. As display technology advances and new applications emerge, competitive dynamics in the LEF market are expected to intensify, driving companies to focus on product differentiation and technological advancement.
Recent Developments:
- In December 2023, Ubright Optronics, a leading manufacturer of brightness enhancement films (BEF) for LCDs, celebrated its 20th anniversary. The company marked this milestone by broadening its focus to encompass non-LCD applications and expanding its capabilities through the acquisition of a precision coating company within its corporate group.
- In December 2022, Efun Technology partnered with RealD to develop and supply specialized 3D cinema screens. These advanced screens, featuring ultra-high reflectivity and brightness, have been installed in over 500 locations worldwide, with a strong presence in China.
Market Concentration & Characteristics:
The Light Enhancement Film (LEF) market exhibits moderate concentration, characterized by a blend of established players and emerging companies. Major firms, such as 3M, LG Chem, and Toray Industries, dominate the market, leveraging their extensive research and development capabilities, robust distribution networks, and established brand reputations to maintain competitive advantages. These companies focus on innovation to develop high-performance LEFs tailored for diverse applications, including consumer electronics, automotive, and general lighting. Emerging players and regional manufacturers are increasingly entering the market, often specializing in niche segments or innovative technologies. This dynamic fosters a competitive landscape that encourages continuous improvement in product quality and functionality. The market is also characterized by a growing emphasis on sustainability and energy efficiency, as manufacturers respond to consumer demand for eco-friendly solutions. Overall, the LEF market is evolving rapidly, with both established and new players contributing to its growth and diversification.
Report Coverage:
The research report offers an in-depth analysis based on By Product Type and By Application. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The Light Enhancement Film market is expected to witness robust growth, driven by increasing demand for energy-efficient display technologies across various industries.
- Advancements in display technologies, such as OLED and Mini-LED, will significantly boost the adoption of LEFs to enhance visual performance.
- The automotive sector will increasingly integrate LEFs into digital dashboards and infotainment systems, spurring demand for high-quality displays.
- Growing consumer awareness of sustainability will lead to greater emphasis on eco-friendly LEFs, aligning with global energy-saving initiatives.
- The rise of smart devices and wearables will create new opportunities for LEF applications in compact, high-performance displays.
- Emerging markets in Latin America and Africa will contribute to market expansion as digital infrastructure investments increase.
- Competitive dynamics will intensify, driving innovation and product differentiation among existing and new market players.
- Collaborations and partnerships between manufacturers and technology firms will facilitate the development of advanced LEF solutions.
- Customization will become a key trend, with manufacturers offering tailored LEFs for specific applications and industries.
- Regulatory pressures for energy efficiency will further propel the adoption of LEFs in consumer electronics and lighting solutions.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the Light Enhancement Film market?
What factors are driving the growth of the Light Enhancement Film market?
Which regions are leading in the Light Enhancement Film market?
What are the challenges faced by the Light Enhancement Film market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Light Enhancement Film Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Light Enhancement Film Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 214.8 million → 2032: USD 380.24 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Light Enhancement Film Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Light Enhancement Film Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Light Enhancement Film Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Light Enhancement Film Market Drivers
- 3.3 Light Enhancement Film Market Restraints & Challenges
- 3.4 Light Enhancement Film Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Light Enhancement Film Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Light Enhancement Film Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Light Enhancement Film category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Light Enhancement Film Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Light Enhancement Film Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Light Enhancement Film market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Light Enhancement Film Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Light Enhancement Film Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Light Enhancement Film Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Light Enhancement Film (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Light Enhancement Film Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Light Enhancement Film Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Light Enhancement Film Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Light Enhancement Film Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Light Enhancement Film Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Light Enhancement Film Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Light Enhancement Film Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Light Enhancement Film Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Light Enhancement Film Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
