
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
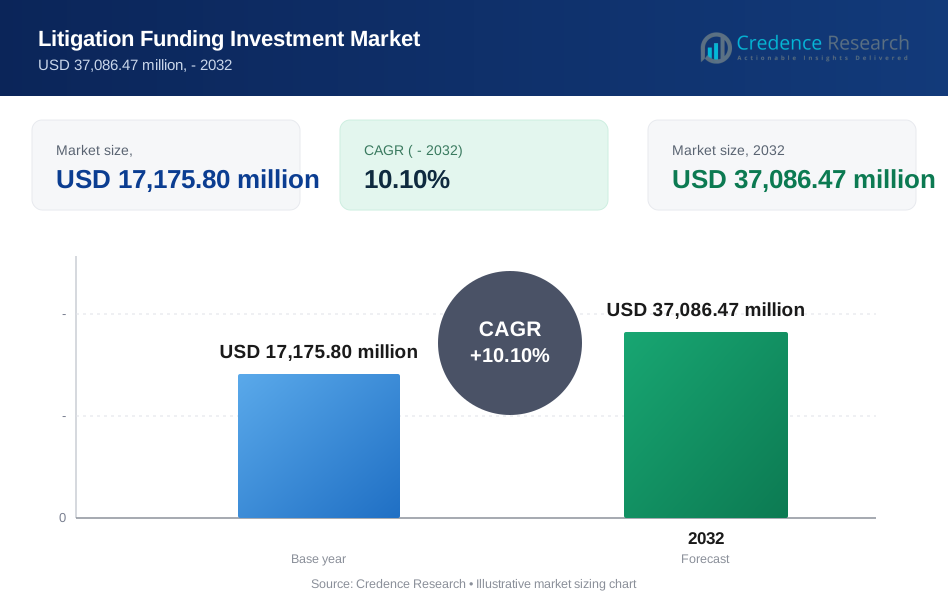
| Litigation Funding Investment Market Size 2024 | USD 17,175.80 Million |
| Litigation Funding Investment Market, CAGR | 10.10% |
| Litigation Funding Investment Market Size 2032 | USD 37,086.47 Million |
Market Overview
The global Litigation Funding Investment Market is projected to grow from USD 17,175.80 million in 2024 to an estimated USD 37,086.47 million by 2032, with a compound annual growth rate (CAGR) of 10.10% from 2025 to 2032. This growth is driven by the increasing demand for alternative financing options in the legal sector and the growing trend of non-recourse financing, which allows claimants to pursue legal cases without upfront costs.
Key drivers of the litigation funding market include rising litigation costs, the need for businesses to manage cash flow, and increasing corporate awareness of legal funding options. Additionally, advancements in legal technologies and the growing acceptance of litigation funding by both the public and private sectors are expected to shape market dynamics. These trends are making litigation funding a more viable option for both individuals and companies involved in complex legal battles. Furthermore, the trend of institutional investment in legal cases is expected to increase, creating new opportunities in the market.
Geographically, North America holds the largest share of the market, driven by a robust legal system and a high demand for litigation financing. Europe follows closely, with significant growth anticipated in the UK and Germany. Key players in the market include Burford Capital, Augusta Ventures, IMF Bentham, and LexShares, which are leading the way in providing innovative litigation funding solutions to businesses and individuals globally.
Market Insights
- The global litigation funding market is projected to grow from USD 17,175.80 million in 2024 to USD 37,086.47 million by 2032, with a CAGR of 10.10% from 2025 to 2032.
- The rising complexity and cost of legal disputes are driving the demand for alternative financing options like litigation funding, allowing claimants to pursue cases without upfront costs.
- The escalating costs of legal cases, particularly in corporate and commercial disputes, are a key driver, leading businesses to seek third-party funding to manage these expenses.
- The absence of universal regulatory standards across regions poses a challenge, with concerns over transparency, fairness, and potential conflicts of interest.
- Increasing participation from institutional investors, such as pension funds and sovereign wealth funds, is fueling market growth by providing more capital for larger cases.
- North America holds the largest market share, with Europe, especially the UK and Germany, following closely due to their established legal frameworks and high demand for litigation financing.
- As legal systems in regions like Asia-Pacific and Latin America mature, the market for litigation funding is expected to grow rapidly, offering new opportunities for investors and funders.
Market Drivers
Increasing Litigation Costs and Complexity
The rising costs of legal disputes, combined with the increasing complexity of cases, are major drivers of growth in the global litigation funding investment market. As legal battles become more intricate, requiring specialized expertise and resources, the financial burden on businesses and individuals seeking justice becomes more significant. High litigation costs can deter individuals and companies from pursuing cases that have a high chance of success but are financially prohibitive. Litigation funding addresses this issue by providing capital to fund legal proceedings, allowing claimants to pursue cases without upfront costs. This funding model is especially beneficial for cases that could take years to resolve, such as class action lawsuits or intellectual property disputes, where the claimant might otherwise lack the necessary funds to pay for extensive legal representation.For instance, the increasing complexity of litigation-backed transactions has led to innovative financial strategies such as litigation portfolio financing. This approach combines multiple cases into a single structure, reducing overall risk by diversifying outcomes and enabling funds to free up capital for new opportunities. By enabling access to justice without the need for personal or corporate investment, litigation funding plays a crucial role in empowering claimants, ultimately driving market demand.
Need for Alternative Financing in a Competitive Legal Environment
With the legal industry becoming increasingly competitive, especially in regions like North America and Europe, law firms and corporations are actively seeking ways to reduce their financial risk and improve their chances of success. Litigation funding serves as an attractive alternative financing solution for businesses, law firms, and individuals who may lack the resources to bear the financial burden of litigation. Funding allows parties to maintain their cash flow while pursuing high-stakes legal actions. The growing number of litigation cases involving large corporations, particularly in sectors such as technology, pharmaceuticals, and finance, has led to an increasing reliance on third-party funding to support complex lawsuits.Similarly, law firms are adopting alternative billing structures like contingency fee monetization, which allows them to generate immediate liquidity by anticipating future revenue from successful cases. This trend helps optimize cash flow without waiting for case resolutions, showcasing the strategic benefits of litigation funding in addressing financial constraints. Additionally, litigation funding helps level the playing field, enabling smaller firms or claimants with limited resources to compete against larger and better-financed opponents. The rise of mass claims and class actions in regions like France and the EU highlights how litigation funding empowers claimants to pursue complex disputes. This funding model ensures access to justice even for smaller firms or individuals facing well-financed opponents in high-stakes legal battles.
Institutional Investment and Institutionalization of Legal Financing
One of the key factors driving the growth of the litigation funding market is the increasing involvement of institutional investors. Historically, litigation funding was seen as a niche market dominated by private investors and hedge funds. However, over the past decade, institutional investors such as pension funds, endowments, and insurance companies have recognized the potential for high returns in litigation financing. The institutionalization of legal financing has led to a surge in capital available for funding large-scale litigation. This influx of institutional capital has not only expanded the scope of cases that can be funded but has also increased the professionalism and transparency of the industry. Institutional investors bring an added layer of credibility and efficiency to litigation funding, which further enhances its appeal to corporate clients and law firms. This shift toward institutional investment is expected to be a significant driver of market growth, as it provides a more stable and scalable source of funding, supporting an increasing number of high-value and long-duration cases.
Growing Acceptance and Regulatory Advancements
The increasing acceptance of litigation funding within the legal community and its evolving regulatory landscape are also important drivers of the market. Initially, litigation funding faced skepticism due to concerns over ethical issues, such as the potential for conflicts of interest, and questions about its impact on legal processes. However, as the industry has matured, many jurisdictions have enacted or refined regulations governing litigation funding, providing clearer guidelines and greater transparency. In countries like the United States, the United Kingdom, and Australia, legal reforms have helped to normalize the practice of third-party funding by ensuring ethical compliance and protecting the interests of all parties involved in legal proceedings. The growing body of legal frameworks governing litigation funding is fostering trust among businesses and law firms, which in turn is increasing the overall adoption of funding services. As litigation funding becomes more mainstream, more organizations are expected to embrace this financing model to manage the financial risks associated with complex legal cases. Moreover, as legal professionals and courts become more familiar with litigation funding structures, the process is likely to become increasingly streamlined, reducing barriers to entry for new market participants and enhancing the growth potential of the industry.
Market Trends
Integration of Technology and Data Analytics in Risk Assessment
As litigation funding continues to evolve, there is a growing trend towards the integration of technology and data analytics into the decision-making process. Litigation funders are increasingly relying on advanced algorithms, artificial intelligence (AI), and machine learning to evaluate the viability of potential cases and assess the risks involved. These technologies help funders analyze vast amounts of data related to previous cases, predict the likelihood of success, and calculate potential returns on investment. By leveraging data analytics, funders are able to make more informed and precise investment decisions, improving the overall efficiency and profitability of their portfolios.Additionally, technology is being used to streamline the due diligence process, making it easier for funders to access and analyze legal documents, court rulings, and other relevant data. AI-powered tools are being employed to predict case outcomes, analyze legal trends, and identify patterns that may have been difficult to detect manually. This trend is driving increased automation in litigation funding, reducing human error and speeding up the funding decision-making process. The use of technology not only improves the accuracy of risk assessments but also makes the litigation funding process more transparent, efficient, and scalable. As technology continues to advance, its role in litigation funding is expected to expand further, enabling funders to manage larger portfolios and support more complex legal cases.
Regulatory Advancements and Growing Legal Frameworks
As the litigation funding industry grows, so does the need for clear and robust regulatory frameworks to govern its operations. A growing trend in the market is the continued development of legal and regulatory frameworks that ensure the transparency, fairness, and ethical standards of litigation funding. In many regions, such as the United States, the United Kingdom, and Australia, regulators are increasingly focused on defining the legal boundaries of litigation funding, providing more certainty to funders, law firms, and claimants alike. These regulatory advancements aim to address concerns around potential conflicts of interest, ethical practices, and the financial fairness of funding arrangements.Additionally, jurisdictions are clarifying the legal status of third-party funding agreements, which is crucial for the continued growth of the market. For instance, in some countries, litigation funding is still viewed with suspicion due to concerns about its potential to influence legal outcomes or disrupt traditional legal processes. However, the development of comprehensive legal frameworks that govern litigation funding ensures that these concerns are addressed, promoting greater trust in the industry. As regulators continue to fine-tune these frameworks, the industry is likely to become more standardized, reducing barriers to entry and enabling greater participation from both funders and claimants. Furthermore, ongoing regulatory clarity is expected to lead to enhanced legitimacy and credibility for the litigation funding industry as a whole.
Shift Towards Institutional Investment and Larger Funding Pools
One of the most prominent trends in the global litigation funding investment market is the increasing involvement of institutional investors, such as pension funds, hedge funds, insurance companies, and sovereign wealth funds. This shift from individual or smaller-scale investors to large institutional players is a significant transformation that has expanded the capital pool available for funding litigation. Institutional investors bring substantial financial resources, which allows for the funding of larger and more complex cases that require high levels of capital and long-term commitment. In turn, this trend has led to a greater emphasis on rigorous risk assessment and due diligence processes, as institutional investors demand higher standards of transparency and accountability in litigation funding agreements.For instance, institutional investors like pension funds and hedge funds are now actively involved in litigation funding, providing substantial capital that enables the pursuit of complex legal cases. This shift has not only increased the financial capacity of the market but also spurred the development of structured multi-case portfolios. These portfolios diversify risk across multiple lawsuits and offer stable income streams for investors. The entry of institutional players has also contributed to market maturation, fostering more sophisticated funding models and innovative solutions that enhance flexibility in deal structuring while aligning with investors' long-term financial goals.
Expansion of Funding Models Beyond Traditional Case-by-Case Approaches
A significant trend in the litigation funding market is the move toward more diverse and flexible funding models that go beyond the traditional, case-by-case funding approach. Initially, litigation funding was structured around single-case investments, where third-party funders provided capital for a specific lawsuit in exchange for a portion of the proceeds if the case was successful. However, the evolving nature of litigation finance has led to the development of more complex and tailored funding models, such as portfolio funding, hybrid funding, and corporate funding agreements.For example, portfolio funding has become a popular strategy where funders finance a group of legal cases, spreading risk across multiple lawsuits. This approach reduces the impact of any single case's outcome on the overall portfolio. Hybrid funding models have also emerged, combining elements of traditional funding with loan structures to provide greater flexibility for law firms and claimants. Corporate funding agreements are increasingly utilized by businesses to finance litigation efforts as part of broader strategies, such as intellectual property disputes or class-action lawsuits. These innovative models not only improve risk management but also align financial goals between funders and clients. By enabling strategic investment opportunities, these approaches are transforming how legal claims are financed in industries where multi-party and multi-jurisdictional cases are common.
Market Challenges
Regulatory and Ethical Challenges in Litigation Funding
One of the primary challenges facing the global litigation funding investment market is the lack of a universally agreed-upon regulatory framework, which often leads to legal uncertainties and ethical concerns. While some regions, such as the United States, the United Kingdom, and Australia, have made strides in establishing regulations governing third-party funding, many countries still lack clear guidelines or enforceable laws on how litigation funding should operate.For instance, in the United States, which is currently the largest market for litigation funding, there is no federal regulation that applies to litigation funding, and the matter has been left to individual states to address. This lack of uniformity creates a complex landscape for funders and litigants alike. In the European Union, the parliament has recently identified several issues with litigation funding from a regulatory perspective and has recommended establishing a system of authorization for litigation funders, along with enforcement measures and complaint systems at the national level.The absence of a standardized regulatory framework can create a fragmented market, where funders must navigate varying legal landscapes across jurisdictions. This complexity can hinder the scalability and growth of the market, as businesses and law firms may be hesitant to engage in litigation funding agreements due to potential regulatory risks.Furthermore, ethical concerns surrounding third-party funding persist. Critics argue that funding arrangements may influence legal strategies and case outcomes, potentially undermining the integrity of the justice system. Issues such as conflicts of interest, where funders exert undue influence over legal decisions, or the possibility of funders pursuing cases primarily for financial gain rather than seeking justice, pose risks to the long-term sustainability of the market.
Risk Management and Unpredictable Case Outcomes
Litigation funding inherently involves significant risks, as the outcome of legal cases is often unpredictable, and there is no guarantee of success. Funding high-stakes, complex legal disputes such as class actions, intellectual property lawsuits, or multi-party litigation exposes investors to substantial financial risk, especially in cases with long durations or unclear legal precedents. While data analytics and technology have improved risk assessment in the industry, there is still a level of uncertainty that makes it difficult for funders to predict case outcomes with complete accuracy.This uncertainty is exacerbated by the unpredictable nature of judicial processes, which can be influenced by factors outside of a funder's control, such as changes in law, judicial bias, or unexpected legal developments. For investors, the potential for significant financial loss in cases that fail or are delayed is a major challenge. This risk can deter potential investors from entering the market, especially those who are not well-versed in legal intricacies or who are seeking more predictable, low-risk investment opportunities. As a result, managing these risks effectively remains a challenge for litigation funders, who must continuously refine their risk assessment models while balancing the potential for high returns with the inherent uncertainty of legal proceedings.
Market Opportunities
Expanding Demand for Litigation Financing in Emerging Markets
One of the most significant opportunities in the global litigation funding investment market lies in the expansion of litigation funding into emerging markets. Many developing regions, such as parts of Asia, Latin America, and Africa, are experiencing rapid economic growth, leading to an increase in commercial disputes and legal cases that require substantial financial resources. These markets often lack the access to capital necessary for large-scale litigation, creating a significant opportunity for investors to provide funding. As legal systems in these regions mature and global business operations expand, the demand for litigation financing will continue to grow. Funders who can navigate the regulatory challenges and legal nuances of emerging markets stand to benefit from early entry into these untapped markets, positioning themselves for long-term growth and profitability.
Increasing Corporate Use of Litigation Funding for Risk Management
Another key market opportunity lies in the growing acceptance of litigation funding as a strategic tool for corporate risk management. As businesses face increasingly complex and high-stakes legal challenges, such as intellectual property disputes, antitrust cases, and class actions, they are increasingly turning to litigation funding to mitigate financial risks. This trend is particularly evident in industries such as technology, pharmaceuticals, and energy, where companies are regularly involved in high-value legal disputes. By using litigation funding, corporations can preserve their cash flow and resources while engaging in potentially lucrative litigation without bearing the full financial burden. As more businesses recognize the benefits of litigation funding in managing legal risks, the market for corporate-funded litigation is expected to grow, providing ample opportunities for funders to offer tailored solutions to corporate clients.
Market Segmentation Analysis
By Type:
Commercial litigation is the largest and fastest-growing segment in the market. As businesses face an increasing number of disputes, including breach of contract, intellectual property infringement, and antitrust cases, the need for litigation funding has surged. This segment is driven by the high costs associated with corporate legal battles and the complexity of large-scale disputes. Commercial litigation funding enables businesses to manage financial risk while pursuing high-value cases.Bankruptcy claims represent another significant segment, where funding is often required to pursue recovery in the event of corporate insolvencies. Litigation funders provide capital to creditors, enabling them to recover funds from bankrupt entities. This segment is particularly relevant during economic downturns when bankruptcy cases rise, creating opportunities for funders to invest in potentially high-return cases.International arbitration is gaining traction as a preferred method for resolving cross-border disputes, particularly in industries such as energy, construction, and finance. The increasing globalization of business activities, combined with the rising costs of international legal proceedings, is driving the demand for litigation funding in this segment.Personal injury cases are another prominent segment, especially in jurisdictions with a well-established legal framework for compensation. Litigation funding is widely used by individuals who cannot afford the high costs of personal injury claims. This segment has seen growth due to the increasing awareness of legal funding options and the rising frequency of personal injury claims.
By Enterprise Size:
Micro, Small, and Medium Enterprises (MSMEs) are increasingly adopting litigation funding to manage legal costs, particularly in complex disputes that could potentially drain their limited resources. These enterprises often face challenges in funding their litigation but can benefit from third-party financing to pursue claims without impacting their operational finances.Large enterprises, particularly those in industries with frequent high-value disputes (e.g., technology, pharmaceuticals), are increasingly using litigation funding as a strategic tool to manage risk and preserve cash flow. They often require large-scale funding for complex cases, which makes them attractive clients for funders.
Segments
Based on Type
- Commercial Litigation
- Bankruptcy Claim
- International Arbitration
- Personal Injury
Based on Enterprise Size
- Micro, Small, and Medium Enterprises (MSMEs)
- Large Enterprises
Based on End User
- BFSI and Media Entertainment
- IT & Telecommunication
- Manufacturing
- Healthcare
- Others
Based on Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America (45%)
North America holds the largest share of the global litigation funding market, with the United States accounting for the bulk of this share. The region's well-established legal system and robust commercial litigation environment make it an attractive market for litigation funders. The growing demand for funding in high-stakes commercial, intellectual property, and class-action lawsuits is a key driver of market growth. Additionally, the regulatory framework in the United States, which supports third-party funding under certain conditions, has created a favorable environment for the expansion of litigation financing. The presence of major funders, including Burford Capital and other private equity firms, further strengthens North America's dominance in this sector.
Europe (30%)
Europe is the second-largest market for litigation funding, with significant contributions from the United Kingdom, Germany, and France. The UK is particularly prominent in the market due to its legal reforms that have facilitated the growth of third-party funding, especially in commercial disputes and class actions. Germany, as the largest economy in Europe, also contributes significantly to the market, with increasing adoption of litigation funding in both domestic and cross-border disputes. The European market is driven by complex regulatory frameworks and the growing acceptance of alternative dispute resolution mechanisms, such as arbitration. As litigation funding continues to gain traction across various European jurisdictions, the region is expected to maintain its strong position in the market.
Key players
- Burford Capital LLC
- Harbour Litigation Funding Ltd
- Apex Litigation Finance
- Omni Bridgeway
- Longford Capital Management LP
Competitive Analysis
The global litigation funding investment market is highly competitive, with several key players vying for market leadership. Burford Capital LLC stands out as one of the largest and most established players, offering a broad portfolio of funding options and a robust financial track record. Harbour Litigation Funding Ltd is known for its focus on commercial litigation and international arbitration, capitalizing on its extensive experience in cross-border disputes. Apex Litigation Finance differentiates itself by offering innovative funding solutions, particularly in the corporate sector, while Omni Bridgeway is recognized for its global reach, handling high-value cases across multiple jurisdictions. Longford Capital Management LP focuses on providing capital for complex commercial disputes and bankruptcy cases, positioning itself as a specialized provider of litigation finance. The competition among these players fosters innovation and ensures diverse offerings in the market, enabling businesses to access tailored financial solutions for their legal needs.
Recent Developments
- In May 2024, Burford Capital LLC announced new independent research examining how CFOs and senior financial officers impact corporate legal departments, legal spending, and success in recovering value through affirmative recoveries1.
- In June 2024, Omni Bridgeway received the most recognitions overall and the most Band 1 rankings worldwide in the Chambers and Partners 2024 Litigation Support Guide, with twelve of their global offices and business lines recognized5.
- In July 2023, Longford Capital Management LP secured a $25 million investment from Sandton Capital Partners to support the launch and future endeavors of Thaxted Capital, a Manchester-based litigation funder4.
Market Concentration and Characteristics
The global litigation funding investment market is moderately concentrated, with a few dominant players such as Burford Capital LLC, Harbour Litigation Funding Ltd, Apex Litigation Finance, Omni Bridgeway, and Longford Capital Management LP leading the sector. These key players have a significant share due to their extensive portfolios, strong financial resources, and global presence. However, the market also consists of several smaller, specialized firms that focus on niche areas such as personal injury, bankruptcy claims, or international arbitration. The characteristics of the market include high competition among funders to offer innovative funding models, with increasing emphasis on technology and data analytics for risk assessment. As more institutional investors enter the market, the concentration is expected to grow, although regional and sector-specific players will continue to play a crucial role in catering to diverse legal needs across jurisdictions.
Report Coverage
The research report offers an in-depth analysis based on Type, Enterprise Size, End User and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The global litigation funding market is expected to experience robust growth, driven by increasing demand for alternative financial solutions in legal disputes. The market is projected to expand significantly due to rising litigation costs and complex legal cases.
- As legal systems in emerging markets such as Asia-Pacific, Latin America, and the Middle East continue to develop, litigation funding opportunities will increase. This expansion will open new avenues for investment and legal financing in these regions.
- Institutional investors, including pension funds and sovereign wealth funds, are likely to play a more prominent role in the litigation funding market. Their involvement will increase capital availability and provide more robust financing solutions for large-scale legal cases.
- The industry is anticipated to see continued innovation in funding models, including portfolio funding, hybrid financing, and corporate funding arrangements. These models will offer greater flexibility and risk management for funders and claimants alike.
- Advanced data analytics, artificial intelligence, and machine learning will become increasingly integrated into risk assessment processes. These technologies will allow funders to make more accurate predictions regarding case outcomes, enhancing investment decisions.
- With globalization on the rise, there will be an increasing demand for litigation funding in international arbitration cases. This trend will be fueled by the growing complexity of cross-border legal disputes in sectors like finance, energy, and intellectual property.
- The regulatory landscape for litigation funding will continue to evolve globally, providing more clarity and structure. These developments will help mitigate ethical concerns and encourage broader adoption of litigation financing in various jurisdictions.
- More large corporations will embrace litigation funding as a risk management tool, particularly in industries like technology and pharmaceuticals. This will contribute to the growth of funding for commercial disputes and high-value claims.
- As awareness of litigation funding grows, its use in personal injury cases and class actions is likely to increase. This trend will provide individuals and groups with greater access to justice without upfront financial burdens.
- The market will become increasingly competitive as more players enter the space, both in established and emerging regions. This competition will drive innovation, improve service offerings, and create more tailored funding solutions for a variety of legal needs.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Increasing Litigation Costs and Complexity
The rising costs and complexity of legal disputes are prompting businesses and individuals to seek alternative financing solutions, making litigation funding an attractive option to pursue cases that would otherwise be financially prohibitive.
Need for Alternative Financing in a Competitive Legal Environment
Law firms and corporations are increasingly turning to litigation funding to manage cash flow and reduce financial risk, especially in high-stakes or protracted legal battles, enabling them to compete more effectively in the legal arena.
Institutional Investment and Institutionalization of Legal Financing
The entry of institutional investors such as pension funds and sovereign wealth funds is expanding the capital pool available for litigation funding, increasing professionalism, transparency, and the ability to fund larger and more complex cases.
Growing Acceptance and Regulatory Advancements
Evolving regulatory frameworks and greater acceptance within the legal community are reducing ethical concerns and providing clearer guidelines, which is fostering trust and accelerating the adoption of litigation funding across more jurisdictions.
Integration of Technology and Data Analytics in Risk Assessment
The use of advanced analytics, artificial intelligence, and machine learning is improving risk assessment and investment decisions for funders, making the litigation funding process more efficient, scalable, and attractive to investors.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of the global litigation funding investment market in 2023 and 2032?
What is litigation funding?
What are the key drivers of growth in the litigation funding market?
Which regions dominate the global litigation funding market?
Who are the key players in the global litigation funding market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Commercial Litigation
- 1.2.2 Bankruptcy Claim
- 1.2.3 International Arbitration
- 1.2.4 Personal Injury
- 1.3 By End User
- 1.3.1 BFSI and Media Entertainment
- 1.3.2 IT & Telecommunication
- 1.3.3 Manufacturing
- 1.3.4 Healthcare
- 1.3.5 Others
- 1.4 By Enterprise Size
- 1.4.1 Micro, Small, and Medium Enterprises (MSMEs)
- 1.4.2 Large Enterprises
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 17,175.80 million → 2032: USD 37,086.47 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Litigation Funding Investment Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Litigation Funding Investment Market Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Supply Chain Structure and Procurement Trends
- 5.4 Supply-Demand Gap and Bottlenecks
- 5.5 Import Dependence and Sourcing Structure
- 5.6 Regional Supply and Demand Concentration
Chapter 6 Global Litigation Funding Investment Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Pricing by Product and Market Segment
- 6.5 Geographic Pricing Differences
- 6.6 Key Input, Energy, Labor and Logistics Costs
- 6.7 Contract Pricing and Purchasing Models
- 6.8 Pricing Sensitivity and Competitive Positioning
- 6.9 Price, Margin and Profitability Implications
Chapter 7 Global Litigation Funding Investment Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Litigation Funding Investment Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Litigation Funding Investment Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Data Protection, AI and Cybersecurity Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Litigation Funding Investment Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Litigation Funding Investment Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 17,175.80 million → 2032: USD 37,086.47 million)
- 11.1.2 Historical Market Size
- 11.1.3 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 CAGR and Year-on-Year Growth
- 11.2.3 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Litigation Funding Investment Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Base-Year Market Share, 2024
- 12.3.5 Segment CAGR and Growth Drivers
- 12.3.6 Subsegment Market Size and Forecast
- 12.3.6.1 Commercial Litigation
- 12.3.6.2 Bankruptcy Claim
- 12.3.6.3 International Arbitration
- 12.3.6.4 Personal Injury
- 12.3.7 Subsegment Pricing and Adoption Trends
- 12.3.8 Leading Suppliers and Competition
- 12.3.9 Regional Demand and Opportunities
- 12.4 By End User - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Base-Year Market Share, 2024
- 12.4.5 Segment CAGR and Growth Drivers
- 12.4.6 Subsegment Market Size and Forecast
- 12.4.6.1 BFSI and Media Entertainment
- 12.4.6.2 IT & Telecommunication
- 12.4.6.3 Manufacturing
- 12.4.6.4 Healthcare
- 12.4.6.5 Others
- 12.4.7 Subsegment Pricing and Adoption Trends
- 12.4.8 Leading Suppliers and Competition
- 12.4.9 Regional Demand and Opportunities
- 12.5 By Enterprise Size - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Base-Year Market Share, 2024
- 12.5.5 Segment CAGR and Growth Drivers
- 12.5.6 Subsegment Market Size and Forecast
- 12.5.6.1 Micro, Small, and Medium Enterprises (MSMEs)
- 12.5.6.2 Large Enterprises
- 12.5.7 Subsegment Pricing and Adoption Trends
- 12.5.8 Leading Suppliers and Competition
- 12.5.9 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Litigation Funding Investment End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Litigation Funding Investment Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Litigation Funding Investment Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Energy Efficiency and Resource Management
- 15.7 Sustainability, Recycling and Circularity
- 15.8 Technology Roadmap, 2024-2032
- 15.9 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Litigation Funding Investment Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Burford Capital LLC
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Financial Performance and Investment
- 18.2.6 Market Share and Competitive Position
- 18.2.7 Technology and Innovation Capabilities
- 18.2.8 Strategic Alliances or Partnerships
- 18.2.9 Recent Developments
- 18.2.10 Growth Strategy and Outlook
- 18.3 Harbour Litigation Funding Ltd
- 18.4 Apex Litigation Finance
- 18.5 Omni Bridgeway
- 18.6 Longford Capital Management LP
- 18.7 Augusta Ventures
- 18.8 IMF Bentham
- 18.9 LexShares
- 18.10 Therium Capital Management
- 18.11 Woodsford Litigation Funding
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

