
Low Calorie RTD Beverages Market Overview:
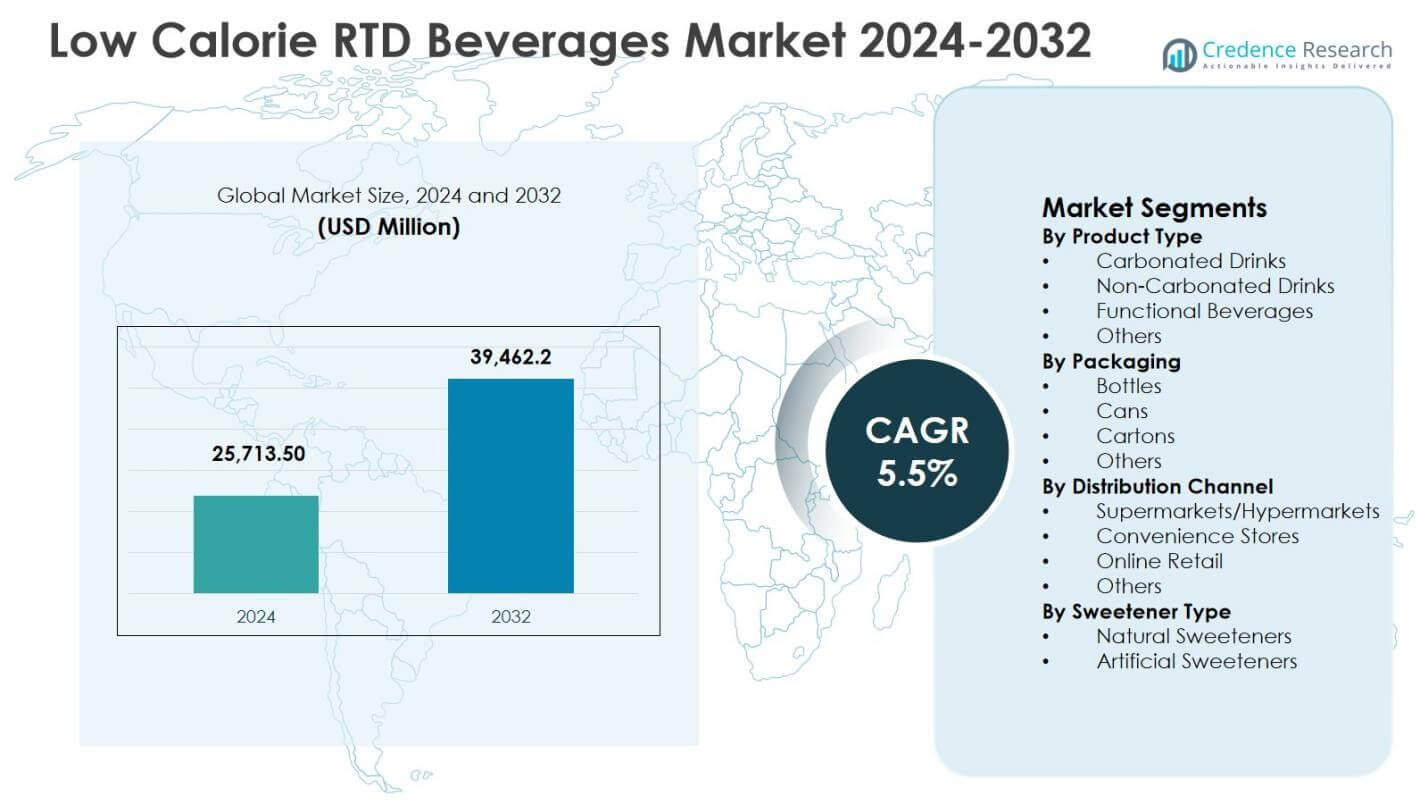
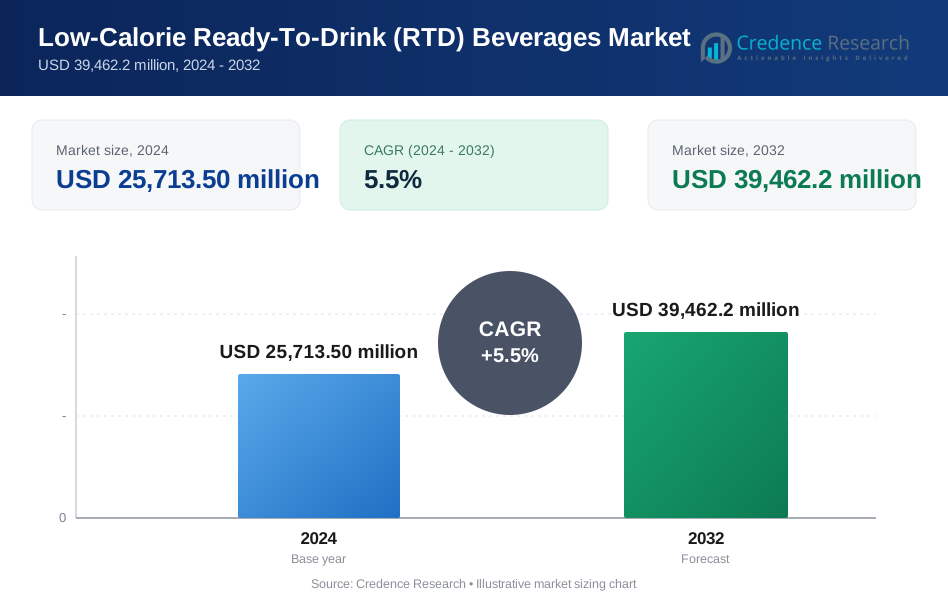
The Low Calorie RTD Beverages Market size was valued at USD 25,713.50 million in 2024 and is anticipated to reach USD 39,462.2 million by 2032, expanding at a CAGR of 5.5% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Low-Calorie Ready-To-Drink (RTD) Beverages Market Size 2024 | USD 25,713.50 million |
| Livestock Farm Equipment Market, CAGR | 5.5% |
| Livestock Farm Equipment Market Size 2032 | USD 39,462.2 million |
Low Calorie RTD Beverages Market Insights
- Market growth is driven by rising health awareness and sugar-reduction preferences, with carbonated drinks leading by product type at a 41.6% share in 2024, followed by non-carbonated drinks at 33.2% and functional beverages at 18.9%.
- Ongoing product reformulation, clean-label positioning, and expansion of zero-sugar portfolios shape market trends, while bottles dominate packaging with a 46.8% share, supported by cans at 29.4% due to recyclability and convenience.
- Pricing pressure from private labels and taste acceptance challenges act as restraints, though wide retail presence sustains demand, with supermarkets and hypermarkets accounting for a 48.9% distribution share in 2024.
- Regionally, North America led with a 34.8% share in 2024, followed by Europe at 27.6%, Asia Pacific at 24.1%, Latin America at 8.2%, and Middle East & Africa at 5.3%, reflecting varied adoption levels and retail maturity.
Low Calorie RTD Beverages Market Segmentation Analysis:
By Product Type:
The Low Calorie RTD Beverages Market by product type is led by Carbonated Drinks, which accounted for 41.6% market share in 2024, driven by strong consumer preference for low-calorie sodas and sparkling beverages as alternatives to traditional sugary soft drinks. Manufacturers continue to reformulate products using natural sweeteners and zero-sugar formulations, supporting sustained demand. Non-Carbonated Drinks followed with 33.2% share, supported by rising consumption of ready-to-drink teas and flavored waters. Functional Beverages held 18.9%, benefiting from demand for added vitamins and electrolytes, while Others represented 6.3%.
- For instance, Coca-Cola launched AHA sparkling water, offering flavors like Raspberry + Acai with 0 calories, 0g sugar, and no sweeteners per 12oz can, using only carbonated water and natural flavors.
By Packaging:
Based on packaging, Bottles dominated the Low Calorie RTD Beverages Market with a 46.8% share in 2024, supported by convenience, resealability, and strong penetration in on-the-go consumption formats. PET and glass bottles remain widely adopted across both carbonated and non-carbonated categories. Cans accounted for 29.4%, driven by growing preference for recyclable packaging and portion control benefits. Cartons captured 15.7%, particularly in functional and dairy-based low-calorie beverages, while Others, including pouches and tetra variants, held a 8.1% share due to niche applications.
- For instance, Minute Maid Light Lemonade by Coca-Cola comes in clear, recyclable 500-ml PET four-packs with 15 calories per serving across flavors like Raspberry Passion, supporting portable low-calorie refreshment.
By Distribution Channel:
In terms of distribution, Supermarkets/Hypermarkets led the market with a 48.9% share in 2024, supported by wide product availability, strong brand visibility, and promotional pricing strategies. These channels remain critical for bulk purchases and new product launches. Convenience Stores accounted for 26.7%, driven by impulse buying and urban consumption patterns. Online Retail captured 16.4%, reflecting rising e-commerce adoption and subscription-based beverage purchases. Others, including specialty and foodservice channels, represented 8.0%, supported by premium and functional low-calorie beverage offerings.
Key Growth Drivers
Rising Health and Wellness Awareness
Growing consumer awareness regarding obesity, diabetes, and lifestyle-related disorders is a major driver for the Low Calorie RTD Beverages Market. Consumers increasingly prefer beverages with reduced sugar, zero calories, and clean-label ingredients to support weight management and overall wellness. This shift is particularly strong among urban populations and younger consumers who actively monitor calorie intake. Beverage manufacturers are responding by expanding low-calorie portfolios using natural sweeteners, plant-based ingredients, and functional additives, which continues to accelerate product adoption across developed and emerging markets.
- For instance, PepsiCo introduced bubly burst, a sparkling water line with fruit flavors like Triple Berry and Peach Mango. Each serving contains 10 calories or less with no added sugar.
Product Innovation and Flavor Diversification
Continuous innovation in formulations and flavor profiles is significantly driving market growth. Manufacturers are introducing low-calorie RTD beverages with enhanced taste, natural flavors, and functional benefits such as added vitamins, electrolytes, and antioxidants. These innovations help overcome taste-related barriers traditionally associated with low-calorie products. The availability of diverse formats including sparkling waters, flavored teas, and functional drinks is expanding the consumer base. This focus on innovation enables brands to differentiate offerings, improve repeat purchases, and strengthen shelf presence.
- For instance, Twinings Sparkling Tea offers low-calorie RTD teas under 50 calories per can, fortified with antioxidant vitamin C at 30% of daily needs, alongside vitamins like D and zinc. Flavors like Defence (Orange with Passionfruit and Elderberry) and Refresh (Raspberry Lemonade with Hibiscus) use no added sugar or artificial ingredients.
Expanding Urbanization and On-the-Go Consumption
Rapid urbanization and increasingly busy lifestyles are boosting demand for convenient, ready-to-drink beverage options. Low calorie RTD beverages align well with on-the-go consumption patterns, offering convenience without compromising health goals. Growth in working populations, fitness-conscious consumers, and outdoor recreational activities further supports demand. Additionally, strong penetration of convenience stores and organized retail in urban areas improves product accessibility, reinforcing consumption frequency and supporting consistent market expansion.
Key Trends & Opportunities
Growing Demand for Functional Low-Calorie Beverages
A key trend shaping the Low Calorie RTD Beverages Market is the rising demand for functional beverages that combine low calorie content with health-enhancing benefits. Consumers increasingly seek drinks that support hydration, immunity, digestion, and energy without added sugars. This trend creates strong opportunities for manufacturers to integrate functional ingredients such as probiotics, adaptogens, electrolytes, and plant extracts. Brands that successfully balance functionality with taste and transparency can capture premium positioning and drive higher margins across health-focused consumer segments.
- For instance, Recess offers low-calorie sparkling drinks with magnesium L-threonate, L-theanine, and lemon balm adaptogens, delivering only 20 calories and 5g or less sugar per can from fruit juice to promote relaxation.
Expansion of E-commerce and Direct-to-Consumer Channels
The rapid growth of e-commerce platforms presents a significant opportunity for low calorie RTD beverage brands. Online retail enables wider product reach, personalized offerings, subscription models, and improved consumer engagement. Digital channels also support niche and premium product launches that may face shelf-space limitations in physical stores. With increasing smartphone penetration and digital payment adoption, especially in emerging economies, online channels are becoming a strategic avenue for brand building, data-driven marketing, and long-term customer retention.
- For instance, Coca-Cola utilizes online quick-commerce for low-calorie sales. Coca-Cola Zero Sugar, offering 0 kcal per 250ml bottle with zero sugars, is available via platforms like Zepto for instant delivery, enhancing accessibility in emerging markets.
Key Challenges
Taste Perception and Consumer Acceptance
Despite advancements in formulation, taste perception remains a key challenge for low calorie RTD beverages. Some consumers continue to associate low-calorie products with artificial aftertastes or reduced flavor intensity. Negative experiences can limit repeat purchases and slow adoption among mainstream consumers. Achieving taste parity with full-sugar beverages while maintaining clean-label standards requires continuous R&D investment. Brands must focus on sensory optimization and consumer education to overcome skepticism and strengthen long-term acceptance.
Regulatory Compliance and Ingredient Constraints
Stringent regulations surrounding sweeteners, labeling, and health claims pose challenges for market participants. Different regions enforce varying standards on ingredient usage, nutritional disclosures, and marketing claims, increasing compliance complexity and operational costs. Additionally, restrictions on artificial sweeteners and rising scrutiny of natural alternatives can limit formulation flexibility. Navigating evolving regulatory frameworks while maintaining product consistency and profitability remains a critical challenge for manufacturers operating across multiple geographies.
Regional Analysis
North America
The Low Calorie RTD Beverages Market in North America accounted for 34.8% market share in 2024, driven by high health awareness, strong demand for sugar-free beverages, and rapid adoption of functional low-calorie drinks. Consumers actively seek clean-label, zero-calorie, and naturally sweetened products, supporting sustained volume growth. The region benefits from well-established retail infrastructure, high penetration of convenience stores, and strong brand loyalty. Product innovation, frequent new launches, and aggressive marketing strategies further strengthen market expansion across the United States and Canada.
Europe
Europe held 27.6% market share in 2024, supported by increasing regulatory pressure to reduce sugar intake and rising consumer focus on preventive health. Low calorie RTD beverages are widely adopted across carbonated drinks, flavored waters, and functional beverages. Strong demand from Western Europe, combined with expanding consumption in Eastern Europe, supports steady growth. Sustainability-driven packaging preferences and clean-label formulations further enhance product appeal. Supermarkets and hypermarkets remain the primary sales channels, supported by strong private-label penetration.
Asia Pacific
Asia Pacific captured 24.1% market share in 2024, driven by rapid urbanization, growing middle-class populations, and rising awareness of lifestyle-related health issues. Increasing consumption of ready-to-drink teas, flavored waters, and functional beverages significantly supports demand. Countries such as China, Japan, and India are witnessing strong growth due to changing dietary habits and expanding organized retail. Rising e-commerce adoption and affordability of low calorie beverage options further strengthen market penetration across urban and semi-urban areas.
Latin America
Latin America accounted for 8.2% market share in 2024, supported by growing health consciousness and government initiatives to reduce sugar consumption. Consumers are gradually shifting from traditional sugary drinks to low calorie alternatives, particularly in urban centers. Carbonated low calorie beverages dominate demand, while functional drinks are gaining traction. Expanding modern retail formats and improving cold-chain infrastructure support wider product availability. Brazil and Mexico remain key contributors to regional growth.
Middle East & Africa
The Middle East & Africa region held 5.3% market share in 2024, driven by rising urbanization, increasing disposable incomes, and growing awareness of obesity-related health risks. Demand is concentrated in premium low calorie and functional RTD beverages, particularly in urban markets. Expanding retail infrastructure and tourism-driven consumption support growth. Although overall penetration remains lower than other regions, improving distribution networks and lifestyle changes continue to create long-term growth opportunities.
Low Calorie RTD Beverages Market Segmentations:
By Product Type
- Carbonated Drinks
- Non-Carbonated Drinks
- Functional Beverages
- Others
By Packaging
- Bottles
- Cans
- Cartons
- Others
By Distribution Channel
- Supermarkets/Hypermarkets
- Convenience Stores
- Online Retail
- Others
By Sweetener Type
- Natural Sweeteners
- Artificial Sweeteners
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
Competitive landscape analysis of the Low Calorie RTD Beverages Market is shaped by the presence of major global players including The Coca-Cola Company, PepsiCo Inc., Nestlé S.A., Danone S.A., Monster Beverage Corporation, Red Bull GmbH, Arizona Beverage Company, Unilever PLC, The Kraft Heinz Company, and Dr Pepper Snapple Group. These companies compete primarily through product innovation, sugar-reduction strategies, and expansion of low-calorie and zero-sugar portfolios. Strong investments in R&D support flavor enhancement and clean-label formulations, improving consumer acceptance. Strategic marketing, wide distribution networks, and brand loyalty strengthen market positioning, while partnerships and acquisitions help expand regional presence. Private-label competition and regional brands add pricing pressure, encouraging continuous differentiation through functional benefits, packaging innovation, and sustainability-focused initiatives.
Key Player Analysis
- Danone S.A.
- Monster Beverage Corporation
- The Kraft Heinz Company
- Arizona Beverage Company
- Unilever PLC
- Dr Pepper Snapple Group
- Nestlé S.A.
- Red Bull GmbH
- PepsiCo Inc.
- The Coca-Cola Company
Recent Developments
- In March 2025, PepsiCo acquired functional soda brand Poppi for £1.5bn ($1.95bn), which offers low-calorie RTD beverages with no more than five grams of sugar per serving through prebiotics, fruit juice, and apple cider vinegar.
- In August 2025, Pernod Ricard’s Malibu partnered with Dole Food Company to develop a new range of tropical-inspired low-calorie canned RTD cocktails, slated for early 2026 release.
- In November 2025, Ghodawat Consumer Limited (GCL) debuted Coolberg Diet, India’s first zero-sugar, zero-calorie malt beverage targeting health-conscious consumers.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Packaging, Distribution Channel, Sweetener Type and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Low Calorie RTD Beverages Market will continue expanding due to sustained consumer focus on health, wellness, and sugar reduction.
- Product innovation will accelerate, with greater emphasis on natural sweeteners, clean-label formulations, and improved taste profiles.
- Functional low-calorie beverages with added vitamins, electrolytes, and plant-based ingredients will gain stronger consumer acceptance
- Demand for convenient, on-the-go beverage formats will support higher consumption across urban and working populations.
- E-commerce and direct-to-consumer channels will play an increasingly important role in market penetration and brand engagement.
- Sustainable and recyclable packaging solutions will influence purchasing decisions and product differentiation strategies.
- Emerging markets will witness faster adoption driven by urbanization, rising disposable incomes, and changing dietary habits.
- Strategic partnerships and acquisitions will help companies expand product portfolios and geographic reach.
- Regulatory initiatives promoting sugar reduction will encourage further reformulation of existing beverage lines.
- Brand competition will intensify, pushing manufacturers to balance affordability, functionality, and sensory appeal.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Health and Wellness Awareness
Increasing consumer concern about obesity, diabetes, and lifestyle-related diseases is fueling demand for beverages with reduced sugar and calorie content. This trend is especially pronounced among urban and younger populations who are actively seeking healthier drink alternatives.
Product Innovation and Flavor Diversification
Continuous advancements in formulation and the introduction of new flavors, natural sweeteners, and functional ingredients are making low-calorie RTD beverages more appealing. These innovations help overcome taste barriers and expand the consumer base.
Expansion of Functional Low-Calorie Beverages
Consumers are increasingly looking for beverages that not only have low calories but also offer added health benefits such as vitamins, electrolytes, and adaptogens. This demand is driving manufacturers to develop multifunctional products that support hydration, immunity, and energy.
Growth of E-commerce and Direct-to-Consumer Channels
The rapid adoption of online retail platforms is making low-calorie RTD beverages more accessible, supporting niche product launches and subscription models. Digital channels enable brands to reach a wider audience and engage consumers directly, especially in emerging markets.
Urbanization and On-the-Go Consumption
Busy lifestyles and increasing urbanization are boosting demand for convenient, ready-to-drink options that align with health goals. The proliferation of convenience stores and organized retail in urban areas further supports frequent consumption and market growth.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Low Calorie RTD Beverages Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Low Calorie RTD Beverages Market projected to grow between 2024 and 2032?
Which Low Calorie RTD Beverages Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Low Calorie RTD Beverages Market?
Who are the leading companies in the Low Calorie RTD Beverages Market?
Which region commanded the largest share of the Low Calorie RTD Beverages Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Packaging
- 1.2.1 Bottles
- 1.2.2 Cans
- 1.2.3 Cartons
- 1.2.4 Others
- 1.3 By Product Type
- 1.3.1 Carbonated Drinks
- 1.3.2 Non-Carbonated Drinks
- 1.3.3 Functional Beverages
- 1.3.4 Others
- 1.4 By Sweetener Type
- 1.4.1 Natural Sweeteners
- 1.4.2 Artificial Sweeteners
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 25,713.50 million → 2032: USD 39,462.2 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Low-Calorie Ready-To-Drink (RTD) Beverages Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Low-Calorie Ready-To-Drink (RTD) Beverages Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Low-Calorie Ready-To-Drink (RTD) Beverages Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Low-Calorie Ready-To-Drink (RTD) Beverages Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Low-Calorie Ready-To-Drink (RTD) Beverages Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Low-Calorie Ready-To-Drink (RTD) Beverages Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Low-Calorie Ready-To-Drink (RTD) Beverages Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Low-Calorie Ready-To-Drink (RTD) Beverages Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 25,713.50 million → 2032: USD 39,462.2 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Low-Calorie Ready-To-Drink (RTD) Beverages Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Packaging - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Bottles
- 12.3.7.2 Cans
- 12.3.7.3 Cartons
- 12.3.7.4 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Product Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Carbonated Drinks
- 12.4.7.2 Non-Carbonated Drinks
- 12.4.7.3 Functional Beverages
- 12.4.7.4 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Sweetener Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Natural Sweeteners
- 12.5.7.2 Artificial Sweeteners
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Low-Calorie Ready-To-Drink (RTD) Beverages Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Low-Calorie Ready-To-Drink (RTD) Beverages Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Low-Calorie Ready-To-Drink (RTD) Beverages Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 The Coca-Cola Company
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 PepsiCo Inc.
- 17.4 Nestlé S.A.
- 17.5 Danone S.A.
- 17.6 Monster Beverage Corporation
- 17.7 Red Bull GmbH
- 17.8 Arizona Beverage Company
- 17.9 Unilever PLC
- 17.10 The Kraft Heinz Company
- 17.11 Dr Pepper Snapple Group
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

