
Construction Design App Market Overview:
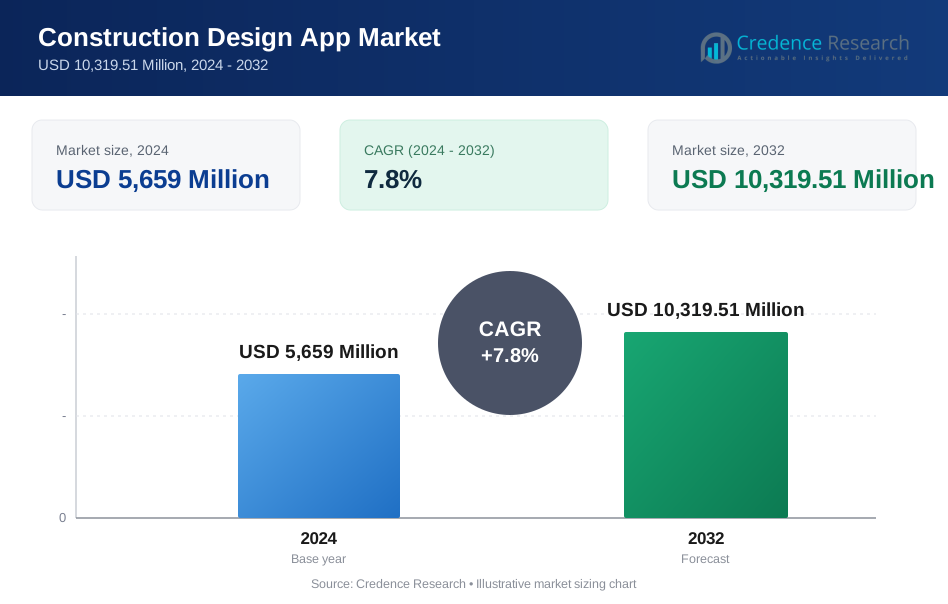
Construction Design App market size was valued USD 5,659 Million in 2024 and is anticipated to reach USD 10,319.51 Million by 2032, at a CAGR of 7.8% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2032 |
| Construction Design App Market Size 2024 | USD 5,659 million |
| Construction Design App Market, CAGR | 7.8% |
| Construction Design App Market Size 2032 | USD 10,319.51 million |
Construction Design App Market Insights
- Market drivers include rapid adoption of BIM-enabled digital design tools, growth in smart infrastructure and commercial real-estate development, and increasing demand for mobile and cloud-based collaboration across architecture, engineering, and construction teams.
- Market trends highlight rising integration of AI, AR/VR visualization, and generative design, along with expanding SaaS subscription models and cross-platform compatibility that support real-time project coordination and immersive visualization workflows.
- Competitive landscape is characterized by strong participation from Autodesk, SketchUp, Archicad, AutoCAD, Chief Architect, Planner 5D, Morpholio Trace, Magicplan, and Houzz, with vendors focusing on product upgrades, BIM integration, and enterprise collaboration ecosystems.
- Regional analysis shows North America leading with 34.6% share, followed by Europe at 27.8% and Asia-Pacific at 24.3%, while the Android platform segment dominates by platform with 42.6% share in 2024.

Construction Design App Market Segmentation Analysis:
By Platform
The Construction Design App market by platform is led by the Android segment, which accounted for 42.6% share in 2024, driven by its wider device penetration, cost-effective ecosystem, and strong adoption among SMEs and emerging-market users. iOS captured 33.8% share, supported by premium enterprise users and design professionals who prefer high-performance mobile environments. Windows held 18.4% share, driven by desktop-based design workflows in engineering firms, while Others accounted for 5.2%, reflecting niche and cross-platform solutions that support hybrid environments and cloud-based collaboration across devices.
- For instance, Autodesk’s BIM 360 and AutoCAD mobile apps are available on Android, enabling on-site drawing access and markup for contractors using mid-range smartphones.
By Type
Integrated Building Information Modeling (BIM) emerged as the dominant type with 38.9% market share, supported by increasing demand for coordinated design workflows, clash-detection capabilities, and lifecycle-based construction planning. 3D Modeling and Visualization accounted for 32.4% share, driven by immersive design presentations, AR-VR-enabled visualization, and stakeholder communication needs. Project Management Tools captured 15.6% share, reflecting the shift toward digital scheduling and resource tracking, while Compliance and Regulations and Others jointly contributed 13.1%, driven by sustainability reporting, permit documentation, and audit-ready project records.
- For instance, Autodesk Revit and Navisworks are widely used together to perform multidisciplinary clash detection and 4D construction sequencing on large projects.
By End User
Architects represented the dominant end-user segment with 41.7% share, driven by growing adoption of digital design workflows, rapid concept visualization, and increased reliance on BIM-enabled collaboration platforms. Engineers accounted for 28.9% share, supported by structural analysis integration and precise technical modeling needs. Construction managers held 21.3% share, reflecting the expansion of mobile field-coordination, site-progress tracking, and cost-control applications, while Others captured 8.1%, including interior designers, contractors, and facility planners adopting design apps to enhance accuracy, reduce rework, and accelerate project decision-making across multidisciplinary construction environments.
Key Growth Drivers
Rising Adoption of Digital Design and BIM-Integrated Workflows
The Construction Design App market is growing rapidly as the industry shifts from manual drafting and legacy desktop tools toward digital, cloud-based, and BIM-enabled design environments. Increasing pressure to improve project accuracy, reduce design rework, and accelerate approval cycles is driving widespread adoption of modeling, visualization, and coordination apps across architecture, engineering, and construction teams. Developers and contractors increasingly rely on mobile and collaborative design tools to support remote review, real-time updates, and multidisciplinary teamwork across distributed project sites. The integration of apps with BIM platforms, digital twins, and 3D visualization further enhances design intelligence, improves clash detection, and reduces costly project delays. Governments and regulatory bodies promoting digital construction standards also strengthen market growth. Together, these factors position digital design apps as core infrastructure in modern construction workflows, replacing fragmented design processes with efficient, synchronized project ecosystems.
- For instance, Autodesk has steadily expanded Autodesk Construction Cloud and Revit integrations to support cloud-based model coordination and data sharing across project stakeholders.
Growth in Urban Infrastructure, Smart Buildings, and Real-Estate Development
Rapid urbanization, large-scale infrastructure investments, and expansion in residential and commercial real-estate projects are major growth drivers for the Construction Design App market. Increasing demand for sustainable buildings, energy-efficient layouts, and space-optimization solutions is encouraging architecture and engineering firms to adopt advanced design applications for planning, visualization, and performance modeling. Smart city development initiatives, metro and transit projects, and mixed-use urban structures require higher design precision and collaborative engineering environments, which significantly boost software usage. Construction design apps also support faster feasibility analysis, accurate project costing, and flexible design iteration, helping developers shorten bid-to-execution timelines. The rising focus on modular construction, prefabrication, and off-site manufacturing further amplifies adoption, as design teams require digital tools for simulation and component alignment. This surge in infrastructure development directly fuels sustained demand for advanced construction design applications worldwide.
- For instance, Bentley Systems’ OpenBuildings and OpenRail have been deployed on complex rail and urban infrastructure programs to manage multi-disciplinary design coordination.
Mobile-First Design Ecosystems and Growing SME & Contractor Adoption
The increasing shift toward mobile-first workflows and the democratization of professional design tools among SMEs and independent contractors are accelerating market expansion. Lightweight, intuitive, and subscription-based design applications enable small firms, freelancers, and site-level project teams to access capabilities previously limited to large enterprises. Mobile design apps support on-site drawing edits, field visualization, progress markup, and real-time coordination between engineers, architects, and construction supervisors. This significantly improves communication efficiency, reduces documentation delays, and enhances decision-making during field execution. The availability of affordable SaaS pricing models, cross-platform compatibility, and integration with project management, cloud storage, and AR-VR visualization tools further encourages adoption. As digital transformation expands beyond large engineering firms into mid-scale and emerging-market construction ecosystems, mobile and collaborative design apps continue to gain strong traction as essential tools for day-to-day project workflows.
Key Trends & Opportunities
Integration of AI, AR/VR, and Generative Design for Intelligent Modeling
A major emerging trend in the Construction Design App market is the integration of AI-driven automation, AR/VR visualization, and generative design capabilities that enhance modeling accuracy and design creativity. AI-powered tools assist architects and engineers by automating repetitive drafting tasks, optimizing structural layouts, and predicting design conflicts before construction. Generative design engines enable rapid concept exploration, sustainability-driven material choices, and energy-efficient building models. Meanwhile, AR/VR technologies allow immersive design walkthroughs, remote stakeholder collaboration, and real-time spatial planning at concept and construction stages. These technologies significantly improve visualization, reduce redesign costs, and enhance client engagement. Vendors increasingly embed analytics, simulation, and digital-twin-ready workflows into design apps, unlocking new opportunities in lifecycle asset management, smart building optimization, and predictive maintenance planning. This convergence of intelligent technologies is transforming design applications from drafting tools into strategic decision-support platforms across the construction value chain.
- For instance, Unity Reflect and Trimble’s SketchUp with VR plugins enable architects and clients to review 3D models in immersive environments and adjust designs on the fly.
Expansion of Cloud-Based Collaboration and Integrated Project Ecosystems
Another key market opportunity arises from the rapid expansion of cloud-based collaboration platforms that enable unified design, documentation, and coordination across multidisciplinary project environments. Construction stakeholders increasingly prefer centralized design ecosystems that integrate BIM, project scheduling, costing, and field-execution workflows within a single connected framework. Cloud-native construction design apps support remote teamwork, version control, traceable design histories, and seamless stakeholder communication across global project teams. This trend is particularly strong in large infrastructure, industrial, and cross-border development projects where distributed engineering teams require synchronized collaboration. Integration with IoT, site-monitoring platforms, and digital documentation systems further enhances project intelligence and execution efficiency. As organizations adopt enterprise-wide digital transformation strategies, demand grows for interoperable design applications that connect design intent with real-time construction execution, creating scalable opportunities for vendors offering collaborative, secure, and enterprise-aligned design platforms.
- For instance, Procore’s platform integrates drawings, submittals, schedules, and cost data so project teams work from a common, continuously updated source of truth.
Key Challenges
High Implementation Costs, Skill Gaps, and Adoption Barriers in Emerging Markets
Despite strong growth potential, the Construction Design App market faces challenges related to high software licensing costs, hardware upgrade requirements, and limited digital skills among small contractors and regional firms. Many SMEs and traditional construction operators continue to depend on manual drafting, basic CAD tools, or fragmented workflows due to budget constraints and limited training resources. Transitioning to BIM-integrated and cloud-based design ecosystems requires process restructuring, workforce upskilling, and cultural acceptance of digital workflows, which may slow adoption in cost-sensitive markets. In emerging economies, infrastructure gaps, limited broadband access, and low awareness of digital design benefits further restrict penetration. These barriers create uneven adoption levels across regions and organization sizes, requiring vendors to invest in training programs, modular pricing strategies, and localized deployment approaches to support successful digital transformation in construction design environments.
Data Security, Interoperability Issues, and Integration Complexity
Data security risks, interoperability challenges, and integration complexity remain significant obstacles for organizations adopting construction design applications. Large engineering and construction enterprises manage sensitive project information, intellectual property, and regulatory documentation, making cybersecurity and data-governance compliance critical. Concerns over cloud data privacy, cross-platform data movement, and unauthorized access may slow cloud migration in highly regulated projects. Interoperability gaps between different BIM platforms, CAD systems, and project management tools also create workflow disruptions, data loss, and collaboration inefficiencies. Integrating design apps with legacy systems, enterprise ERP platforms, and field-execution software increases technical complexity and implementation time. Vendors must prioritize open standards, secure data frameworks, and API-driven integration architectures to address these challenges and enable seamless, secure, and scalable digital ecosystems across the global construction design landscape.
Regional Analysis
North America
North America held the largest share of the Construction Design App market in 2024, accounting for 34.6%, driven by strong adoption of BIM-integrated design platforms, advanced digital construction practices, and a mature AEC technology ecosystem. The U.S. leads the region due to extensive infrastructure modernization projects, high cloud-software penetration, and heavy investments in smart building development and commercial real-estate design. Construction firms increasingly rely on mobile design tools, AR-VR visualization, and collaborative workflows to reduce project rework and accelerate approvals. Demand continues to rise across large contractors and architectural firms, supported by technology-driven regulatory compliance and sustainability-focused design standards.
Europe
Europe accounted for 27.8% of the Construction Design App market in 2024, supported by strong government-driven digital construction mandates, widespread BIM adoption, and growing emphasis on energy-efficient and sustainable building design. The UK, Germany, and France remain key contributors, with engineering and architectural firms leveraging cloud-based modeling, advanced simulation tools, and digital documentation platforms to enhance precision and lifecycle asset management. The region’s focus on green buildings, renovation programs, and infrastructure redevelopment further strengthens demand for integrated design applications. Collaborative workflows, regulatory alignment, and public-sector digitalization initiatives continue to drive market expansion across both residential and commercial construction segments.
Asia-Pacific
Asia-Pacific emerged as the fastest-growing region with a 24.3% market share in 2024, fueled by rapid urbanization, megacity development, and large-scale infrastructure investments across China, India, Japan, and Southeast Asia. Increasing demand for affordable housing, smart city projects, and industrial construction is accelerating adoption of mobile-first and SaaS-based design applications. SMEs, local contractors, and emerging-market engineering firms are increasingly transitioning from traditional drafting tools to BIM-enabled and 3D visualization platforms. Government initiatives promoting digital construction standards, combined with expanding real-estate and commercial development activity, further strengthen regional growth momentum and position Asia-Pacific as a major future revenue contributor.
Latin America
Latin America accounted for 7.6% of the Construction Design App market in 2024, with growth driven by urban infrastructure expansion, commercial real-estate development, and gradual digitalization of design workflows in Brazil, Mexico, and Chile. Adoption remains stronger among mid-to-large engineering and architectural firms that increasingly deploy cloud-based modeling, coordination, and project documentation tools to improve design accuracy and cost control. Mobile design applications are gaining traction among contractors and site managers, particularly in metropolitan development projects. However, budget constraints, uneven technology penetration, and limited digital skill readiness moderate adoption, creating gradual but steady regional market growth.
Middle East & Africa
The Middle East & Africa region captured 5.7% share of the Construction Design App market in 2024, supported by large-scale commercial, hospitality, and infrastructure megaprojects across the UAE, Saudi Arabia, and Qatar, alongside emerging urban development in African economies. High-value smart city initiatives and state-led construction programs encourage adoption of BIM-centric design ecosystems, advanced 3D visualization, and collaborative project coordination platforms. Engineering firms increasingly deploy design apps for complex structural modeling and sustainability-focused project planning. While digital transformation is accelerating in Gulf economies, slower adoption in developing African markets results in uneven regional penetration but continued long-term growth potential.
Construction Design App Market Segmentations:
By Platform
- Android
- iOS
- Windows
- Others
By Type
- 3D Modeling and Visualization
- Project Management Tools
- Compliance and Regulations
- Integrated Building Information Modeling
- Others
By End User
- Architects
- Engineers
- Construction managers
- Others
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The Construction Design App market features a diverse and evolving competitive landscape characterized by innovation, platform integration, and expanding mobile and cloud-based capabilities. Leading players such as Autodesk, SketchUp, AutoCAD, Archicad, Chief Architect, Planner 5D, Morpholio Trace – Sketch CAD, Magicplan, Home Design 3D, and Houzz focus on enhancing BIM compatibility, 3D modeling accuracy, and cross-device collaboration to support multidisciplinary design workflows. Vendors increasingly emphasize AI-assisted drafting, AR/VR visualization, and generative design functions to improve design precision and project coordination. The market also includes niche and specialized applications that cater to contractors, interior designers, and field engineers seeking lightweight mobile design tools. Strategic initiatives include product upgrades, SaaS-based pricing models, and integration with project management and construction productivity platforms to expand enterprise adoption. Partnerships with construction technology ecosystems, cloud providers, and digital-twin solution vendors further strengthen competitive positioning, while emerging regional developers enter the market with cost-effective and localized design applications.
Key Player Analysis
- Morpholio Trace – Sketch CAD
- Chief Architect
- Planner 5D
- SketchUp
- Sun Seeker – Solar AR Tracker
- AutoCAD
- Archicad
- Houzz
- Magicplan
- Home Design 3D
Recent Developments
- In November 2025, Adani Group entered into a three-year strategic partnership with Autodesk to deploy Autodesk Construction Cloud (ACC) and provide Building Information Modeling (BIM) advisory services across its infrastructure operations globally, aimed at unifying project data and enhancing collaboration in design-to-construction workflows.
- In October 2025, Topcon Positioning Systems and Amberg Technologies announced a collaboration agreement at INTERGEO 2025 (Oct 7–9) to launch fully integrated hardware and software solutions for rail and tunnel construction workflows, enhancing interoperability between their platforms to boost workflow efficiency and accuracy.
- In September 2025, Autodesk introduced Autodesk Forma Building Design, a new cloud-based detailed building design solution within its Forma platform at Autodesk University 2025, expanding its AEC design offerings with automated modeling and building analysis capabilities.
Report Coverage
The research report offers an in-depth analysis based on Platform, Type, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will continue to expand as construction firms accelerate digital transformation and integrate mobile-first design workflows across project stages.
- Adoption of BIM-centered design ecosystems will increase, supporting greater coordination, clash detection, and lifecycle-based project planning.
- AI-driven automation and generative design capabilities will play a larger role in improving accuracy, optimizing layouts, and reducing design iteration time.
- AR/VR and mixed-reality tools will gain wider acceptance for immersive visualization, remote collaboration, and client-centric design presentations.
- Cloud-based collaboration platforms will strengthen scalability, enabling real-time data sharing and version control across distributed project teams.
- SMEs and independent contractors will adopt lightweight and subscription-based design apps at a faster pace due to affordability and ease of use.
- Integration with project management, digital twin, and IoT-enabled construction platforms will become more widespread.
- Sustainability-focused design tools will see increasing demand as developers prioritize energy efficiency and regulatory compliance.
- Regional markets in Asia-Pacific and the Middle East will witness accelerated adoption driven by large infrastructure and urban development projects.
- Vendors will focus on interoperability, cybersecurity, and open-platform ecosystems to address data security and integration challenges in enterprise environments.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Construction Design App Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Construction Design App Market projected to grow between 2024 and 2032?
Which Construction Design App Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Construction Design App Market?
Who are the leading companies in the Construction Design App Market?
Which region commanded the largest share of the Construction Design App Market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Construction Design App Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Construction Design App Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 5,659 Million → 2032: USD 10,319.51 Million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Construction Design App Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Construction Design App Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Construction Design App Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Construction Design App Market Drivers
- 3.3 Construction Design App Market Restraints & Challenges
- 3.4 Construction Design App Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Construction Design App Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Construction Design App Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Construction Design App category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Construction Design App Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Construction Design App Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Construction Design App market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Construction Design App Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Construction Design App Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Construction Design App Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Construction Design App (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Construction Design App Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Construction Design App Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Construction Design App Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Construction Design App Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Construction Design App Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Construction Design App Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Construction Design App Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Construction Design App Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Construction Design App Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
