
Market Overview
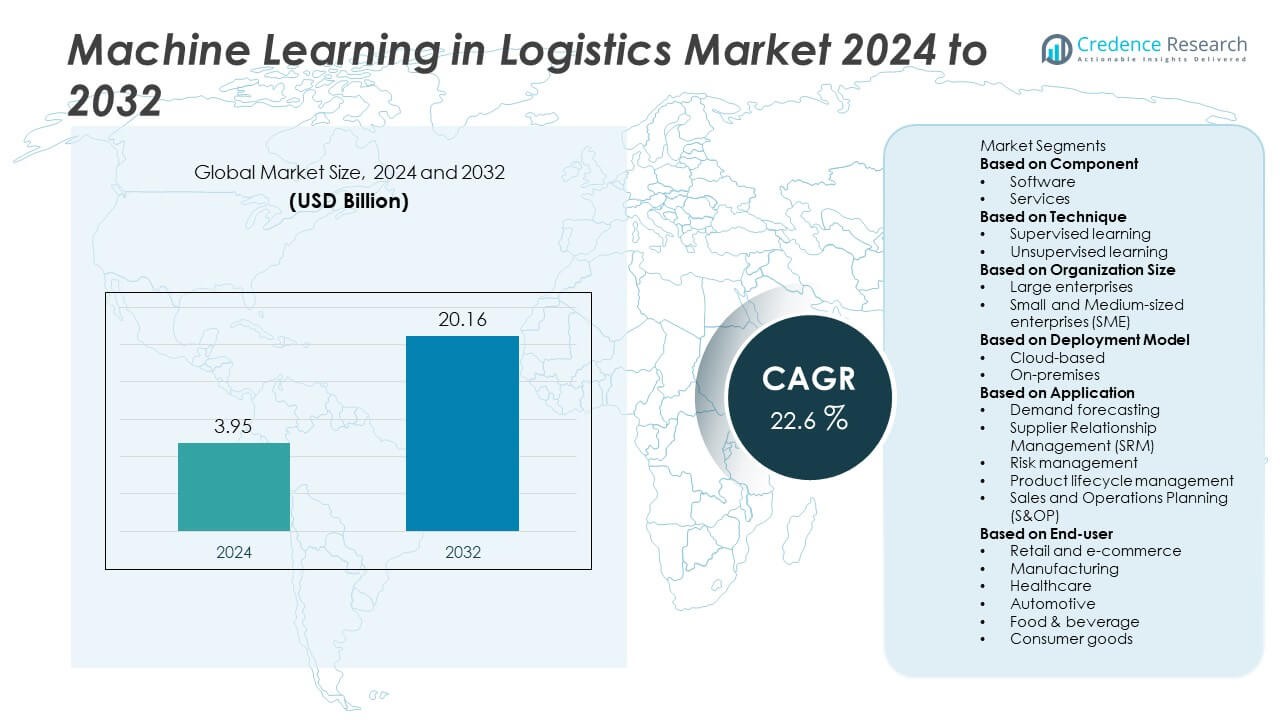
The Machine Learning in Logistics Market was valued at USD 3.95 billion in 2024 and is projected to reach USD 20.16 billion by 2032, expanding at a CAGR of 22.6% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Machine Learning in Logistics Market Size 2024 | USD 3.95 Billion |
| Machine Learning in Logistics Market, CAGR | 22.6% |
| Machine Learning in Logistics Market Size 2032 | USD 20.16 Billion |
The Machine Learning in Logistics Market grows through strong drivers such as the rising need for predictive analytics, route optimization, warehouse automation, and demand forecasting. Companies adopt advanced tools to reduce costs, improve accuracy, and enhance supply chain visibility.
The Machine Learning in Logistics Market demonstrates strong geographical growth across major regions, supported by rapid digital transformation and rising e-commerce penetration. North America leads adoption with advanced infrastructure, widespread use of predictive analytics, and early investment in automation technologies. Europe emphasizes regulatory compliance and sustainability, driving integration of AI-powered tools in logistics operations. Asia-Pacific records significant expansion through growing consumer demand, large-scale trade activities, and government-led digital initiatives, while Latin America and the Middle East & Africa gradually adopt machine learning to improve efficiency and reduce delivery bottlenecks. Key players shaping the market include Amazon Web Services, Inc. (AWS), which provides scalable cloud-based machine learning platforms; Microsoft Corporation, offering AI-driven logistics optimization tools; DHL Supply Chain, leveraging advanced analytics for global logistics operations; and Blue Yonder Group, Inc., known for its strong predictive analytics solutions in supply chain and warehouse management.
Market Insights
- The Machine Learning in Logistics Market was valued at USD 3.95 billion in 2024 and is projected to reach USD 20.16 billion by 2032, growing at a CAGR of 22.6% during the forecast period.
- Strong demand for predictive analytics, warehouse automation, and route optimization drives adoption as companies aim to improve efficiency and reduce operational costs.
- Key trends highlight integration of IoT-enabled devices, real-time visibility platforms, and AI-powered forecasting, along with the emergence of autonomous logistics solutions.
- The market features intense competition with global players such as Amazon Web Services, Microsoft, IBM, DHL Supply Chain, and Blue Yonder investing heavily in advanced AI-driven logistics platforms.
- High implementation costs, challenges in integrating new technologies with legacy systems, and workforce skill shortages restrain the pace of adoption for small and mid-sized firms.
- North America leads adoption through advanced logistics infrastructure and early investments, Europe focuses on sustainability and compliance, Asia-Pacific grows rapidly with booming e-commerce and trade, while Latin America and the Middle East & Africa show gradual but steady progress.
- The sector continues to evolve as machine learning strengthens resilience, reduces carbon footprints, and creates new opportunities for companies to align operational efficiency with global sustainability targets.
Market Drivers
Rising Demand for Predictive Analytics in Supply Chains
The Machine Learning in Logistics Market gains strong momentum from the increasing need for predictive analytics to improve supply chain visibility. Companies rely on advanced models to anticipate demand shifts, identify potential disruptions, and plan inventory with greater precision. It supports dynamic decision-making by processing large datasets from suppliers, warehouses, and transportation systems. Predictive tools reduce inefficiencies and lower costs by aligning supply with real demand. Logistics firms adopt these solutions to achieve timely deliveries and enhance customer satisfaction. The use of analytics strengthens competitiveness in highly volatile global trade environments.
- For instance, Blue Yonder reported that its Luminate platform processed forecasts, enabling global retailers and logistics providers to improve supply chain accuracy and responsiveness.
Growing Emphasis on Route Optimization and Transportation Efficiency
The Machine Learning in Logistics Market benefits from wider adoption of algorithms that optimize routes and transportation efficiency. Logistics providers face mounting pressure to reduce fuel costs and meet delivery commitments in shorter timeframes. It enables real-time adjustments to routes by analyzing traffic, weather, and operational constraints. Companies apply such solutions to minimize downtime and enhance fleet utilization across regions. Improved routing directly cuts operational expenses while ensuring faster order fulfillment. The application of machine learning in this domain reshapes logistics operations into leaner, more efficient networks.
- For instance, FedEx integrated its AI-powered Dynamic Route Optimization system across its U.S. operations in 2023, which optimized more than 200,000 daily routes and reduced average delivery miles by 12 million annually.
Expanding Role of Warehouse Automation and Inventory Control
The Machine Learning in Logistics Market expands rapidly through automation of warehouses and tighter inventory management practices. Smart algorithms track inventory flow and predict stock requirements across multiple facilities. It reduces the risk of overstocking or stockouts by balancing supply with demand forecasts. Warehouse automation powered by machine learning accelerates picking, packing, and sorting, reducing human error. Companies invest in these systems to improve throughput while maintaining accuracy in high-volume operations. Intelligent automation establishes resilient, cost-efficient warehouse ecosystems.
Increasing Integration of IoT and Real-Time Data for Decision-Making
Machine Learning in Logistics Market advances through integration with IoT devices that generate valuable real-time data. Connected sensors track shipments, monitor conditions, and transmit data to machine learning systems for continuous evaluation. It enhances visibility across the logistics chain, enabling managers to respond quickly to disruptions. Data-driven insights improve asset utilization and reduce risks tied to theft or spoilage. The ability to process vast streams of information empowers companies to move toward fully adaptive supply chains. Integration with IoT strengthens the position of machine learning as a core enabler of intelligent logistics.
Market Trends
Adoption of AI-Powered Demand Forecasting Solutions
The Machine Learning in Logistics Market shows strong momentum through the use of AI-powered demand forecasting solutions. Companies seek advanced tools to anticipate consumer demand patterns with greater precision. It allows firms to plan procurement, manage stock levels, and adjust delivery schedules based on real-time insights. Predictive demand planning reduces excess inventory while preventing shortages in high-demand cycles. Retailers and logistics providers deploy these solutions to align supply chain performance with evolving market requirements. Demand forecasting supported by machine learning transforms logistics into a more responsive and customer-focused industry.
- For instance, Blue Yonder highlighted that its Demand Planning solution enabled a 12-point improvement in forecast accuracy for its clients, alongside a 75-point lift in planner productivity and a 50-point reduction in planning costs
Shift Toward Autonomous Logistics and Smart Fleet Management
The Machine Learning in Logistics Market progresses with the integration of autonomous systems and intelligent fleet management platforms. Companies deploy self-learning algorithms to optimize fleet routes, monitor vehicle performance, and improve driver productivity. It strengthens operational efficiency by analyzing road conditions, traffic, and energy use. Autonomous delivery vehicles and drones represent a growing trend in urban logistics. Companies that invest in these technologies achieve cost savings while reducing delivery times. The trend toward autonomy underscores the role of machine learning in shaping the future of global logistics.
- For instance, DHL partnered with Volvo Autonomous Solutions in 2024 to operate driverless freight trucks between Dallas and Houston, completing more than 1,500 autonomous trips covering over 1.2 million miles with zero safety incidents during the pilot phase.
Expansion of Real-Time Tracking and Visibility Platforms
The Machine Learning in Logistics Market advances with broader adoption of real-time tracking and shipment visibility platforms. IoT-enabled devices feed continuous data into machine learning models to monitor shipment locations, condition, and safety. It empowers logistics managers to detect delays, reroute deliveries, and respond proactively to disruptions. Enhanced visibility supports customer satisfaction by providing accurate updates on delivery status. Companies invest in digital platforms that centralize tracking data for global operations. Real-time transparency supported by machine learning becomes an essential component of modern logistics networks.
Integration of Sustainable Practices Through Data Optimization
The Machine Learning in Logistics Market evolves by supporting sustainability goals through smarter resource utilization. Machine learning systems analyze fuel use, packaging materials, and energy consumption to identify areas for efficiency improvement. It enables companies to reduce carbon footprints while maintaining operational productivity. Optimized routing and warehouse energy management drive measurable reductions in emissions. Firms integrate sustainability metrics into decision-making frameworks powered by machine learning. The trend highlights the dual role of technology in advancing both profitability and environmental responsibility in logistics.
Market Challenges Analysis
High Implementation Costs and Complexity of Integration
The Machine Learning in Logistics Market faces challenges linked to high implementation costs and the complexity of integrating advanced systems into existing infrastructure. Many logistics providers operate on thin margins, making large-scale investments in data platforms and AI-driven tools difficult. It often requires significant upgrades to IT infrastructure, including cloud systems, IoT devices, and secure data storage networks. Smaller companies struggle to justify these expenses while competing with larger players that have more resources. Integration with legacy systems further delays deployment and increases technical hurdles. The financial and operational demands create barriers that slow down wider adoption across the sector.
Data Quality Issues and Skills Shortages in Workforce
The Machine Learning in Logistics Market also encounters challenges related to inconsistent data quality and a shortage of skilled professionals. Machine learning systems rely on accurate, structured, and comprehensive data, yet many logistics networks still deal with fragmented or incomplete datasets. It reduces the effectiveness of predictive models and limits the accuracy of real-time decision-making. Companies also face difficulties in hiring talent with expertise in AI, data science, and logistics operations. The gap between technical capabilities and workforce readiness increases operational risks and raises training costs. Persistent issues around data quality and skill shortages remain critical obstacles to scaling machine learning in logistics operations.
Market Opportunities
Rising Potential of E-Commerce and Last-Mile Delivery Optimization
The Machine Learning in Logistics Market holds significant opportunities through the rapid growth of e-commerce and the increasing focus on last-mile delivery. Companies leverage intelligent algorithms to optimize delivery routes, reduce fuel costs, and ensure faster service in congested urban areas. It enhances delivery accuracy by analyzing customer preferences, traffic conditions, and package density. Retailers and logistics providers benefit from predictive tools that improve scheduling and reduce delays during peak demand seasons. The expansion of online retail across both developed and emerging regions amplifies the scope for machine learning adoption. Last-mile efficiency becomes a major differentiator in competitive logistics markets.
Growing Scope of Sustainable Logistics and Green Supply Chains
The Machine Learning in Logistics Market also creates opportunities for building sustainable and environmentally responsible supply chains. Companies integrate machine learning systems to reduce emissions through optimized fuel usage, energy-efficient warehouse operations, and waste reduction strategies. It supports compliance with evolving environmental regulations while improving brand reputation among eco-conscious customers. Predictive models identify areas for carbon footprint reduction across logistics operations, creating both cost and sustainability benefits. Businesses that adopt these solutions can strengthen their market position while aligning with global sustainability targets. The growing emphasis on green logistics drives innovation and long-term opportunities in the sector.
Market Segmentation Analysis:
By Component
The Machine Learning in Logistics Market is segmented by component into software and services. Software dominates the segment as companies deploy machine learning platforms for predictive analytics, warehouse automation, and route optimization. It provides advanced capabilities for real-time decision-making, enabling logistics providers to handle increasing operational complexity. Services hold strong growth potential as organizations seek consulting, integration, and managed services to ensure successful deployment of AI-driven solutions. It addresses the need for technical expertise and ongoing support in maintaining large-scale logistics networks. The combination of software innovation and service support creates a balanced growth path for this segment.
- For instance, Microsoft reported that its Azure AI services processed over 2 trillion predictions per month in 2023, enabling logistics and retail clients to optimize operations at scale through cloud-based software and integrated support services.
By Technique
The Machine Learning in Logistics Market is divided by technique into supervised learning, unsupervised learning, reinforcement learning, and deep learning. Supervised learning accounts for major adoption as companies use it to predict demand, improve delivery times, and reduce operational inefficiencies. Unsupervised learning plays a growing role in identifying hidden patterns in large logistics datasets, supporting applications such as fraud detection and route clustering. Reinforcement learning emerges as a powerful technique for autonomous systems and adaptive route planning. It enhances decision-making by allowing systems to learn from outcomes and continuously refine performance. Deep learning expands opportunities in image recognition for inventory management and automated quality checks.
- For instance, Google DeepMind applied reinforcement learning to logistics simulations in 2023, running over 70 million training steps per day to optimize routing models that improved delivery accuracy across large-scale fleet networks.
By Organization Size
The Machine Learning in Logistics Market is further segmented by organization size into large enterprises and small & medium-sized enterprises (SMEs). Large enterprises lead adoption due to their ability to invest in advanced infrastructure and leverage extensive datasets. It supports global operations through predictive insights, automation, and integrated data platforms. SMEs show rising adoption rates as cloud-based machine learning solutions lower entry barriers and reduce upfront costs. Service providers design scalable solutions that allow smaller firms to compete with larger logistics players. Both categories benefit from machine learning, though investment levels and implementation scales vary significantly.
Segments:
Based on Component
- Software
- Services
Based on Technique
- Supervised learning
- Unsupervised learning
Based on Organization Size
- Large enterprises
- Small and Medium-sized enterprises (SME)
Based on Deployment Model
- Cloud-based
- On-premises
Based on Application
- Demand forecasting
- Supplier Relationship Management (SRM)
- Risk management
- Product lifecycle management
- Sales and Operations Planning (S&OP)
Based on End-user
- Retail and e-commerce
- Manufacturing
- Healthcare
- Automotive
- Food & beverage
- Consumer goods
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis
North America
North America holds the largest share of the Machine Learning in Logistics Market, accounting for 34.2% in 2024. The region leads adoption due to the presence of advanced logistics infrastructure, strong investments in artificial intelligence, and the rapid expansion of e-commerce platforms. It benefits from early integration of machine learning solutions across transportation, warehousing, and supply chain management. Companies in the United States and Canada deploy predictive analytics to improve demand forecasting, fleet optimization, and last-mile delivery. The high concentration of global technology providers further strengthens innovation and accelerates deployment across logistics networks. Large logistics enterprises in the region prioritize efficiency, sustainability, and real-time visibility, which creates steady opportunities for machine learning solutions.
Europe
Europe contributes to 28.6% of the Machine Learning in Logistics Market in 2024, supported by strong regulatory frameworks and a growing focus on digital transformation in supply chains. Companies in Germany, the United Kingdom, and France lead the adoption of intelligent logistics platforms to comply with sustainability targets and improve operational transparency. It gains momentum from the integration of IoT and machine learning systems that provide real-time monitoring of goods in transit. The region’s advanced automotive and manufacturing industries drive demand for optimized supply chain processes supported by AI-driven tools. SMEs and logistics startups in Europe increasingly adopt cloud-based machine learning applications to lower costs and enhance efficiency. A strong emphasis on data privacy and compliance influences the deployment of AI-driven logistics solutions in the region.
Asia-Pacific
Asia-Pacific represents 23.7% of the Machine Learning in Logistics Market in 2024, with significant growth potential over the forecast period. The region experiences rapid expansion in e-commerce, driven by large consumer bases in China, India, and Southeast Asia. It supports adoption through the need for efficient last-mile delivery solutions and scalable logistics networks. Companies across the region invest heavily in automation, warehouse robotics, and demand forecasting tools powered by machine learning. Governments in key economies encourage digital transformation initiatives that create favorable conditions for advanced logistics technologies. Major logistics providers in Asia-Pacific integrate machine learning to handle cross-border operations and rising trade volumes. The region’s growth is reinforced by strong investments in infrastructure and rising awareness of cost optimization benefits.
Latin America
Latin America holds 7.1% of the Machine Learning in Logistics Market in 2024. Adoption is slower compared to other regions due to infrastructure gaps and limited financial resources among smaller logistics firms. It gains traction in markets such as Brazil and Mexico, where e-commerce expansion accelerates the demand for efficient supply chain solutions. Companies adopt predictive analytics and real-time tracking to improve reliability and reduce delivery delays across diverse geographies. Cloud-based machine learning tools provide affordable entry points for regional logistics providers. The growing integration of automation in ports and warehouses supports long-term market development. Investments in digital transformation projects by regional governments strengthen future adoption across the sector.
Middle East & Africa
The Middle East & Africa accounts for 6.4% of the Machine Learning in Logistics Market in 2024. The region shows gradual adoption, with Gulf Cooperation Council (GCC) countries leading efforts to modernize logistics infrastructure. It benefits from significant investments in smart city projects and free trade zones that require advanced logistics and supply chain solutions. Machine learning supports efficient port management, predictive maintenance, and real-time shipment tracking across the region. Africa shows early-stage adoption, driven by growing e-commerce penetration and infrastructure development projects. Companies in logistics hubs such as the UAE and Saudi Arabia integrate AI-driven platforms to strengthen their roles as global trade centers. The region’s focus on digital transformation in logistics ensures steady growth opportunities despite current challenges.
Key Player Analysis
- Manhattan Associates, Inc.
- FedEx Corporation
- Microsoft Corporation
- Blue Yonder Group, Inc.
- H. Robinson Worldwide, Inc.
- International Business Machines Corporation (IBM)
- Google LLC
- Coupa Software Inc.
- DHL Supply Chain
- Amazon Web Services, Inc. (AWS)
Competitive Analysis
The competitive landscape of the Machine Learning in Logistics Market is defined by the presence of global technology providers and logistics leaders that actively invest in advanced AI-driven platforms to enhance efficiency, scalability, and customer value. Key players include Amazon Web Services, Inc. (AWS), Microsoft Corporation, Google LLC, International Business Machines Corporation (IBM), Blue Yonder Group, Inc., Manhattan Associates, Inc., Coupa Software Inc., C.H. Robinson Worldwide, Inc., DHL Supply Chain, and FedEx Corporation. These companies leverage machine learning to deliver predictive analytics, real-time tracking, route optimization, and intelligent warehouse management solutions. Cloud service providers such as AWS, Microsoft, and Google dominate the infrastructure segment by offering scalable AI and data platforms, while IBM and Blue Yonder focus on specialized supply chain analytics and predictive modeling. Logistics giants like DHL and FedEx integrate machine learning to streamline global operations, reduce delivery delays, and enhance last-mile performance. Technology-driven firms such as Manhattan Associates, Coupa, and C.H. Robinson strengthen competitiveness with end-to-end optimization tools that improve transparency and responsiveness in logistics networks. The market remains highly dynamic, with continuous innovation, strategic partnerships, and rising demand for sustainable, data-driven supply chains shaping long-term growth.
Recent Developments
- In August 2025, FedEx inaugurated the FedEx SMART Centre at IIT Madras, advancing logistics innovation through applied research and collaboration.
- In June 2025, Microsoft introduced AI agents across their developer and data stack, embedding them into tools like GitHub, Teams, Cosmos DB, and Windows.
- In April 2025, C.H. Robinson revealed that their generative AI agents had executed over 3 million shipping tasks, dramatically reducing customer time‑to‑market.
- In January 2025, Blue Yonder released major AI and machine learning platform updates to enhance supply chain efficiency.
Market Concentration & Characteristics
The Machine Learning in Logistics Market reflects a moderately concentrated structure with dominance by global technology leaders and large logistics enterprises that invest heavily in advanced AI-driven platforms. It features strong competition among established players such as AWS, Microsoft, Google, IBM, DHL, FedEx, and Blue Yonder, which focus on predictive analytics, real-time tracking, and intelligent automation. Smaller firms and startups enter the market by offering niche solutions such as warehouse robotics, demand forecasting, and route optimization, creating innovation-driven fragmentation within certain segments. It is characterized by rapid adoption of cloud-based platforms, increasing reliance on IoT integration, and growing demand for scalable solutions that serve both large enterprises and SMEs. The market demonstrates high entry barriers due to infrastructure costs and technical expertise requirements, yet it continues to expand as digital transformation reshapes logistics. It evolves with emphasis on efficiency, transparency, and sustainability, positioning machine learning as a core enabler of next-generation supply chain operations.
Report Coverage
The research report offers an in-depth analysis based on Component, Technique, Organization Size, Deployment Model, Application, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Machine Learning in Logistics Market will expand rapidly with rising adoption of AI-driven predictive analytics for smarter supply chains.
- It will strengthen last-mile delivery optimization through intelligent routing and autonomous vehicle integration.
- The market will gain momentum from cloud-based platforms that offer scalability and flexibility for logistics providers of all sizes.
- It will advance warehouse automation by integrating robotics and vision-based deep learning for faster and more accurate operations.
- The sector will adopt real-time tracking and visibility solutions powered by IoT sensors and machine learning algorithms.
- It will focus on sustainability by using AI models to reduce fuel consumption, optimize routes, and lower emissions.
- The market will attract increasing investments in agentic AI systems that improve adaptive decision-making across logistics networks.
- It will encourage collaboration between technology providers and logistics companies to accelerate innovation and deployment.
- The sector will face rising demand for skilled talent in data science, AI, and logistics analytics to support large-scale adoption.
- It will continue evolving toward intelligent, resilient, and customer-centric logistics ecosystems driven by machine learning.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Demand for Predictive Analytics in Supply Chains
Companies are increasingly leveraging machine learning for predictive analytics to improve supply chain visibility, anticipate demand shifts, and proactively manage inventory, which reduces inefficiencies and enhances competitiveness in volatile trade environments.
Emphasis on Route Optimization and Transportation Efficiency
Machine learning algorithms enable real-time route optimization by analyzing traffic, weather, and operational constraints, helping logistics providers reduce fuel costs, minimize delivery times, and improve fleet utilization.
Expansion of Warehouse Automation and Inventory Control
Smart machine learning systems automate warehouse operations, optimize inventory levels, and accelerate picking and packing processes, leading to higher throughput, reduced human error, and cost-efficient logistics ecosystems.
Integration of IoT and Real-Time Data for Decision-Making
The adoption of IoT devices in logistics generates real-time data streams that feed into machine learning models, enhancing shipment tracking, asset utilization, and rapid response to disruptions, thereby enabling adaptive and resilient supply chains.
Growth of E-Commerce and Last-Mile Delivery Optimization
The surge in e-commerce is driving logistics companies to adopt machine learning for optimizing last-mile delivery, improving scheduling, reducing delays, and meeting rising consumer expectations for fast and accurate deliveries.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Machine Learning in Logistics, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Machine Learning in Logistics market projected to grow between 2025 and 2032?
Which Machine Learning in Logistics market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Machine Learning in Logistics market?
Who are the leading companies in the Machine Learning in Logistics market?
Which region commanded the largest share of the Machine Learning in Logistics market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Component
- 1.2.1 Software
- 1.2.2 Services
- 1.3 By Technique
- 1.3.1 Supervised learning
- 1.3.2 Unsupervised learning
- 1.3.3 Reinforcement learning
- 1.3.4 Deep learning
- 1.4 By Application
- 1.4.1 Demand forecasting
- 1.4.2 Supplier Relationship Management (SRM)
- 1.4.3 Risk management
- 1.4.4 Product lifecycle management
- 1.4.5 Sales and Operations Planning (S&OP)
- 1.5 By Organization Size
- 1.5.1 Large enterprises
- 1.5.2 Small and Medium-sized enterprises (SME)
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 3.95 billion → 2032: USD 20.16 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Machine Learning in Logistics Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Machine Learning in Logistics Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Machine Learning in Logistics Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Machine Learning in Logistics Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Machine Learning in Logistics Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Machine Learning in Logistics Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Machine Learning in Logistics Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Machine Learning in Logistics Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 3.95 billion → 2032: USD 20.16 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Machine Learning in Logistics Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Component - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Software
- 12.3.7.2 Services
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Technique - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Supervised learning
- 12.4.7.2 Unsupervised learning
- 12.4.7.3 Reinforcement learning
- 12.4.7.4 Deep learning
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Demand forecasting
- 12.5.7.2 Supplier Relationship Management (SRM)
- 12.5.7.3 Risk management
- 12.5.7.4 Product lifecycle management
- 12.5.7.5 Sales and Operations Planning (S&OP)
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Organization Size - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Large enterprises
- 12.6.7.2 Small and Medium-sized enterprises (SME)
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Machine Learning in Logistics End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Machine Learning in Logistics Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Machine Learning in Logistics Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Machine Learning in Logistics Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Amazon Web Services, Inc. (AWS)
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Microsoft Corporation
- 18.4 Google LLC
- 18.5 International Business Machines Corporation (IBM)
- 18.6 Blue Yonder Group, Inc.
- 18.7 DHL Supply Chain
- 18.8 FedEx Corporation
- 18.9 Manhattan Associates, Inc.
- 18.10 Coupa Software Inc.
- 18.11 C.H. Robinson Worldwide, Inc.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

