
Market Overview
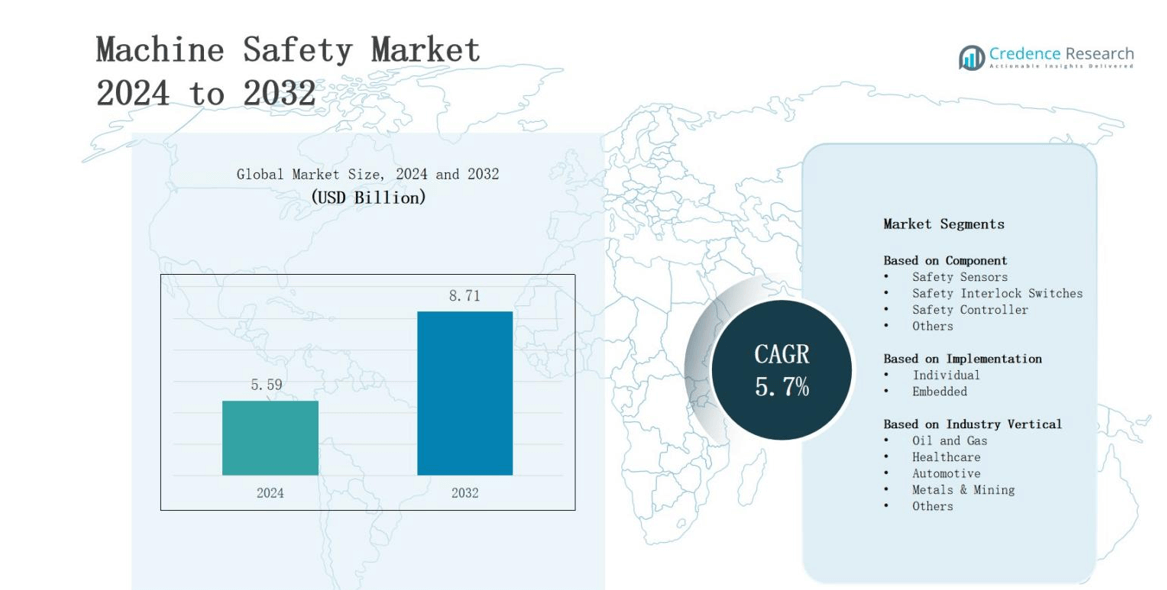
The global machine safety market is projected to grow from USD 5.59 billion in 2024 to USD 8.71 billion by 2032, registering a CAGR of 5.7%.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Machine Safety Market Size 2024 | USD 5.59 billion |
| Machine Safety Market, CAGR | 5.7% |
| Machine Safety Market Size 2032 | USD 8.71 billion |
The machine safety market is driven by rising adoption of automation across industries, stringent workplace safety regulations, and increasing demand for advanced safety components to reduce accidents and downtime. Growing awareness of employee safety, coupled with the integration of IoT and Industry 4.0 technologies, further accelerates adoption of safety sensors, controllers, and interlock devices. Manufacturers are investing in innovative solutions to ensure compliance, enhance productivity, and minimize risks. Emerging trends include the shift toward collaborative robotics, predictive maintenance, and AI-enabled safety systems, which collectively shape a more connected and intelligent industrial safety ecosystem.
The machine safety market shows significant growth across North America, Europe, Asia-Pacific, and the Rest of the World, driven by industrial automation, regulatory compliance, and workforce protection initiatives. North America and Europe focus on advanced safety systems and strict standards, while Asia-Pacific leads in adoption due to rapid industrialization, and the Rest of the World presents emerging opportunities. Key players including Siemens AG, Emerson Electric Co., Mitsubishi Electric Corporation, SICK AG, Schneider Electric SE, OMRON Corporation, B&R Automation, Honeywell International, ABB Ltd., Rockwell Automation, and KEYENCE CORPORATION dominate the market with innovative solutions and global reach.
Market Insights
- The machine safety market is projected to grow from USD 5.59 billion in 2024 to USD 8.71 billion by 2032, registering a CAGR of 5.7%, driven by automation adoption and regulatory compliance.
- Safety sensors dominate the component segment with 38% share, supported by real-time monitoring demand, followed by interlock switches at 27%, controllers at 22%, and other components at 13%, enhancing workplace protection.
- Embedded implementation leads with 61% share due to seamless integration with automated machinery, while individual implementation contributes 39%, appealing to SMEs for cost-effective and flexible adoption across industries.
- Automotive holds the largest industry vertical share at 31%, followed by oil and gas at 21%, metals and mining at 18%, healthcare at 15%, and other sectors at 15%, reflecting diversified industrial demand.
- Regionally, Asia-Pacific leads with 31% share, followed by North America at 29%, Europe at 26%, and the Rest of the World at 14%, driven by industrialization, workforce safety initiatives, and adoption of smart technologies.
Market Drivers
Rising Adoption of Industrial Automation
The machine safety market experiences strong growth due to widespread adoption of automation in manufacturing and processing industries. Companies aim to increase operational efficiency while ensuring worker safety, which creates demand for safety controllers, sensors, and interlock devices. Automation requires advanced safety protocols to minimize risks associated with high-speed machinery. Governments continue enforcing strict regulations that compel manufacturers to implement certified safety solutions. Automation advances transform operational environments and support rapid safety technology integration.
- For instance, Rockwell Automation’s GuardLink safety system has been deployed in food and beverage plants, using smart safety devices connected over a single cable to minimize wiring and improve diagnostics.
Stringent Workplace Safety Regulations
Governments and industry bodies enforce strict workplace safety standards that drive consistent demand for certified safety systems. Regulations such as ISO and OSHA require industries to comply with robust safety protocols to protect workers. The machine safety market benefits from such frameworks, as organizations must prioritize safety investments. It encourages innovation in protective equipment and monitoring devices. Strong compliance culture ensures workplace incidents remain minimal, while supporting long-term productivity goals. Regulatory enforcement sustains market momentum globally.
- For instance, OSHA’s lockout/tagout standard (29 CFR 1910.147) has driven companies like General Motors and Ford to deploy advanced machine guarding and energy-isolation systems to protect maintenance workers
Growing Focus on Workforce Protection
Worker safety concerns remain a central driver of market expansion, as industrial accidents impose high human and financial costs. The machine safety market addresses these concerns through products that protect workers during machine operation. Employers adopt preventive safety technologies to limit liability and strengthen employee confidence. It ensures improved morale, reduced downtime, and higher efficiency. Expanding industrial sectors in emerging economies amplify the focus on safety, creating broad opportunities for safety solution providers worldwide.
Technological Advancements in Safety Solutions
The market grows steadily with advancements in robotics, IoT, and artificial intelligence that enhance predictive capabilities of safety systems. It enables real-time monitoring and advanced diagnostics, ensuring machines function safely under varying conditions. The machine safety market benefits from integration of smart sensors and cloud-based analytics platforms. Manufacturers introduce innovative solutions that combine automation with enhanced protection. These developments create safer workplaces, optimize productivity, and ensure compliance with international standards. Technology continues shaping next-generation safety frameworks.
Market Trends
Integration of IoT and Smart Safety Systems
The machine safety market is witnessing a rapid shift toward IoT-enabled and connected safety systems that enhance real-time monitoring and predictive analytics. Companies deploy smart sensors and cloud-based platforms to detect anomalies and prevent operational risks. It allows industries to identify issues early and reduce downtime. IoT integration improves visibility, enabling remote supervision of safety protocols. This trend supports compliance, operational efficiency, and proactive safety management across various industrial environments.
- For instance, Axzon provides IoT sensors that deliver real-time temperature and moisture data during automotive manufacturing, helping prevent equipment overheating and failures.
Adoption of Collaborative Robotics and Human-Machine Interaction
The increasing use of collaborative robots in modern factories significantly influences safety practices. The machine safety market adapts by providing solutions that protect workers while allowing closer human-machine collaboration. It focuses on advanced sensors, interlock systems, and adaptive safety controls that maintain safe environments without slowing productivity. Organizations rely on flexible solutions to balance efficiency and protection. This trend reflects the growing acceptance of robotics in manufacturing and process industries worldwide.
- For instance, Omron employs safety area scanners and mats in its collaborative robot setups to create open-area safety guarding, enabling robots to work alongside humans without physical barriers while maintaining safety through advanced sensing technologies.
Shift Toward Predictive Maintenance and Advanced Diagnostics
Industrial operators are prioritizing predictive maintenance to ensure uninterrupted operations and safe machine performance. The machine safety market benefits from diagnostic tools and predictive algorithms that detect potential hazards before they escalate. It reduces unexpected failures and costly downtime while supporting compliance with safety standards. Companies integrate AI-based systems to enhance precision and efficiency in maintenance activities. The trend highlights a growing preference for proactive safety management over traditional reactive approaches.
Emphasis on AI and Data-Driven Safety Solutions
Artificial intelligence plays a crucial role in the development of intelligent machine safety frameworks. The machine safety market leverages AI for risk assessment, automated decision-making, and real-time data interpretation. It helps companies create safer, more adaptive production environments. Data-driven solutions provide actionable insights that strengthen workplace safety strategies. AI integration promotes continuous improvement and supports innovation. This trend defines the evolution of safety solutions toward more dynamic and intelligent ecosystems across industries.
Market Challenges Analysis
High Implementation Costs and Complex Integration
The machine safety market faces challenges related to high initial costs and complex integration processes. Companies often hesitate to invest in advanced safety systems due to budget limitations, particularly in small and medium-sized enterprises. It requires specialized expertise to install and maintain safety devices, which further raises costs. Integration with existing legacy machinery can be difficult, slowing adoption in traditional industries. These financial and technical barriers limit broader market penetration despite rising safety awareness.
Lack of Skilleid Workforce and Awareness Gaps
A shortage of skilled professionals who can manage and operate advanced safety systems continues to challenge market expansion. The machine safety market depends on trained engineers to ensure proper installation, compliance, and maintenance of safety solutions. It also faces awareness gaps among organizations in emerging economies, where safety standards are not strictly enforced. Limited knowledge about the long-term benefits of safety investments often delays adoption. This situation restricts consistent global growth despite technological advancements.
Market Opportunities
Expansion in Emerging Economies and Industrial Growth
The machine safety market holds significant opportunities in emerging economies where industrialization is accelerating rapidly. Manufacturing hubs in Asia-Pacific, Latin America, and Africa are expanding production capacity, which increases demand for advanced safety systems. It allows companies to improve compliance, reduce accidents, and align with global safety standards. Rising foreign investments and supportive government initiatives further encourage the adoption of modern safety solutions. The expansion of industrial sectors creates strong opportunities for safety technology providers worldwide.
Advancements in Digital Technologies and Smart Manufacturing
Growing adoption of digital technologies creates new opportunities for innovative safety solutions. The machine safety market benefits from developments in artificial intelligence, cloud platforms, and advanced robotics that enhance monitoring and predictive maintenance. It enables industries to integrate safety within smart manufacturing frameworks for higher efficiency. Demand for data-driven, adaptive safety systems is rising across sectors such as automotive, pharmaceuticals, and food processing. This digital transformation strengthens the long-term growth outlook for advanced safety solutions.
Market Segmentation Analysis:
By Component
In the machine safety market, safety sensors dominate the component segment with a share of around 38%, supported by rising demand for real-time monitoring and accident prevention across manufacturing facilities. These sensors enhance detection accuracy and support compliance with global safety standards. Safety interlock switches account for nearly 27%, as industries adopt them to ensure safe access during machine operation. Safety controllers represent about 22%, driven by automation growth, while other components hold the remaining 13%.
- For instance, Rockwell Automation’s Guardmaster interlock switches are widely deployed in food and beverage plants to prevent operators from accessing hazardous zones until equipment has stopped.
By Implementation
Embedded implementation leads this segment with a share of 61%, driven by its seamless integration with automated machinery and ability to improve reliability. It enables manufacturers to reduce system complexity while enhancing safety functionality. Individual implementation contributes nearly 39%, appealing to small and medium enterprises seeking flexibility and cost-effective adoption. The machine safety market benefits from the preference for embedded solutions in modern industrial setups where operational efficiency is critical.
- For instance, Siemens integrates embedded safety controllers in its SIMATIC S7-1500 series, allowing built-in fail-safe automation that reduces wiring needs and streamlines machine safety compliance.
By Industry Vertical
The automotive sector holds the largest share at about 31%, fueled by automation in assembly lines and strict safety compliance requirements. Oil and gas follows with around 21%, where safety systems mitigate high-risk operational environments. Metals and mining contributes nearly 18%, supported by rising adoption of advanced machinery protection systems. Healthcare accounts for close to 15%, focusing on precision safety in medical equipment. Other industries collectively represent about 15%, reflecting diversified demand across sectors.
Segments:
Based on Component
- Safety Sensors
- Safety Interlock Switches
- Safety Controller
- Others
Based on Implementation
- Individual
- Embedded
Based on Industry Vertical
- Oil and Gas
- Healthcare
- Automotive
- Metals & Mining
- Others
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America holds a 29% share of the machine safety market, driven by advanced industrial automation and stringent regulatory standards. It benefits from high adoption of IoT-enabled safety systems and smart manufacturing solutions. Leading industries, including automotive, aerospace, and food processing, emphasize compliance and workforce protection. It supports development of innovative safety devices and advanced sensors. Strong government policies and investment in research and development sustain market growth. Companies continue upgrading legacy systems to meet modern safety requirements, boosting overall demand.
Europe
Europe captures 26% of the market, fueled by strict workplace safety regulations and widespread industrial automation. It encourages adoption of advanced safety controllers, interlock switches, and sensors. It focuses on reducing operational hazards and protecting employees across automotive, metals, and pharmaceutical sectors. Emerging trends include collaborative robotics and predictive maintenance integration in production facilities. Investment in AI-driven and connected safety solutions enhances compliance. Regional manufacturers prioritize innovation to maintain competitive advantage and meet international standards.
Asia-Pacific
Asia-Pacific holds the largest share at 31%, led by rapid industrialization and expansion of manufacturing hubs in China, India, and Southeast Asia. It experiences rising adoption of automated machinery, creating strong demand for safety sensors and controllers. Governments enforce safety regulations and promote industrial growth, supporting the machine safety market. It benefits from increasing foreign investment in manufacturing infrastructure. Focus on workforce protection and compliance drives the deployment of advanced solutions. Growing automotive, electronics, and food processing sectors accelerate market penetration.
Rest of the World
The Rest of the World accounts for 14% of the market, with emerging economies investing in industrial safety solutions to modernize production environments. It includes regions in Latin America, the Middle East, and Africa where infrastructure development and industrial expansion create demand for safety devices. The machine safety market benefits from government incentives and international safety standards adoption. It faces challenges due to limited skilled workforce and awareness gaps. Growing industrial sectors present opportunities for technology adoption and enhanced workplace protection.
Key Player Analysis
- ABB Ltd.
- Honeywell International, Inc.
- OMRON Corporation
- Siemens AG
- Emerson Electric Co.
- Rockwell Automation
- KEYENCE CORPORATION
- Mitsubishi Electric Corporation
- Schneider Electric SE
- SICK AG
- B&R Automation
Competitive Analysis
The machine safety market remains highly competitive, with leading players focusing on innovation, strategic partnerships, and expansion to maintain market leadership. Companies such as Siemens AG, Emerson Electric Co., Mitsubishi Electric Corporation, SICK AG, Schneider Electric SE, OMRON Corporation, B&R Automation, Honeywell International, ABB Ltd., Rockwell Automation, and KEYENCE CORPORATION continually develop advanced safety solutions, including sensors, controllers, and interlock devices. It emphasizes integration with automation systems, IoT platforms, and predictive maintenance tools to meet evolving industrial requirements. Market players invest in research and development to enhance product reliability, compliance with global safety standards, and operational efficiency. Companies compete on technology, product quality, and geographic reach, targeting sectors like automotive, metals and mining, oil and gas, and healthcare. It also explores emerging markets to capture growth opportunities in industrializing regions. Continuous innovation, coupled with strong distribution networks, positions these key players to sustain competitiveness while addressing increasing demand for safer, more efficient industrial operations worldwide.
Recent Developments
- In January 2025, Mitsubishi Electric Corporation launched MELSEC iQR safety local IO modules RX40NC6S-TS and RY48PT20S-TS. The modules are meant to supplement the lineup, improve efficiency, and lower safety costs in industrial automation.
- In December 2023, Balluff announced the CIP Safety I/O module for making safety-rated I/O devices more integrated. The module has the ability to support configurations with 12 single-channel safe inputs, 6 dual-channel safe inputs, and either 4 single-channel or 2 dual-channel safe outputs, and it is IP67 rated.
- In 2025, Honeywell acquired the Li-ion Tamer business from Nexceris, enhancing off-gas detection solutions for lithium-ion batteries.
- In March 2025, Siemens acquired Altair Engineering Inc., a provider of industrial simulation and AI software, to strengthen its AI-powered industrial software portfolio.
Market Concentration & Characteristics
The machine safety market exhibits a moderately consolidated structure, dominated by leading global players such as Siemens AG, Emerson Electric Co., Mitsubishi Electric Corporation, SICK AG, Schneider Electric SE, OMRON Corporation, B&R Automation, Honeywell International, ABB Ltd., Rockwell Automation, and KEYENCE CORPORATION. It demonstrates high technological intensity, with companies investing heavily in research and development to introduce innovative safety sensors, controllers, and interlock devices. Market competition focuses on product quality, compliance with international safety standards, and integration with automation and IoT platforms. It serves diverse industries including automotive, oil and gas, metals and mining, and healthcare, with varying adoption levels across regions. Emerging economies present growth opportunities, while advanced regions emphasize upgrades of legacy systems. The market’s characteristics reflect strong regulatory influence, technological evolution, and the need for reliable, efficient, and adaptive safety solutions, encouraging continuous innovation and strategic partnerships among key players.
Report Coverage
The research report offers an in-depth analysis based on Component, Implementation, Industry Verticals and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Automation adoption across industries will continue to drive demand for advanced safety solutions.
- IoT integration will enhance real-time monitoring and predictive maintenance capabilities.
- Collaborative robotics will increase the need for adaptive safety systems in human-machine environments.
- AI-enabled safety devices will improve operational efficiency and risk management.
- Emerging economies will present significant growth opportunities for machine safety solutions
- Upgrades of legacy machinery will stimulate demand for modern safety components.
- Compliance with global safety regulations will remain a key priority for manufacturers.
- Industry-specific customization of safety devices will gain importance.
- Technological innovation will focus on smarter, connected, and scalable safety systems.
- Workforce protection and accident prevention will remain central drivers of market adoption.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Adoption of Industrial Automation
Manufacturers are increasingly automating production lines to boost efficiency and reduce human error, which necessitates advanced machine safety systems to protect workers and ensure compliance with safety standards.
Stringent Workplace Safety Regulations
Global and regional regulations such as ISO and OSHA require industries to implement certified safety protocols, driving consistent investment in machine safety solutions to avoid penalties and ensure employee protection.
Technological Advancements in Safety Solutions
Integration of IoT, AI, and smart sensors enables real-time monitoring, predictive maintenance, and advanced diagnostics, making safety systems more effective and attractive for modern industrial environments.
Growing Focus on Workforce Protection
Rising awareness of the human and financial costs of workplace accidents is prompting companies to adopt preventive safety technologies, improving morale, reducing downtime, and enhancing operational efficiency.
Expansion in Emerging Economies
Rapid industrialization in Asia-Pacific, Latin America, and Africa is increasing demand for machine safety systems as new manufacturing hubs seek to align with global safety standards and attract foreign investment.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for machine safety market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the machine safety market projected to grow between 2025 and 2032?
What are the primary factors fueling the growth of the machine safety market?
Who are the leading companies in the machine safety market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Component
- 1.2.1 Safety Sensors
- 1.2.2 Safety Interlock Switches
- 1.2.3 Safety Controller
- 1.2.4 Others
- 1.3 By Implementation
- 1.3.1 Embedded
- 1.3.2 Individual
- 1.4 By Industry Vertical
- 1.4.1 Automotive
- 1.4.2 Oil and Gas
- 1.4.3 Metals & Mining
- 1.4.4 Healthcare
- 1.4.5 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 5.59 billion → 2032: USD 8.71 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Machine Safety Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Machine Safety Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Machine Safety Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Machine Safety Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Machine Safety Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Machine Safety Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Machine Safety Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Machine Safety Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 5.59 billion → 2032: USD 8.71 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Machine Safety Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Component - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Safety Sensors
- 12.3.7.2 Safety Interlock Switches
- 12.3.7.3 Safety Controller
- 12.3.7.4 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Implementation - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Embedded
- 12.4.7.2 Individual
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Industry Vertical - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Automotive
- 12.5.7.2 Oil and Gas
- 12.5.7.3 Metals & Mining
- 12.5.7.4 Healthcare
- 12.5.7.5 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Machine Safety End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Machine Safety Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Machine Safety Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Machine Safety Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Siemens AG
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Emerson Electric Co.
- 18.4 Mitsubishi Electric Corporation
- 18.5 SICK AG
- 18.6 Schneider Electric SE
- 18.7 OMRON Corporation
- 18.8 B&R Automation
- 18.9 Honeywell International
- 18.10 ABB Ltd.
- 18.11 Rockwell Automation
- 18.12 KEYENCE CORPORATION
- 18.13 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

