
Market Overview
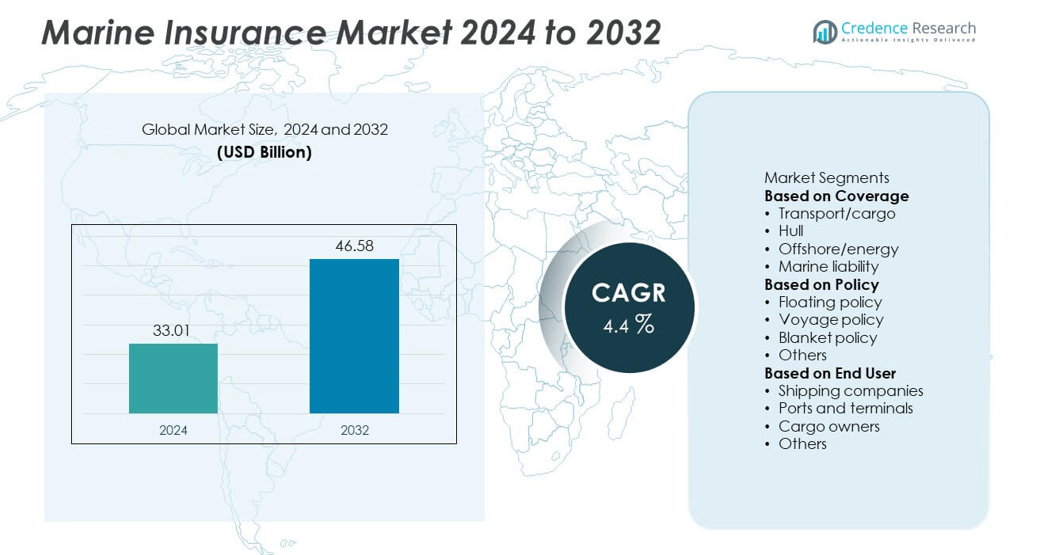
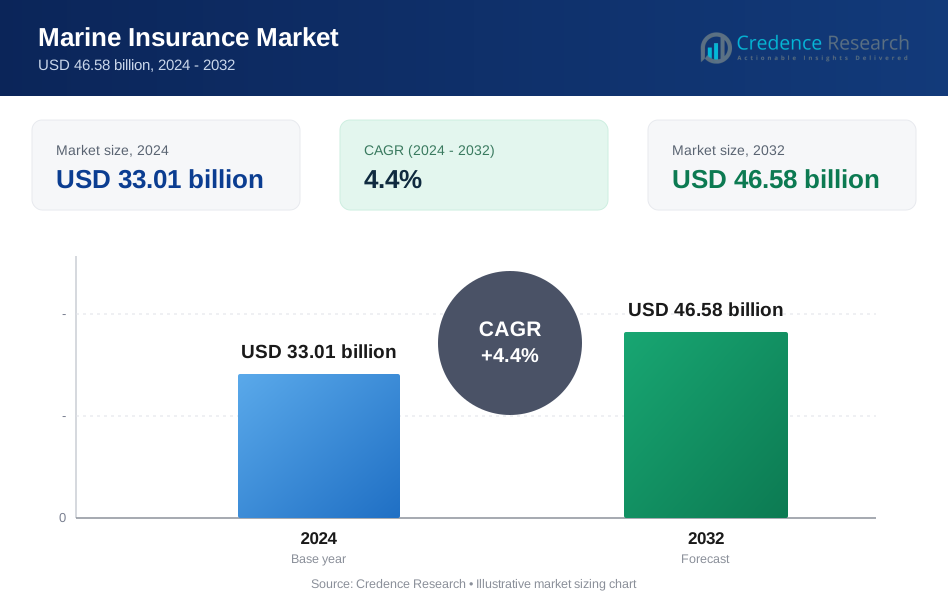
Marine Insurance Market was valued at USD 33.01 billion in 2024 and is expected to reach USD 46.58 billion by 2032, growing at a CAGR of 4.4% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Marine Insurance Market Size 2024 | USD 33.01 billion |
| Marine Insurance Market, CAGR | 4.4% |
| Marine Insurance Market Size 2032 | USD 46.58 billion |
The Marine Insurance Market grows with rising global trade volumes, stricter regulatory frameworks, and increasing exposure to climate-related risks. Shipowners and cargo operators adopt comprehensive policies to protect against accidents, piracy, and natural disasters. It also benefits from the expansion of offshore energy projects that require specialized coverage.
The Marine Insurance Market shows strong geographical presence across North America, Europe, Asia-Pacific, Latin America, and the Middle East & Africa. North America demonstrates steady adoption supported by advanced port infrastructure, offshore energy projects, and strict compliance requirements. Europe remains a major hub for underwriting, with London serving as a global center for marine insurance supported by strong regulatory oversight and sustainability-driven policies. Asia-Pacific records the fastest expansion with high cargo volumes, busy shipping lanes, and growing offshore renewable projects. Latin America and the Middle East & Africa show gradual growth, driven by increasing exports, energy exploration, and infrastructure investments. Key players influencing the market include Allianz SE, recognized for comprehensive risk solutions, Lloyd’s of London, serving as a global underwriting hub, Tokio Marine Holdings, Inc., expanding across Asia-Pacific with tailored coverage, and Zurich Insurance Group, offering strong global marine insurance portfolios with emphasis on sustainability and digital solutions.
Market Insights
- The Marine Insurance Market was valued at USD 33.01 billion in 2024 and is expected to reach USD 46.58 billion by 2032, growing at a CAGR of 4.4%.
- Rising global trade volumes, shipping activity, and offshore energy projects drive steady demand for marine insurance policies.
- Market trends focus on digital platforms, predictive analytics, and InsurTech solutions that enhance claims management, transparency, and risk evaluation.
- Leading players such as Allianz SE, Lloyd’s of London, Zurich Insurance Group, Tokio Marine Holdings, Inc., and Swiss Re shape the competitive landscape with diversified marine portfolios and tailored risk solutions.
- High claims costs, climate-related uncertainties, and evolving international regulations act as restraints, making profitability and compliance key challenges for insurers.
- North America shows strong adoption with offshore projects and regulated shipping, Europe remains a global hub with London’s underwriting dominance, and Asia-Pacific records the fastest growth with high cargo volumes and busy shipping routes.
- The overall market outlook is positive as insurers align with sustainability goals, expand cyber risk coverage, and deliver flexible policies to meet the evolving needs of global maritime stakeholders.
Market Drivers
Rising Global Trade and Shipping Activities
The Marine Insurance Market grows with the steady rise in international trade and shipping volumes. Expanding seaborne commerce requires coverage for cargo, vessels, and logistics operations. It protects businesses against losses caused by accidents, piracy, and natural hazards during transit. Increased containerization and growth in bulk shipping reinforce the demand for reliable policies. Major shipping routes across Asia-Pacific and Europe highlight the importance of risk mitigation. The continuous expansion of maritime trade strengthens adoption across global markets.
- For instance, Allianz Commercial's Safety and Shipping Review 2025 reported a record low of 27 large vessel losses globally in 2024, a significant decrease from over 200 annual losses in the 1990s. Of the 2024 losses, six were cargo vessels and 10 were fishing vessels.
Stringent Regulatory Frameworks and Compliance Needs
Government authorities and international bodies enforce strict maritime regulations to ensure safety and accountability. The Marine Insurance Market benefits from mandatory requirements that compel shipowners and cargo operators to secure adequate coverage. It ensures compliance with conventions such as SOLAS and MARPOL. Insurance providers adapt products to meet these evolving legal obligations. Shipping companies invest in comprehensive coverage to avoid penalties and disruptions. Strong regulatory frameworks encourage sustainable growth in the sector.
- For instance, AXA XL was included in the Poseidon Principles for Marine Insurance third annual disclosure report, published in February 2025, which covered 5.8% of the global Hull & Machinery portfolio across all signatories.
Growing Exposure to Natural Disasters and Climate Risks
Rising climate-related risks create greater reliance on marine insurance policies. The Marine Insurance Market addresses vulnerabilities linked to storms, floods, and unpredictable sea conditions. It provides financial protection against damage to vessels, ports, and cargoes. Increasing severity of weather patterns forces operators to adopt robust insurance solutions. Insurers develop products that account for environmental uncertainties and long-term climate impacts. This demand for climate risk management drives consistent policy uptake.
Expansion of Offshore Energy and Marine Infrastructure
The global rise in offshore oil, gas, and renewable energy projects drives insurance demand. The Marine Insurance Market supports coverage for offshore rigs, wind farms, and undersea infrastructure. It enables companies to safeguard high-value assets exposed to maritime risks. Growing investments in offshore exploration require specialized insurance offerings. Insurers tailor products to cover complex risks in construction and operations. The expansion of marine infrastructure underpins long-term market opportunities.
Market Trends
Adoption of Digital Platforms and InsurTech Solutions
The Marine Insurance Market is witnessing strong adoption of digital platforms and InsurTech innovations. Insurers deploy blockchain, AI, and data analytics to streamline claims management and risk assessment. It reduces paperwork, improves transparency, and accelerates policy issuance. Automated tools allow faster premium calculations and customized coverage options. Real-time monitoring of shipping operations enhances risk evaluation. This digital shift strengthens efficiency and customer experience across the sector.
- For instance, Tokio Marine piloted a blockchain-based marine cargo insurance certificate system that reduced certification issuance time by 85%, speeding up documentation processes for shippers.
Integration of Advanced Risk Modeling and Predictive Analytics
Growing complexity in global shipping requires advanced risk evaluation techniques. The Marine Insurance Market benefits from predictive analytics and simulation models that assess vessel performance and cargo exposure. It enables insurers to design policies tailored to specific shipping routes and cargo types. Satellite tracking and IoT data improve visibility into vessel operations. Insurers utilize these insights to optimize pricing and reduce claims disputes. The trend reflects a shift toward proactive risk management.
- For instance, marine insurers partnering with EY and Guardtime have deployed blockchain platforms, working with Microsoft’s Azure Blockchain team, to digitize contract data and reduce risk-related ambiguity during transit. This automated approach enhances accuracy and lowers exposure in underwriting.
Expansion of Specialized Coverage for Offshore Projects
Rising offshore energy and infrastructure activities create demand for niche insurance solutions. The Marine Insurance Market expands with policies covering offshore wind farms, oil rigs, and subsea assets. It supports investors by reducing financial risks linked to construction and operational hazards. Specialized underwriting teams develop products addressing complex marine environments. Growing renewable energy projects accelerate demand for tailored offshore coverage. This trend reinforces the market’s role in supporting global energy expansion.
Focus on Sustainability and Green Shipping Practices
Sustainability initiatives influence product design in marine insurance. The Marine Insurance Market aligns with the shipping industry’s decarbonization goals and green vessel investments. It encourages adoption of cleaner technologies by offering favorable policy terms for eco-friendly fleets. Insurers assess compliance with IMO 2030 and IMO 2050 emission targets. Coverage models reward operators investing in energy-efficient vessels. The trend highlights the alignment of insurance offerings with environmental responsibility.
Market Challenges Analysis
High Claims Costs and Complex Risk Assessment
The Marine Insurance Market faces challenges from rising claims costs linked to accidents, piracy, and cargo losses. Insurers struggle with complex risk assessment due to unpredictable weather conditions and geopolitical disruptions along major trade routes. It creates pressure on underwriting practices and premium pricing. High-value cargo and specialized vessels increase financial exposure for insurers. Disputes in claims settlements often delay compensation and reduce client satisfaction. Managing these risks demands advanced tools and strong industry collaboration.
Regulatory Uncertainty and Limited Profit Margins
Evolving international regulations and regional compliance standards complicate operations for insurers. The Marine Insurance Market requires continuous adaptation to frameworks such as IMO conventions and local maritime laws. It increases administrative costs and challenges profitability in competitive markets. Low premium rates and strong competition among providers further strain margins. Emerging risks such as cyberattacks on shipping systems add new layers of complexity. Maintaining compliance while delivering sustainable profitability remains a critical market challenge.
Market Opportunities
Growth Potential in Emerging Trade Routes and Developing Economies
The Marine Insurance Market presents significant opportunities with the rise of new trade corridors and expanding maritime activity in developing regions. Emerging economies in Asia-Pacific, Africa, and Latin America increase demand for cargo and hull coverage as shipping volumes rise. It supports businesses involved in bulk commodities, containerized goods, and energy transport. Expanding port infrastructure and foreign investments strengthen the need for comprehensive marine policies. Insurers offering flexible, region-specific products can capture growing market share. Developing economies provide a strong platform for long-term insurance growth.
Expansion of Digital Solutions and Cyber Risk Coverage
Rapid digitalization of shipping operations opens opportunities for insurers to introduce technology-driven products. The Marine Insurance Market benefits from demand for policies covering cyber threats, automated vessels, and IoT-enabled fleets. It enables operators to manage modern risks while ensuring compliance with global security standards. Blockchain and predictive analytics enhance claims processing and risk evaluation. Insurers offering integrated digital platforms improve transparency and customer trust. The expansion of digital services and specialized coverage strengthens the market’s future outlook.
Market Segmentation Analysis:
By Coverage
The Marine Insurance Market is segmented into cargo insurance, hull and machinery insurance, liability insurance, and offshore/energy insurance. Cargo insurance dominates due to the rising volume of global trade and the need to safeguard goods in transit. It protects shipments against risks such as theft, fire, collision, and natural hazards. Hull and machinery insurance supports shipowners by covering damage to vessels and onboard equipment. Liability insurance is gaining importance with increasing compliance requirements and risks of pollution, collisions, and crew-related liabilities. Offshore and energy insurance emerges as a vital segment, offering coverage for rigs, wind farms, and subsea operations. Each coverage type addresses distinct risks within maritime activities, making insurance solutions highly diversified.
- For instance, Allianz’s Safety and Shipping Review 2025 reported only 27 ship losses globally in 2024-of these, just 6 were cargo vessels and 10 were fishing vessels-highlighting insurers’ need to continuously tailor cargo and liability coverage based on vessel type and risk scenario.
By Policy
The Marine Insurance Market includes open cover policies, time policies, and voyage policies. Open cover policies are widely used by companies engaged in frequent shipping, offering continuous coverage for multiple consignments. It simplifies processes for exporters and logistics providers by reducing the need for repeated documentation. Time policies remain popular for shipowners, providing protection for vessels over a fixed period. Voyage policies serve cargo owners and operators seeking coverage for specific journeys, offering flexibility for irregular trade routes. Insurers balance these policies to meet varying customer needs across global shipping networks.
- For instance, Lloyd’s postponed its full digital transformation under Blueprint Two to 2028, extending the use of legacy systems in policy placement and claims processing through that year-highlighting how operational continuity shapes policy evolution.
By End User
The Marine Insurance Market serves end users including shipowners, cargo owners, and offshore energy companies. Shipowners rely on policies to protect vessels and manage operational risks. Cargo owners seek coverage to safeguard goods transported across volatile routes. Offshore energy companies demand specialized policies for rigs, pipelines, and renewable energy structures operating in harsh marine environments. It enables businesses to mitigate financial exposure and ensure operational continuity. Diverse end-user requirements push insurers to design tailored solutions that address unique risks in global maritime activities.
Segments:
Based on Coverage
- Transport/cargo
- Hull
- Offshore/energy
- Marine liability
Based on Policy
- Floating policy
- Voyage policy
- Blanket policy
- Others
Based on End User
- Shipping companies
- Ports and terminals
- Cargo owners
- Others
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis
North America
North America accounts for 32% of the Marine Insurance Market in 2024, making it one of the leading regions. The region benefits from strong shipping activity along the U.S. East Coast, Gulf of Mexico, and Canadian trade routes. The presence of established insurers and underwriters ensures comprehensive coverage for both cargo and vessel operators. It gains further strength from high demand for offshore energy insurance, particularly in oil and gas exploration zones. Strict compliance with international maritime safety standards fuels the need for liability and pollution coverage. Growth is reinforced by digital adoption, where insurers introduce platforms that streamline claims and improve transparency.
Europe
Europe holds 30% of the Marine Insurance Market in 2024, supported by major maritime hubs such as the UK, Germany, Norway, and the Netherlands. London remains a global center for marine underwriting, attracting both domestic and international clients. The region benefits from strong port infrastructure and trade connectivity across the North Sea, Baltic Sea, and Mediterranean. It shows consistent demand for hull, cargo, and liability insurance due to dense shipping lanes and offshore energy projects. It also leads in sustainability initiatives, with insurers introducing green policies aligned with European Union decarbonization goals. Europe’s regulatory environment ensures robust oversight, strengthening trust in insurance solutions.
Asia-Pacific
Asia-Pacific represents 25% of the Marine Insurance Market in 2024, recording the fastest growth. China, Japan, South Korea, and India are key contributors, driven by massive cargo volumes and expanding port infrastructure. The region is home to some of the world’s busiest shipping routes, such as the Strait of Malacca and South China Sea, creating high demand for comprehensive coverage. It benefits from rising trade flows in manufactured goods, commodities, and energy resources. Governments across Asia-Pacific invest heavily in port modernization, fueling growth in cargo and liability insurance. Increasing offshore renewable projects, including wind farms in China and Japan, further support demand. The region’s strong role in global shipping ensures sustained insurance growth.
Latin America
Latin America accounts for 7% of the Marine Insurance Market in 2024, with Brazil, Mexico, and Chile driving adoption. The region depends heavily on shipping for agricultural exports, mining products, and oil shipments. It creates steady demand for cargo and hull insurance across Atlantic and Pacific trade routes. Offshore exploration projects, particularly in Brazil’s pre-salt oil fields, increase the requirement for specialized insurance. It also benefits from growing port investments and regional trade agreements that encourage shipping expansion. Limited local underwriting capacity often pushes international insurers to strengthen their presence in Latin America.
Middle East & Africa
The Middle East & Africa region captures 6% of the Marine Insurance Market in 2024, with the UAE, Saudi Arabia, and South Africa leading activity. Strategic shipping lanes, including the Suez Canal and Strait of Hormuz, elevate the importance of marine coverage. It shows demand for cargo insurance linked to oil and gas exports, as well as rising interest in liability policies. Offshore projects in the Gulf drive specialized insurance for rigs and energy infrastructure. Africa’s reliance on maritime trade for agricultural and mineral exports supports further adoption. Gradual port modernization and trade initiatives ensure long-term market opportunities in the region.
Key Player Analysis
- Tokio Marine Holdings, Inc.
- Zurich Insurance Group
- AXA XL
- Swiss Re
- Munich Re
- Allianz SE
- The Travelers Companies, Inc.
- Lloyd's of London
- Chubb Limited
- American International Group, Inc. (AIG)
Competitive Analysis
The competitive landscape of the Marine Insurance Market is defined by leading players such as Allianz SE, American International Group, Inc. (AIG), AXA XL, Chubb Limited, Lloyd’s of London, Munich Re, Swiss Re, The Travelers Companies, Inc., Tokio Marine Holdings, Inc., and Zurich Insurance Group. These companies play a central role in shaping the global marine insurance sector by offering comprehensive coverage across cargo, hull, liability, and offshore energy risks. They focus on integrating digital platforms, predictive analytics, and blockchain technologies to enhance claims processing and improve transparency. Strategic investments in specialized products, including cyber risk coverage and green shipping initiatives, demonstrate their adaptability to evolving maritime needs. Many players expand global presence through partnerships with shipping companies, reinsurers, and port authorities, reinforcing customer trust. Competitive intensity remains strong as insurers balance regulatory compliance, profitability, and sustainability-driven offerings. Continuous innovation and diversified marine portfolios enable these companies to maintain leadership in a dynamic global market.
Recent Developments
- In June 2025, PRA, FCA, and Lloyd’s-agreed to streamline the managing agent authorization process, accelerating onboarding while maintaining standards-a key move impacting marine underwriting capabilities
- In March 2025, AIG’s Head of Marine Facultative Reinsurance, Francisco Campos, outlined evolving trends in facultative marine coverage. AIG offers cargo insurance covering Stock Throughput and Project Cargo including Delay in Start-Up, backed by a vast Latin American network across 36 territories.
- In 2025, Allianz Commercial released its Safety and Shipping Review 2025, highlighting that the number of vessels lost in 2024 reached a record low of 27 ships, down from 35 in the previous year and over 200 in the 1990s.
- In August 2024, AXA XL signed an underwriting agreement with U.S. Marine Insurance Group (US MIG) to expand its inland marine insurance offerings in logistics and supply chain sectors. The collaboration aims to provide flexible and tailored coverage for goods in transit and storage, addressing gaps left by standard policie
Report Coverage
The research report offers an in-depth analysis based on Coverage, Policy, End User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will expand with rising global shipping volumes and growing offshore energy projects.
- Digital platforms and InsurTech solutions will transform underwriting and claims management.
- Predictive analytics and AI will enhance risk modeling and pricing accuracy.
- Cyber risk coverage will become a core component of marine insurance offerings.
- Sustainability-focused policies will support green shipping and decarbonization initiatives.
- Emerging economies will drive growth with expanding port infrastructure and trade routes.
- Regulatory changes will push insurers to adapt quickly and offer compliant solutions.
- Reinsurers will play a larger role in managing large-scale climate-related risks.
- Partnerships with shipping firms and logistics companies will strengthen market penetration.
- Continuous product innovation will position marine insurance as a critical safeguard for global trade.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Global Trade and Shipping Activities
The steady increase in international trade and shipping volumes drives demand for marine insurance, as businesses seek protection for cargo, vessels, and logistics operations against losses from accidents, piracy, and natural hazards.
Stringent Regulatory Frameworks and Compliance Needs
Mandatory maritime regulations and international conventions require shipowners and cargo operators to secure adequate insurance coverage, ensuring compliance and encouraging the adoption of comprehensive policies.
Growing Exposure to Natural Disasters and Climate Risks
Increasing frequency and severity of climate-related events such as storms and floods heighten the need for robust marine insurance solutions to protect vessels, ports, and cargo from environmental uncertainties.
Expansion of Offshore Energy and Marine Infrastructure
The growth of offshore oil, gas, and renewable energy projects necessitates specialized insurance products to cover high-value assets and complex risks associated with construction and operations in marine environments.
Adoption of Digital Platforms and InsurTech Solutions
The integration of digital technologies, such as blockchain and predictive analytics, streamlines claims management, enhances risk evaluation, and improves transparency, making marine insurance more efficient and attractive to stakeholders.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Marine Insurance, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Marine Insurance market projected to grow between 2025 and 2032?
What are the primary factors fueling the growth of the Marine Insurance market?
Who are the leading companies in the Marine Insurance market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Policy
- 1.2.1 Floating Policy
- 1.2.2 Voyage Policy
- 1.2.3 Blanket Policy
- 1.2.4 Others
- 1.3 By Coverage
- 1.3.1 Transport/Cargo
- 1.3.2 Hull
- 1.3.3 Offshore/Energy
- 1.3.4 Marine Liability
- 1.4 By End User
- 1.4.1 Shipping Companies
- 1.4.2 Ports and Terminals
- 1.4.3 Cargo Owners
- 1.4.4 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 33.01 billion → 2032: USD 46.58 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Marine Insurance Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Marine Insurance Market Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Supply Chain Structure and Procurement Trends
- 5.4 Supply-Demand Gap and Bottlenecks
- 5.5 Import Dependence and Sourcing Structure
- 5.6 Regional Supply and Demand Concentration
Chapter 6 Global Marine Insurance Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Pricing by Product and Market Segment
- 6.5 Geographic Pricing Differences
- 6.6 Key Input, Energy, Labor and Logistics Costs
- 6.7 Contract Pricing and Purchasing Models
- 6.8 Pricing Sensitivity and Competitive Positioning
- 6.9 Price, Margin and Profitability Implications
Chapter 7 Global Marine Insurance Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Marine Insurance Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Marine Insurance Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Data Protection, AI and Cybersecurity Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Marine Insurance Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Marine Insurance Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 33.01 billion → 2032: USD 46.58 billion)
- 11.1.2 Historical Market Size
- 11.1.3 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 CAGR and Year-on-Year Growth
- 11.2.3 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Marine Insurance Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Policy - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Base-Year Market Share, 2024
- 12.3.5 Segment CAGR and Growth Drivers
- 12.3.6 Subsegment Market Size and Forecast
- 12.3.6.1 Floating Policy
- 12.3.6.2 Voyage Policy
- 12.3.6.3 Blanket Policy
- 12.3.6.4 Others
- 12.3.7 Subsegment Pricing and Adoption Trends
- 12.3.8 Leading Suppliers and Competition
- 12.3.9 Regional Demand and Opportunities
- 12.4 By Coverage - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Base-Year Market Share, 2024
- 12.4.5 Segment CAGR and Growth Drivers
- 12.4.6 Subsegment Market Size and Forecast
- 12.4.6.1 Transport/Cargo
- 12.4.6.2 Hull
- 12.4.6.3 Offshore/Energy
- 12.4.6.4 Marine Liability
- 12.4.7 Subsegment Pricing and Adoption Trends
- 12.4.8 Leading Suppliers and Competition
- 12.4.9 Regional Demand and Opportunities
- 12.5 By End User - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Base-Year Market Share, 2024
- 12.5.5 Segment CAGR and Growth Drivers
- 12.5.6 Subsegment Market Size and Forecast
- 12.5.6.1 Shipping Companies
- 12.5.6.2 Ports and Terminals
- 12.5.6.3 Cargo Owners
- 12.5.6.4 Others
- 12.5.7 Subsegment Pricing and Adoption Trends
- 12.5.8 Leading Suppliers and Competition
- 12.5.9 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Marine Insurance End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Marine Insurance Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Marine Insurance Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Energy Efficiency and Resource Management
- 15.7 Sustainability, Recycling and Circularity
- 15.8 Technology Roadmap, 2024-2032
- 15.9 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Marine Insurance Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Allianz SE
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Financial Performance and Investment
- 18.2.6 Market Share and Competitive Position
- 18.2.7 Technology and Innovation Capabilities
- 18.2.8 Strategic Alliances or Partnerships
- 18.2.9 Recent Developments
- 18.2.10 Growth Strategy and Outlook
- 18.3 Lloyd's of London
- 18.4 Tokio Marine Holdings, Inc.
- 18.5 Zurich Insurance Group
- 18.6 AXA XL
- 18.7 Swiss Re
- 18.8 Munich Re
- 18.9 Chubb Limited
- 18.10 The Travelers Companies, Inc.
- 18.11 American International Group, Inc. (AIG)
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

