
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Maritime Transport Consulting Service Market Size 2024 | USD 5,400 million |
| Maritime Transport Consulting Service Market, CGR | 4.4% |
| Maritime Transport Consulting Service Market Size 2032 | USD 7,620.75 million |
Market Overview:
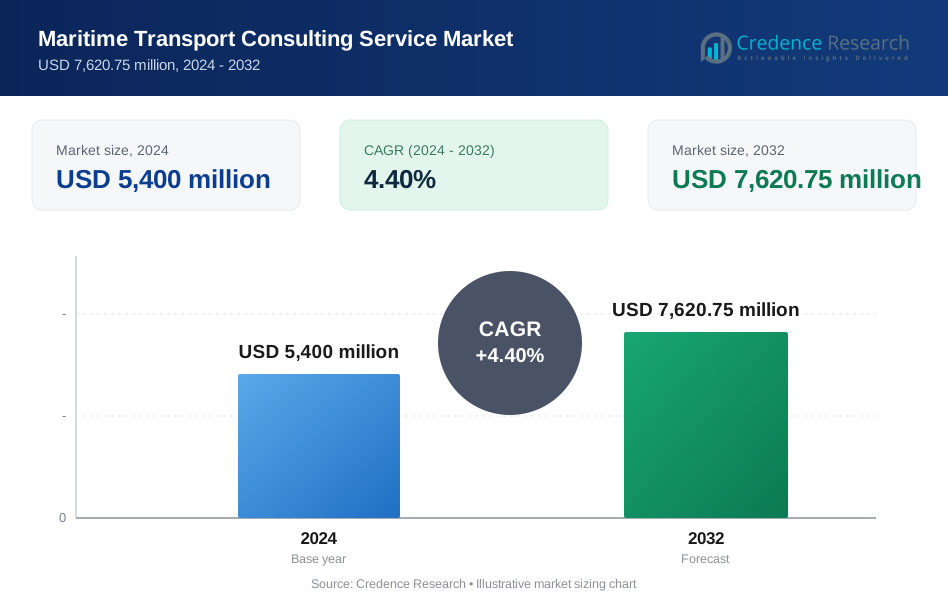
The Maritime Transport Consulting Service Market is projected to grow from USD 5,400 million in 2024 to USD 7,620.75 million by 2032, reflecting a compound annual growth rate (CAGR) of 4.4%.
The Maritime Transport Consulting Service Market is driven by the growing demand for efficient global trade logistics, increasing seaborne trade volumes, and the rising complexity of international shipping regulations. As global supply chains expand and evolve, maritime companies seek expert consulting services to optimize operations, enhance compliance, and reduce operational costs. Digital transformation in the shipping industry, including the adoption of smart port technologies, automation, and AI-driven analytics, is further accelerating the need for specialized consulting. Additionally, the emphasis on environmental sustainability and decarbonization is prompting maritime firms to invest in greener technologies and seek guidance on regulatory compliance, such as IMO emissions standards. The increasing focus on risk management, cybersecurity, and data-driven decision-making also contributes to market growth. Furthermore, emerging economies are investing in port infrastructure and maritime logistics, opening new opportunities for consulting firms. These trends collectively support the steady expansion of the maritime transport consulting service market, positioning it as a critical component of modern maritime operations.
The Maritime Transport Consulting Service Market shows strong regional diversity, with key players dominating different regions. North America, holding 20% of the market share in 2024, is driven by advanced infrastructure and regulatory frameworks, with companies like McKinsey & Company and KPMG International playing a significant role. Europe (25%) leads in sustainability initiatives, where firms like PwC and Roland Berger are prominent. Asia Pacific, the largest market with 35%, features major players like Accenture and Bain & Company, focusing on smart port development and logistics automation. The Middle East & Africa (10%) is growing rapidly, with consultants like Lloyd's Register supporting regional infrastructure expansion. Latin America (10%) sees emerging demand for consulting services, with Drewry Maritime Services and Ernst & Young driving regional growth. These regions together create a highly dynamic, competitive global market.
Market Insights:
- The Maritime Transport Consulting Service Market is projected to grow from USD 5,400 million in 2024 to USD 7,620.75 million by 2032, with a CAGR of 4.4%.
- The market is driven by increasing demand for efficient global trade logistics, rising seaborne trade volumes, and complex international shipping regulations.
- Digital transformation, including smart port technologies, automation, and AI-driven analytics, accelerates the need for specialized consulting services.
- The focus on environmental sustainability and decarbonization prompts maritime firms to seek guidance on regulatory compliance, particularly regarding IMO emissions standards.
- Emerging economies investing in port infrastructure and maritime logistics open new opportunities for consulting firms.
- North America holds 20% of the market share in 2024, driven by advanced infrastructure, regulatory frameworks, and sustainability initiatives.
- Asia Pacific leads the market with 35% of the share in 2024, supported by significant investments in port development and logistics automation.
Market Drivers:
Expansion of Global Trade and Seaborne Logistics:
The continuous growth in international trade has significantly fueled the demand for maritime transport consulting services. As global economies become increasingly interconnected, seaborne logistics play a pivotal role in facilitating the movement of goods across continents. This expansion necessitates expert guidance to optimize shipping routes, streamline port operations, and ensure cost-effective transportation solutions. For instance, Gulf Petrochem FZC commissioned i-maritime Consultants to conduct feasibility studies for their 320,000 MT bulk liquid storage terminal at Pipavav Port, Gujarat. Consulting firms provide strategic insights to help shipping companies adapt to fluctuating market dynamics, evolving trade agreements, and growing competition, thereby enhancing their operational efficiency and global reach.
Regulatory Compliance and Environmental Sustainability:
Increasingly stringent maritime regulations, particularly those targeting environmental performance, are compelling shipping companies to seek professional consulting services. The International Maritime Organization (IMO) and other regulatory bodies have introduced new standards related to emissions reduction, ballast water management, and fuel quality. To navigate these complex requirements, maritime stakeholders rely on consulting firms to assess compliance risks, implement sustainable practices, and integrate green technologies. These services are instrumental in helping organizations transition toward environmentally responsible operations while avoiding penalties and maintaining their market reputation.
Digital Transformation and Technological Advancements:
The maritime industry is undergoing a significant digital shift, with the adoption of advanced technologies such as AI, big data analytics, automation, and smart port systems. This transformation has created a surge in demand for consulting services that can assist in the integration and optimization of these digital tools. For instance, CMA CGM employs predictive analytics powered by AI to optimize container management and route planning, resulting in reduced fuel consumption and improved operational efficiency. Consultants help maritime businesses identify appropriate technologies, manage digital projects, and train personnel for new systems. By enabling efficient data utilization and process automation, these services enhance decision-making capabilities, operational transparency, and competitiveness.
Infrastructure Development and Emerging Markets:
Ongoing investments in port infrastructure and maritime facilities, especially in emerging economies, present substantial opportunities for consulting firms. Governments and private entities are focusing on modernizing ports to accommodate larger vessels and improve cargo handling capabilities. Consulting services are essential in project planning, design, and implementation phases, ensuring successful execution and long-term viability. These developments not only drive regional economic growth but also expand the scope of maritime consulting services worldwide.
Market Trends:
Adoption of Digital and Smart Technologies:
The maritime transport consulting service market is witnessing a strong trend toward the adoption of digital and smart technologies. As the shipping industry modernizes, there is an increased focus on implementing automation, AI, IoT, and blockchain to enhance operational efficiency and transparency. Consulting firms are playing a crucial role in guiding maritime companies through digital transformation, helping them select and integrate technologies that align with their strategic goals. This trend is particularly evident in smart port development, where real-time data analytics and automated systems are streamlining port operations and improving turnaround times.
Emphasis on Environmental Sustainability:
Sustainability has become a central focus in the maritime industry, driven by global climate initiatives and stricter environmental regulations. The consulting market is experiencing rising demand for services that assist with environmental compliance, emission reduction strategies, and the adoption of alternative fuels. For instance, Wallenius Wilhelmsen, based in Norway and Sweden, is pioneering zero-emission ship concepts like the “E/S Orcelle,” which utilizes renewable energy sources such as wind, solar, and hydrogen. Maritime consultants are also advising on carbon offset mechanisms, green ship design, and lifecycle assessments to help clients align with the International Maritime Organization’s decarbonization goals. This trend is shaping long-term investment and operational decisions across the sector.
Integration of Cybersecurity Solutions:
With increasing digitization, cybersecurity has emerged as a critical concern for the maritime industry. Consulting firms are offering specialized services to assess cybersecurity risks, develop response strategies, and ensure regulatory compliance. For instance, Darktrace's AI-driven cybersecurity solutions successfully thwarted a malware attack targeting a maritime transportation company in Greenland by identifying unusual network activity and alerting the security team, preventing data breaches and operational disruptions. As vessels and port systems become more connected, the need to protect sensitive data and prevent operational disruptions is driving the integration of robust cybersecurity frameworks. This trend reflects a proactive approach to managing digital risks and safeguarding global maritime infrastructure.
Rise of Customized and Data-Driven Solutions:
There is a growing trend toward tailored consulting services that leverage data analytics to address specific client needs. Maritime transport companies are seeking customized solutions based on real-time data, predictive modeling, and performance benchmarking. Consultants are increasingly using data-driven tools to enhance route optimization, cost management, and risk assessment. This shift toward personalized, insights-based consulting is enabling clients to make more informed decisions and achieve measurable improvements in their operations.
Market Challenges Analysis:
Complex Regulatory Landscape and Compliance Pressure:
The Maritime Transport Consulting Service Market faces a considerable challenge in addressing the increasingly intricate regulatory landscape that governs global shipping. Maritime regulations, primarily led by international organizations like the International Maritime Organization (IMO), are continuously evolving to address environmental sustainability, vessel safety, crew welfare, and cargo security. These regulations differ significantly across regions, making compliance a multifaceted task for global shipping companies. Consulting firms must not only interpret these complex frameworks but also ensure their clients implement them effectively to avoid penalties and reputational damage. The challenge is further compounded by the need for real-time updates and adaptations, particularly as new emission standards and decarbonization goals are introduced. Maintaining an up-to-date understanding of all applicable laws requires significant investment in research and policy tracking. Additionally, clients operating in multiple jurisdictions need localized compliance strategies, placing greater demand on consultants to provide customized, jurisdiction-specific solutions while managing increasing operational and advisory costs.
High Implementation Costs and Technological Adaptation Barriers:
A key challenge within the Maritime Transport Consulting Service Market lies in the financial and operational barriers associated with implementing advanced technological recommendations. While the maritime sector is undergoing a digital transformation, many companies-especially small and mid-sized operators-struggle to afford the high upfront costs of integrating smart technologies, automation systems, or alternative fuel infrastructure. Even with strategic guidance from consultants, clients often hesitate to execute digital initiatives due to concerns about return on investment, long-term maintenance expenses, or disruptions to current operations. For instance, the Cuban Maritime Administration faces significant challenges in upgrading its centralized and outdated infrastructure, which limits the adoption of modern cost-control systems and alternative fuel technologies, despite their potential to improve operational efficiency. Moreover, the prevalence of legacy systems and outdated infrastructure can limit the compatibility of new technologies, making transitions more complex and risk-prone. Resistance to change from within the organization, driven by lack of technical expertise or fear of redundancy, further slows adoption. Consulting firms are increasingly required not only to offer innovative strategies but also to provide hands-on implementation support, change management training, and long-term performance monitoring to ensure sustainable success.
Market Opportunities:
The Maritime Transport Consulting Service Market is poised to benefit from expanding global trade routes and ongoing port infrastructure developments, particularly in emerging economies. As nations invest heavily in modernizing their maritime facilities to accommodate larger vessels and enhance cargo throughput, the demand for expert consulting services in planning, design, and operational efficiency is set to rise. Consultants are increasingly called upon to guide strategic investments, optimize port layouts, and implement smart technologies that improve overall productivity. Furthermore, the growth of specialized shipping segments, such as LNG transport and offshore renewable energy logistics, presents new avenues for consulting firms to deliver niche expertise. As supply chains become more complex, the need for streamlined logistics and risk mitigation strategies will open new doors for consultancy services that can offer data-driven solutions and tailored operational models.
In addition to infrastructure and logistics growth, the market presents strong opportunities through the global push toward sustainability and decarbonization in the maritime industry. The enforcement of stricter environmental regulations, such as the IMO’s emission reduction targets, has led shipping companies to seek guidance on green technologies, alternative fuels, and energy-efficient vessel designs. Consulting firms that specialize in environmental compliance and sustainable maritime practices are well-positioned to support this transition, offering services such as carbon footprint assessments, regulatory roadmaps, and ESG reporting strategies. Moreover, digitalization efforts across the maritime sector continue to gain momentum, creating demand for consultants who can facilitate the integration of AI, blockchain, and IoT systems into vessel and port operations. As the industry embraces smart shipping and data analytics, consultants offering innovative digital solutions will find ample opportunity to drive transformation and add long-term value to maritime clients. These emerging trends suggest a positive outlook for firms that can adapt to the sector’s shifting needs and deliver forward-thinking, impact-oriented strategies.
Market Segmentation Analysis:
By Service Type
The Maritime Transport Consulting Service Market is segmented into strategic, operational, technical, market entry, and regulatory compliance consulting. Strategic consulting remains essential for long-term planning and global expansion. Operational and technical consulting support efficiency and innovation, while regulatory compliance and market entry consulting address complex legal environments and new market penetration.
By Client Type
Key client segments include shipping companies, port authorities, government bodies, logistics providers, and trade organizations. Shipping companies and port authorities represent the largest demand due to their need for efficiency, safety, and regulatory alignment. Meanwhile, logistics providers and trade organizations seek consulting to streamline operations and enhance international trade logistics.
By Service Application
Applications of maritime consulting include fleet management, supply chain optimization, environmental compliance, cost reduction strategies, and risk management. Fleet and supply chain services support operational effectiveness, while environmental compliance and risk management align with growing regulatory pressures and sustainability goals, creating ongoing demand for specialized consulting expertise.
Segments:
Based on Service Type
- Strategic Consulting
- Operational Consulting
- Technical Consulting
- Market Entry Consulting
- Regulatory Compliance Consulting
Based on Client Type
- Shipping Companies
- Port Authorities
- Government Bodies
- Logistics Providers
- Trade Organizations
Based on Service Application
- Fleet Management
- Supply Chain Optimization
- Environmental Compliance
- Cost Reduction Strategies
- Risk Management
Based on Market Focus
- Bulk Shipping
- Container Shipping
- Tankers
- Roll-on/Roll-off (RoRo)
- Specialized Freight
Based on Technology Adoption
- Traditional Methods
- Digital Solutions
- Automation Technologies
- Data Analytics
- Blockchain in Shipping
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
In 2024, North America holds 20% of the global Maritime Transport Consulting Service Market share. The region benefits from advanced port infrastructure, established shipping companies, and a strong regulatory framework. The United States leads in digital transformation and sustainability initiatives, driving demand for consulting in automation, cybersecurity, and environmental compliance. Green port investments and the push for operational efficiency continue to enhance the market presence of consulting services. Collaborative efforts between the public and private sectors are further accelerating the adoption of innovative maritime strategies across North American ports and logistics networks.
Europe
Europe commands 25% of the global market share in 2024. The region is characterized by strict environmental regulations and progressive maritime policies, leading to high demand for consulting in sustainability and regulatory compliance. Countries like Germany, the Netherlands, and the United Kingdom are heavily investing in decarbonization, fleet modernization, and emissions control technologies. Maritime consultants are central to advising on green transition strategies and helping clients navigate complex EU maritime laws. Europe’s leadership in promoting clean shipping and innovative port operations reinforces its prominent position in the global market.
Asia Pacific
Asia Pacific leads the global market with the highest share of 35% in 2024. This dominance is driven by major shipping economies such as China, Japan, South Korea, and Singapore. Rapid industrialization, trade expansion, and massive port infrastructure projects are fueling demand for consulting services in this region. Consultants are instrumental in supporting smart port development, logistics automation, and regulatory adherence. As governments across the region continue to invest in digital maritime systems and integrated supply chains, Asia Pacific remains at the forefront of consulting-led innovation and strategic maritime growth.
Middle East & Africa
The Middle East & Africa account for 10% of the market share in 2024. Growth in this region is driven by expanding port infrastructure, especially in Gulf Cooperation Council countries. The UAE and Saudi Arabia are leading efforts in maritime innovation, prompting demand for consulting services in technical planning, compliance, and operational efficiency. As governments prioritize maritime logistics to diversify their economies, consulting firms are gaining relevance in regional development plans and trade facilitation strategies.
Latin America
Latin America holds 10% of the global market share in 2024. Countries such as Brazil, Chile, and Panama are investing in port modernization and sustainable maritime practices. Consulting services are increasingly required to support environmental compliance, cost optimization, and supply chain enhancements. Regional efforts to improve maritime infrastructure are gradually creating new opportunities for consultants to influence policy development and infrastructure efficiency.
Key Player Analysis:
- Ernst & Young (EY)
- Roland Berger
- McKinsey & Company
- DNV GL
- AlixPartners
- PwC (PricewaterhouseCoopers)
- Bain & Company
- KPMG International
- Drewry Maritime Services
- Boston Consulting Group (BCG)
- Lloyd's Register
- Accenture
Competitive Analysis:
The Maritime Transport Consulting Service Market is highly competitive, with several leading players driving innovation and market growth. Companies like McKinsey & Company, Boston Consulting Group (BCG), Bain & Company, Drewry Maritime Services, Lloyd's Register, DNV GL, KPMG International, PwC (PricewaterhouseCoopers), Ernst & Young (EY), Accenture, Roland Berger, and AlixPartners are leveraging their extensive expertise to provide specialized solutions in areas such as operational efficiency, regulatory compliance, sustainability, and digital transformation. McKinsey & Company and BCG focus on strategic consulting, helping clients navigate complex global trade dynamics. Meanwhile, Drewry Maritime Services and DNV GL excel in providing technical and market entry consulting. Companies like PwC and EY offer strong regulatory compliance advisory services, while Accenture and Roland Berger emphasize technology-driven solutions for smart ports and logistics optimization. The diversity of expertise across these players creates a dynamic, competitive landscape, encouraging continual service innovation and market diversification to meet evolving industry demands.
Recent Developments:
- In November 2023, Roland Berger signed a contract with Vietnam Maritime Corporation (VIMC) to develop a 10-year strategy, aiming to transform VIMC into the leading integrated maritime logistics group in Vietnam with global reach.
- In April 2025, DNV expanded its operations in Ireland by acquiring Enviroguide Consulting, aiming to strengthen its sustainability expertise and support Ireland’s energy transition goals.
- In March 2025, Bain continued engagements across various transportation sectors, focusing on digital transformation, sustainability, and post-merger integration for maritime clients.
- In April 2025, LR formed a partnership with Royal Caribbean Group to advance maritime safety and efficiency across the cruise sector.
- On April 10, 2025, Accenture announced a joint venture with Fincantieri called Fincantieri Ingenium. This initiative aims to accelerate digital transformation in shipbuilding and port logistics by developing AI-driven platforms and digital ecosystems like Navis Sapiens for next-generation ships.
Market Concentration & Characteristics:
The Maritime Transport Consulting Service Market exhibits moderate concentration, with a mix of large multinational firms and specialized consultancies playing pivotal roles in shaping market dynamics. Leading global consulting firms such as McKinsey & Company, BCG, and DNV GL dominate the high-value segments, leveraging their broad industry experience and extensive resources to provide comprehensive solutions across multiple regions. However, there is also significant space for niche players who focus on specific areas such as regulatory compliance, environmental sustainability, and smart port technologies. These firms often deliver specialized, localized services tailored to specific geographic needs, allowing them to carve out strong positions in emerging markets. The market is characterized by a strong emphasis on technological innovation, sustainability, and regulatory expertise, with increasing demand for consultants who can offer data-driven insights and forward-thinking strategies. As global trade and maritime regulations evolve, the market is likely to see continued diversification and competition.
Report Coverage:
The research report offers an in-depth analysis based on Service Type, Client Type, Service Application, Market Focus, Technology Adoption and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The demand for maritime transport consulting services will continue to grow as global trade volumes increase and shipping operations become more complex.
- Regulatory compliance will remain a key focus, with an emphasis on evolving environmental standards and decarbonization efforts in the shipping industry.
- The adoption of smart port technologies, automation, and AI-driven analytics will create further opportunities for consulting firms in the digital transformation space.
- Emerging economies will drive the need for consulting services as they invest in upgrading port infrastructure and improving logistical capabilities.
- Sustainability will become a critical component of maritime consulting, with a growing need for green technologies and emissions reduction strategies.
- Consultants will play a pivotal role in helping maritime businesses manage and mitigate cybersecurity risks as digitalization intensifies.
- The integration of blockchain and IoT into maritime operations will increase the demand for consulting services to optimize data-driven decision-making.
- Supply chain optimization will remain a priority, with consulting services focusing on improving efficiency and cost-effectiveness in shipping routes and port operations.
- Regional market dynamics will shape consulting strategies, with a focus on understanding and navigating local regulations and infrastructure needs.
- Strategic partnerships and collaborations among industry leaders will foster innovation and expand the scope of consulting services across global markets.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Maritime Transport Consulting Service Market?
What factors are driving the growth of the Maritime Transport Consulting Service Market?
What are some challenges faced by the Maritime Transport Consulting Service Market?
Who are the major players in the Maritime Transport Consulting Service Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Maritime Transport Consulting Service Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Maritime Transport Consulting Service Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 5,400 million → 2032: USD 7,620.75 million)
- 2.1.2 Volume & Revenue – Global Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Maritime Transport Consulting Service Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Maritime Transport Consulting Service Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Maritime Transport Consulting Service Market Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Maritime Transport Consulting Service Market Drivers
- 3.3 Maritime Transport Consulting Service Market Restraints & Challenges
- 3.4 Maritime Transport Consulting Service Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Maritime Transport Consulting Service Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Maritime Transport Consulting Service Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Maritime Transport Consulting Service category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Maritime Transport Consulting Service Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Region – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Priority market opportunity scorecards reflect the geographic scope and strategic relevance of the study. Listed markets are indicative and may be adapted to the industry.
Chapter 5. Maritime Transport Consulting Service Cross-Border Trade & Market Access Analysis
- 5.1 International Trade & Cross-Border Activity Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024) (Volume Where Applicable)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter applies where cross-border trade or delivery is relevant to Maritime Transport Consulting Service. Goods, services, and digital offerings are assessed using applicable classifications and transaction measures. Import-export volumes, trade balances, and route analyses are included only where meaningful to the market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Maritime Transport Consulting Service Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Maritime Transport Consulting Service Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company (Volume Where Applicable)
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Global Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Maritime Transport Consulting Service Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Maritime Transport Consulting Service (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Maritime Transport Consulting Service
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Maritime Transport Consulting Service Market – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share (Volume Where Applicable)
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region (Volume Where Applicable)
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. North America Maritime Transport Consulting Service Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Maritime Transport Consulting Service Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Maritime Transport Consulting Service Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Maritime Transport Consulting Service Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Maritime Transport Consulting Service Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Maritime Transport Consulting Service Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Maritime Transport Consulting Service Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
