
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| MENA Drip Irrigation Systems Market Size 2024 | USD 306.2 million |
| MENA Drip Irrigation Systems Market, CAGR | 18.7% |
| MENA Drip Irrigation Systems Market Size 2032 | USD 1206.73 million |
Market Overview:
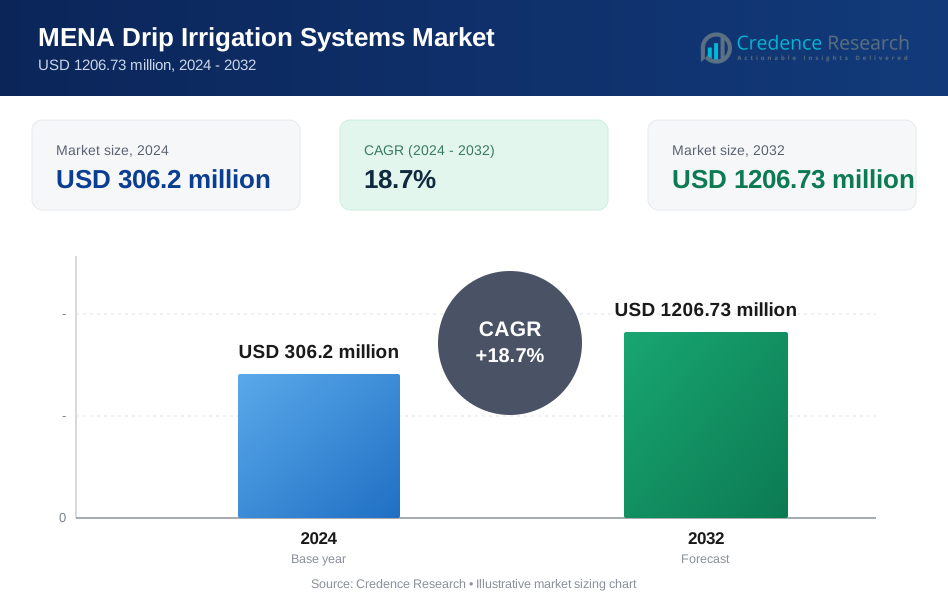
The MENA Drip Irrigation Systems Market is projected to grow from USD 306.2 million in 2024 to an estimated USD 1206.73 million by 2032, with a compound annual growth rate (CAGR) of 18.7% from 2024 to 2032.
The MENA Drip Irrigation Systems market is primarily driven by several key factors. The region's scarce water resources, combined with the growing demand for food due to population growth, have made efficient irrigation systems a necessity. Governments across MENA countries are increasingly supporting sustainable agricultural practices through subsidies and favorable policies to encourage the adoption of drip irrigation systems. Additionally, technological advancements in irrigation systems, such as automated control systems and innovations in drip emitters, are enhancing the efficiency and effectiveness of drip irrigation. Increasing awareness among farmers about the long-term benefits of drip irrigation, such as reduced water consumption and higher crop productivity, is also contributing to the market's expansion. Moreover, the growing trend towards high-value crops and precision agriculture is accelerating the adoption of drip irrigation systems across the region. The rising cost of water and energy is further pushing farmers to adopt more efficient irrigation methods.
Regionally, countries such as Saudi Arabia, the United Arab Emirates, and Egypt are leading the MENA drip irrigation systems market due to their high agricultural output and government initiatives focused on sustainable water use. In Saudi Arabia, the government has been promoting the use of advanced irrigation technologies to improve water efficiency. Egypt, with its agriculture-dependent economy, has also shown substantial growth in adopting drip irrigation to increase crop yields. The UAE, with limited arable land, is investing heavily in modern farming techniques, including drip irrigation, to ensure food security. Other MENA countries are also increasingly adopting drip irrigation systems to combat water scarcity and boost agricultural productivity. Countries like Morocco and Jordan are also stepping up efforts to modernize their irrigation systems, driven by water scarcity challenges and government-led sustainability programs. This regional push is expected to boost the adoption of drip irrigation systems in both small and large-scale farming operations across the region.
Market Drivers:
Water Scarcity and Need for Efficient Water Management:
One of the most significant drivers of the MENA drip irrigation systems market is the region's chronic water scarcity. MENA is one of the most water-stressed regions in the world, with limited freshwater resources and a growing population that intensifies the demand for water. Agriculture accounts for a large portion of water usage, and inefficient irrigation practices further strain water availability. Drip irrigation systems provide a solution by delivering water directly to the roots of plants, minimizing evaporation and runoff, and ensuring that water is used efficiently. As water conservation becomes a top priority for both governments and farmers, the adoption of drip irrigation systems is gaining traction across the region.
Government Initiatives and Policy Support:
Governments in the MENA region are actively promoting sustainable agricultural practices to address food security challenges and mitigate the impact of climate change. Various governments have introduced policies and subsidies aimed at encouraging the use of advanced irrigation technologies, including drip irrigation systems. These initiatives are driven by the recognition that improving water efficiency in agriculture is critical for long-term food production and environmental sustainability. For instance, countries like Saudi Arabia and Egypt have launched programs to modernize their irrigation infrastructure, providing financial incentives to farmers to switch from traditional flood irrigation to more efficient drip irrigation systems. In Saudi Arabia, the government has subsidized 50% of the cost of drip irrigation systems for farmers. Such government support is playing a key role in expanding the market for drip irrigation systems in the region.
Technological Advancements in Irrigation Systems:
The MENA drip irrigation systems market is also benefiting from ongoing technological advancements that enhance the performance and accessibility of these systems. Innovations such as automated control systems, smart sensors, and remote monitoring are making drip irrigation more efficient and user-friendly. These technologies allow farmers to monitor soil moisture levels, weather conditions, and crop needs in real time, enabling precise water management4. Furthermore, advancements in drip emitters and tubing materials have improved the durability and effectiveness of drip irrigation systems, making them more attractive to farmers. For example, the International Center for Agricultural Research in the Dry Areas (ICARDA) has developed ultra-low energy drip irrigation systems that cut pumping energy by 50%. As technology continues to evolve, the integration of digital tools in irrigation management is expected to further drive the market growth in MENA.
Growing Awareness of the Benefits of Drip Irrigation:
Another critical driver of the MENA drip irrigation systems market is the increasing awareness among farmers and agricultural stakeholders of the long-term benefits associated with this irrigation method. Drip irrigation not only conserves water but also enhances crop yields, reduces soil erosion, and improves nutrient uptake. Farmers are becoming more conscious of the economic advantages of using drip irrigation, including lower operational costs and increased productivity. As more success stories and case studies emerge from early adopters in the region, the perception of drip irrigation is shifting from a costly investment to a necessary tool for sustainable farming. This growing awareness is expected to further accelerate the adoption of drip irrigation systems across the MENA region in the coming years.
Market Trends:
Increasing Adoption of Precision Agriculture:
One of the emerging trends in the MENA drip irrigation systems market is the growing shift towards precision agriculture. Precision farming practices focus on optimizing resource use, including water, fertilizers, and pesticides, to enhance crop productivity while minimizing waste. Drip irrigation systems are integral to precision agriculture, as they allow for the precise delivery of water directly to the plant roots, reducing water consumption and ensuring optimal growth conditions. In the MENA region, where water scarcity is a critical concern, farmers are increasingly adopting precision agriculture techniques, supported by drip irrigation, to maximize efficiency and productivity. For instance, in Morocco, precision agriculture techniques have led to a 30% increase in crop yields. This trend is expected to gain further momentum as technological advancements in sensors and data analytics improve irrigation management.
Integration of Smart Irrigation Technologies:
Another significant trend shaping the MENA drip irrigation systems market is the integration of smart irrigation technologies. Farmers in the region are increasingly leveraging advanced technologies such as Internet of Things (IoT) devices, soil moisture sensors, and automated control systems to optimize irrigation schedules. These technologies allow farmers to monitor real-time weather conditions, soil moisture levels, and crop water requirements, enabling more accurate and efficient water use. Smart irrigation systems can automatically adjust water flow based on data inputs, reducing water waste and improving crop health. For example, the Sustainable City in Dubai has implemented smart irrigation systems that resulted in 40% water savings and healthier root zones. As the demand for sustainable and efficient irrigation solutions grows, the integration of smart technologies into drip irrigation systems is expected to accelerate across the MENA region.
Rising Focus on Sustainable Agriculture:
Sustainability is becoming a central focus in agricultural practices across the MENA region, driven by the need to conserve natural resources and mitigate the impacts of climate change. Drip irrigation systems are being increasingly recognized as a key component of sustainable agriculture, as they offer a more efficient way to manage water resources. With agriculture accounting for the majority of water consumption in the region, there is a growing emphasis on reducing water usage while maintaining high levels of productivity. Farmers and policymakers alike are adopting drip irrigation as part of broader efforts to promote environmentally responsible farming practices. This focus on sustainability is expected to continue driving the demand for drip irrigation systems in the coming years.
Expansion of Drip Irrigation in Non-Traditional Crops:
Traditionally, drip irrigation systems have been widely used for high-value crops such as fruits and vegetables, which require precise water management. However, a notable trend in the MENA region is the expansion of drip irrigation into non-traditional crops, including cereals and pulses. As water scarcity challenges persist, farmers are recognizing the benefits of using drip irrigation to improve yields and reduce water consumption even for staple crops. This trend is supported by government programs aimed at modernizing irrigation practices across different crop types. The diversification of drip irrigation applications to include a broader range of crops is expected to contribute to the steady growth of the market in the region.
Market Restraints and Challenges:
High Initial Installation Costs:
One of the key restraints in the MENA drip irrigation systems market is the high initial cost of installation. Drip irrigation systems require significant capital investment for equipment such as pipes, emitters, and filtration units, as well as skilled labor for installation. For small-scale farmers or those operating in economically disadvantaged areas, these upfront costs can be prohibitive, limiting the widespread adoption of drip irrigation systems. Although long-term savings on water and improved crop yields may offset these costs, the initial financial outlay remains a significant barrier for many farmers in the region.
Lack of Technical Knowledge and Expertise:
Another challenge in the MENA drip irrigation systems market is the lack of technical knowledge and expertise among farmers. Many farmers in the region, especially in rural areas, are unfamiliar with the operation and maintenance of drip irrigation systems. This lack of knowledge can lead to inefficient use of the technology, such as improper installation or inadequate maintenance, which reduces the system's effectiveness and lifespan. Additionally, farmers may be unaware of the long-term benefits of drip irrigation, further limiting its adoption. Addressing this challenge will require increased education and training programs for farmers, as well as technical support services to ensure the proper use of drip irrigation systems.
Limited Access to Financing:
Access to financing is another significant restraint in the MENA drip irrigation systems market. Many farmers, particularly smallholders, face challenges in securing loans or financial assistance to invest in drip irrigation technology. Despite government subsidies and support programs in some countries, financial institutions may be hesitant to lend to farmers due to the perceived risks associated with agriculture in the region. This limits farmers' ability to adopt drip irrigation systems, especially when combined with the high initial costs. Expanding access to affordable financing options will be crucial in overcoming this challenge and supporting market growth.
Market Segmentation Analysis:
By Emitter Type, the market is divided into inline emitters and online emitters. Inline emitters, which are integrated within the tubing, are widely used for uniform irrigation and are preferred for row crops. On the other hand, online emitters, attached externally to the tubing, offer flexibility in placing emitters near plants, making them suitable for crops with varying water needs.
By Component, the market includes drippers, filters, valves, tubing, and others. Drippers are critical for controlling the flow of water, and advancements in dripper technology have improved water efficiency. Filters play a vital role in preventing clogging, ensuring the longevity of the system. Valves are essential for regulating water pressure, while tubing is the backbone of the system, distributing water across the fields. Other components, such as connectors and pressure regulators, further enhance system performance.
By Application, the market is segmented into agriculture, greenhouse, and others. Agriculture is the dominant segment, with drip irrigation systems being widely adopted for cultivating fruits, vegetables, and cereals. Greenhouses are increasingly using drip irrigation for controlled environments, where water conservation is crucial. The "others" category includes landscaping and nurseries, where drip irrigation is used to maintain efficient watering practices in non-agricultural settings.
Segmentation:
By Emitter Type
- Inline Emitters
- Online Emitters
By Component
- Drippers,
- Filters,
- Valves,
- Tubing,
- Others
By Application
- Agriculture,
- Greenhouse,
- Others
- North America
- The U.S
- Canada
- Mexico
- Europe
- Germany
- France
- The U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of Middle East and Africa
Regional Analysis:
Saudi Arabia
Saudi Arabia holds a dominant position in the MENA drip irrigation systems market, accounting for approximately 30% of the overall market share. The country has been focusing on reducing its reliance on traditional flood irrigation methods, which are inefficient in water use. Government initiatives, such as subsidies and modern irrigation programs, are aimed at promoting drip irrigation to conserve water in agriculture. With a significant portion of its arable land dedicated to wheat and alfalfa cultivation, Saudi Arabia is increasingly adopting drip irrigation systems to manage its limited water resources. This region's market growth is driven by its focus on sustainable agricultural practices and food security.
Egypt
Egypt represents around 25% of the MENA drip irrigation systems market, primarily due to its agriculture-dependent economy. With the Nile River providing limited water resources and a rapidly growing population, the Egyptian government has been actively promoting the use of efficient irrigation systems. Drip irrigation is gaining traction in Egypt, particularly in the cultivation of high-value crops such as fruits and vegetables. Government-led programs aimed at modernizing irrigation infrastructure, along with international funding, have further supported the adoption of drip irrigation in Egypt. The country’s emphasis on water conservation in agriculture is expected to continue driving market growth.
United Arab Emirates (UAE)
The UAE contributes about 20% of the MENA drip irrigation systems market. With its arid desert climate and limited availability of freshwater, the UAE has become a leader in adopting advanced irrigation technologies. The country has invested heavily in modernizing its agricultural sector, with a focus on sustainable water management solutions like drip irrigation. Despite its small agricultural footprint, the UAE’s use of drip irrigation is widespread in greenhouses and for landscaping purposes, supporting the growth of the market.
Morocco
Morocco holds around 15% of the market share in the MENA drip irrigation systems market. The country faces significant water scarcity challenges, which have pushed it to adopt efficient irrigation technologies. Drip irrigation is increasingly being used in Morocco for the cultivation of fruits, olives, and other high-value crops. The government has implemented several programs to promote the use of drip irrigation, providing subsidies and technical support to farmers. As a result, Morocco has seen substantial growth in drip irrigation adoption over recent years.
Other MENA Countries
The remaining 10% of the MENA drip irrigation systems market is spread across other countries, including Jordan, Tunisia, and Algeria. These countries are gradually adopting drip irrigation systems as part of their efforts to address water scarcity and improve agricultural productivity. Government policies, coupled with international support, are playing a crucial role in driving adoption in these regions.
Key Player Analysis:
- M.A. Horticulture Inc.
- Agri-Inject
- M. Agri Solutions
- Antelco Pty Ltd.
- Bowsmith
- Chinadrip Irrigation Equipment Co., Ltd.
- Elgo Irrigation Ltd.
- EPC Industries Ltd.
- Hunter Industries
- IRRITEC S.P.A.
- Jain Irrigation Systems Ltd.
- Lindsay Corporation
- Microjet
- NaanDan Jain Irrigation
- Netafim
- Rain Bird Corporation
- RIVULIS Irrigation
- The Toro Company
Competitive Analysis:
The MENA drip irrigation systems market is competitive, with several global and regional players vying for market share. Leading companies include Netafim, Jain Irrigation Systems, Rivulis Irrigation, and Rain Bird Corporation. These key players are known for their advanced drip irrigation technologies and strong distribution networks across the region. Netafim, in particular, has a strong presence in the MENA market, offering a wide range of drip solutions tailored for arid climates. Local companies such as Saudi-based Metito and Egypt’s Modern Water Systems also play a crucial role, leveraging their knowledge of regional agricultural needs. The competitive landscape is further influenced by government initiatives promoting water-efficient farming practices. Companies are focusing on innovation, offering smart irrigation solutions, and expanding their presence in emerging markets within MENA to gain a competitive edge. Strategic partnerships and technological advancements continue to shape the competition in the region.
Recent Developments:
- In February 2024, Irritec, a leading Italian company specializing in irrigation solutions, merged with a regional distributor to expand its market presence in the Middle East. This strategic partnership enables Irritec to strengthen its foothold in the region by leveraging the distributor's local expertise and network. The collaboration aims to enhance access to Irritec’s innovative irrigation products, allowing the company to better serve the growing agricultural market in the Middle East while reinforcing its position as a global leader in the irrigation industry.
- In April 2023, The Toro Company, a global leader in outdoor environment solutions, acquired a technology firm specializing in precision irrigation. This acquisition enhances Toro's ability to deliver advanced irrigation technologies, strengthening its position in the agricultural sector. By integrating the firm’s expertise, Toro aims to improve water management efficiency and promote sustainable farming practices, aligning with its commitment to innovation and environmental responsibility.
- In July 2022, Jain Irrigation Systems Limited (JISL) expanded its production facility in Saudi Arabia to meet the rising demand for efficient irrigation systems. This expansion is part of JISL's global strategy to enhance its manufacturing capabilities and support sustainable agriculture in local markets across the MENA region.
Market Concentration & Characteristics:
The MENA drip irrigation systems market is moderately concentrated, with a few key players, such as Netafim, Jain Irrigation Systems, and Rivulis Irrigation, holding significant market share. These companies dominate due to their technological expertise, extensive product portfolios, and established distribution networks across the region. However, the market also includes a mix of regional and local players who cater to specific country needs, such as Metito and Modern Water Systems, which focus on delivering tailored solutions for arid and water-scarce environments. The market is characterized by a growing focus on sustainability, with increased adoption of smart irrigation technologies and precision farming practices. Government support in the form of subsidies and water management programs has also been a defining feature, encouraging both large-scale commercial farms and smallholders to adopt drip irrigation. The market’s competitive dynamics are driven by innovation and a rising demand for efficient water management solutions.
Report Coverage:
The research report offers an in-depth analysis based By Emitter Type, By Component and By Application. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Increasing government support for water conservation initiatives will drive widespread adoption of drip irrigation systems.
- Technological advancements in smart irrigation will enhance the efficiency and precision of water usage in agriculture.
- Rising food demand due to population growth will push farmers to adopt more efficient irrigation methods.
- Expansion of drip irrigation to non-traditional crops such as cereals and pulses will diversify its applications.
- Growing awareness of sustainable farming practices will further promote the adoption of water-efficient irrigation systems.
- Continued investment in agricultural infrastructure, particularly in Saudi Arabia and Egypt, will fuel market growth.
- Partnerships between global companies and local distributors will strengthen regional supply chains and distribution networks.
- Increasing availability of financing and subsidies for small and mid-sized farmers will lower barriers to entry for drip irrigation.
- Integration of renewable energy sources, such as solar-powered pumps, will reduce operational costs for farmers.
- Climate change and ongoing water scarcity challenges will sustain long-term demand for efficient irrigation solutions
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Water Scarcity and Efficient Water Management
The MENA region faces chronic water scarcity, making efficient irrigation essential. Drip irrigation systems minimize water loss by delivering water directly to plant roots, helping conserve limited freshwater resources and supporting sustainable agriculture.
Government Initiatives and Subsidies
Governments across MENA are actively promoting drip irrigation through subsidies, favorable policies, and modernization programs. These initiatives lower adoption barriers for farmers and accelerate the shift from traditional irrigation methods to advanced, water-saving technologies.
Technological Advancements in Irrigation
Innovations such as automated control systems, smart sensors, and improved drip emitters are making drip irrigation systems more efficient and user-friendly. These advancements enable precise water management, reduce operational costs, and increase crop yields, driving market growth.
Rising Awareness of Drip Irrigation Benefits
Farmers are increasingly aware of the long-term economic and agronomic benefits of drip irrigation, including higher productivity, reduced water consumption, and improved soil health. This growing awareness is encouraging broader adoption across both large and small-scale farms.
Expansion into Non-Traditional Crops and Precision Agriculture
The adoption of drip irrigation is expanding beyond high-value crops to include cereals and pulses, supported by precision agriculture practices. This diversification, along with the integration of smart technologies, is broadening the market’s reach and impact.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the MENA Drip Irrigation Systems market?
What are the main drivers of the MENA Drip Irrigation Systems market?
Which countries are leading in the adoption of drip irrigation systems in the MENA region?
What are the main challenges faced by the MENA drip irrigation market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Component
- 1.2.1 Drippers
- 1.2.2 Filters
- 1.2.3 Valves
- 1.2.4 Tubing
- 1.2.5 Others
- 1.3 By Application
- 1.3.1 Agriculture
- 1.3.2 Greenhouse
- 1.3.3 Others
- 1.4 By Emitter Type
- 1.4.1 Inline Emitters
- 1.4.2 Online Emitters
- 1.5 By Country (MENA)
- 1.5.1 Saudi Arabia
- 1.5.2 Egypt
- 1.5.3 United Arab Emirates
- 1.5.4 Morocco
- 1.5.5 Other MENA Countries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 306.2 million → 2032: USD 1206.73 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 MENA Drip Irrigation Systems Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 MENA Drip Irrigation Systems Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 MENA Drip Irrigation Systems Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 MENA Drip Irrigation Systems Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 MENA Drip Irrigation Systems Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 MENA Drip Irrigation Systems Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 MENA Drip Irrigation Systems Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 MENA Drip Irrigation Systems Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 306.2 million → 2032: USD 1206.73 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 MENA Drip Irrigation Systems Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Component - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Drippers
- 12.3.7.2 Filters
- 12.3.7.3 Valves
- 12.3.7.4 Tubing
- 12.3.7.5 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Agriculture
- 12.4.7.2 Greenhouse
- 12.4.7.3 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Emitter Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Inline Emitters
- 12.5.7.2 Online Emitters
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Country (MENA) - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Saudi Arabia
- 12.6.7.2 Egypt
- 12.6.7.3 United Arab Emirates
- 12.6.7.4 Morocco
- 12.6.7.5 Other MENA Countries
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 MENA Drip Irrigation Systems End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 MENA Drip Irrigation Systems Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Country-Level Shares, 2024
- 14.2 Country Market Size Comparison, 2024
- 14.3 Country Market Forecasts, 2024-2032
- 14.4 Subregional Industrial and Demand Clusters
- 14.5 Intra-Regional Pricing and Cost Differences
- 14.6 Cross-Border Trade and Supply Networks
- 14.7 Regional Supply and Demand Balances
- 14.8 Country Opportunity Comparison and Prioritization
Note: Every listed country is covered on the structure shown under the first country.
Chapter 15 MENA Drip Irrigation Systems Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 MENA Drip Irrigation Systems Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Netafim
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Jain Irrigation Systems Ltd.
- 18.4 Rivulis Irrigation
- 18.5 Rain Bird Corporation
- 18.6 The Toro Company
- 18.7 Hunter Industries
- 18.8 EPC Industries Ltd.
- 18.9 Antelco Pty Ltd.
- 18.10 Chinadrip Irrigation Equipment Co., Ltd.
- 18.11 IRRITEC S.P.A.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

