
Market Overview
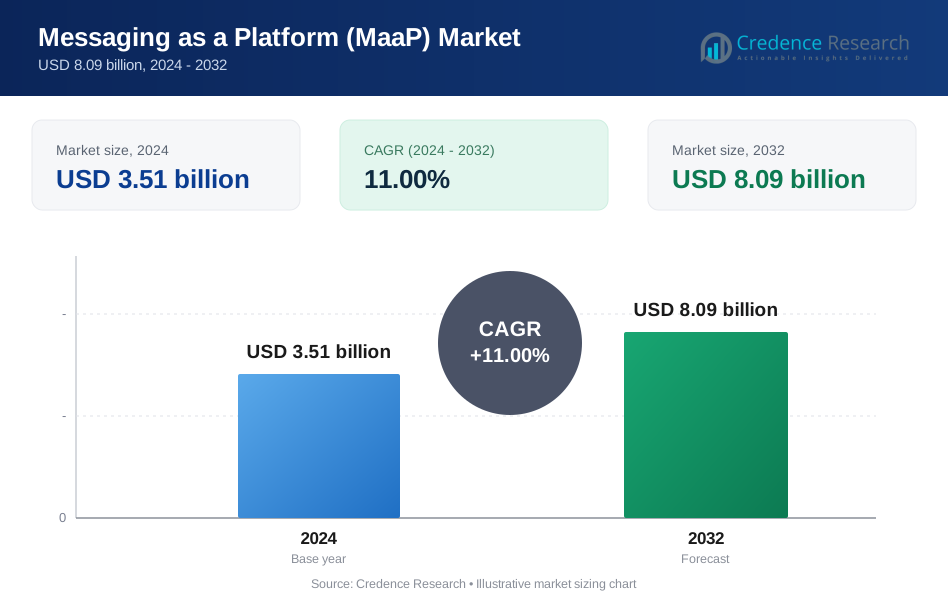
The Messaging-as-a-Platform (MaaP) market was valued at USD 3.51 billion in 2024 and is projected to reach USD 8.09 billion by 2032, growing at a CAGR of 11% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Messaging-as-a-Platform (MaaP) Market Size 2024 | USD 3.51 Billion |
| Messaging-as-a-Platform (MaaP) Market, CAGR | 11% |
| Messaging-as-a-Platform (MaaP) Market Size 2032 | USD 8.09 Billion |
Top players in the Messaging as a Platform (MaaP) market include Google, Twilio Inc., Sinch AB, Infobip Ltd., MessageBird, Tata Communications, Vonage, Orange Business Services, Vodafone Group, and Telefónica S.A. These companies lead the industry by offering scalable omnichannel messaging APIs, advanced RCS capabilities, and AI-driven conversational tools that support automated engagement across mobile ecosystems. North America dominates the market with a 37% share, driven by strong enterprise adoption of cloud communication and OTT business messaging. Europe follows with a 27% share, supported by expanding RCS deployments and strict regulatory frameworks, while Asia Pacific holds a 28% share, fueled by massive OTT usage and rapid digitalization across emerging economies.
Market Insights
- The Messaging as a Platform market reached USD 3.51 billion in 2024 and will reach USD 8.09 billion by 2032 at an 11% CAGR, reflecting strong adoption of mobile-first communication.
- Growth is driven by rising demand for real-time digital engagement, with customer engagement holding a 48% segment share due to high usage of interactive messaging and automated conversational journeys.
- Market trends highlight rapid expansion of OTT and RCS messaging, supported by richer media formats, branded messaging templates, and increasing integration of AI-powered chatbots across customer-facing processes.
- Competition intensifies as key players expand omnichannel APIs, strengthen telecom partnerships, and invest in secure, scalable cloud platforms to support enterprise-grade messaging automation.
- Regionally, North America leads with 37%, followed by Asia Pacific at 28% and Europe at 27%, driven by strong smartphone penetration, rising digital transformation, and growing adoption of MaaP solutions across industries.
Market Segmentation Analysis:
By Component
Platforms lead this segment with a 62% share, driven by rising demand for unified messaging infrastructures that support automation, analytics, and omnichannel communication. Businesses adopt MaaP platforms to manage large-scale interactions, integrate chatbots, and deliver consistent customer experiences across SMS, RCS, and OTT channels. The strong shift toward API-based communication and cloud-native architectures boosts platform adoption, especially among enterprises seeking scalable messaging solutions. Services hold the remaining share, supported by growing needs for integration, customization, and managed communication workflows. Increasing use of AI-powered conversational tools further strengthens the dominance of platform-based deployments.
- For instance, Google's RCS Business Messaging platform handles over 1 billion active Android Messages users and supports verified sender IDs across over 60 countries with more than 90 operator launches, enabling high-volume API-triggered messaging workflows for global enterprises.
By Application
Customer engagement dominates this segment with a 48% share, supported by growing enterprise use of interactive messaging to improve user retention, transaction confirmations, and personalized communication. MaaP enables real-time conversations through chatbots, rich media formats, and automated workflows, which enhance responsiveness and customer satisfaction. Marketing and advertising also show strong traction as brands adopt rich messaging features to deliver promotional campaigns and targeted offers. Customer support applications continue growing due to rising use of AI-driven chatbots that reduce service costs. The shift toward mobile-first user behavior reinforces the leadership of customer engagement applications.
- For instance, Vodafone, along with other carriers, delivers verified business messaging using Rich Communication Services (RCS), which includes advanced features like carousels and action buttons that drive significantly higher engagement rates compared to plain-text SMS.
By Messaging Channel
OTT messaging platforms hold the largest share at 44%, driven by high global usage of WhatsApp, Messenger, and WeChat for business communication. Enterprises prefer OTT channels due to their rich media capabilities, end-to-end encryption, and strong customer reach. RCS gains momentum with enhanced features such as suggested replies, branded messaging, and interactive carousels, strengthening adoption among telecom operators. SMS maintains relevance in regions with limited smartphone penetration or for urgent alerts and transactional messages. In-app messaging grows steadily as businesses integrate chat capabilities directly into digital platforms. The dominance of OTT channels continues due to widespread adoption and superior engagement rates.

Key Growth Drivers
Growing Demand for Rich and Interactive Customer Communication Enterprises adopt MaaP to deliver richer, faster, and more interactive customer communication across mobile channels. Businesses use RCS, OTT platforms, and in-app messaging to enhance engagement with images, carousels, and automated responses. This shift supports higher conversion rates and stronger user retention across retail, BFSI, telecom, and travel industries. Companies also leverage MaaP to reduce reliance on traditional call centers by enabling conversational self-service. As consumers prefer mobile-first interactions, demand for intelligent and interactive messaging capabilities continues to accelerate.
- For instance, Sinch’s messaging infrastructure handles more than 700 billion customer interactions every year across SMS, RCS, WhatsApp, and other OTT channels, and supports enterprise-grade RCS capabilities integrated with over 60 mobile operators.
Rising Adoption of AI-Powered Chatbots and Automation
AI-driven chatbots and automated workflows strengthen MaaP adoption as enterprises seek faster service delivery and 24/7 customer support. Machine learning improves message personalization, intent detection, and automated problem resolution. Organizations integrate MaaP chatbots to reduce operational costs, manage large interaction volumes, and improve response consistency. Automated messaging supports real-time notifications, order updates, and feedback collection. As businesses digitize service processes, AI-based messaging automation becomes a core growth driver across both large enterprises and SMEs.
- For instance, Infobip's platform processed over 450 billion interactions in 2023 across various channels like SMS, chat, and voice, leveraging its AI capabilities to enable enterprise chatbots to deliver automated responses with high precision across global customer bases.
Expansion of Omnichannel Engagement Across Industries
Companies increasingly adopt MaaP to centralize communication across SMS, RCS, OTT platforms, and in-app channels. Omnichannel messaging improves customer satisfaction by ensuring consistent brand experiences and seamless interaction flow. Industries such as healthcare, banking, and e-commerce rely on MaaP to handle authentication, alerts, promotions, and support interactions. Unified dashboards and API-driven orchestration help enterprises manage messaging campaigns at scale. As customer journeys move across multiple digital touchpoints, MaaP becomes essential for integrated engagement strategies.
Key Trends & Opportunities
Growing Shift Toward OTT and RCS Business Messaging
OTT platforms like WhatsApp and Messenger enable high engagement through rich media, verified business accounts, and secure communication, driving rapid MaaP adoption. RCS messaging offers interactive features such as branded templates, suggested replies, and payment integration, opening new revenue streams for operators. Enterprises explore opportunities to replace traditional SMS campaigns with immersive conversational journeys. As telecom providers expand RCS coverage and OTT platforms enhance business APIs, companies gain new avenues for marketing, service, and customer retention.
- For instance, Meta’s WhatsApp Business Platform processes more than 200 million business account interactions per day and supports automated product catalogs with up to 500 items per business, enabling enterprises to deploy large-scale conversational commerce and interactive service journeys.
Expansion of MaaP in SMEs Through Affordable Cloud Solutions
Cloud-based MaaP platforms create strong opportunities for SMEs seeking low-cost communication automation. Easy API integration, pay-as-you-go models, and simplified dashboards help smaller businesses adopt conversational marketing and customer support tools. These capabilities support appointment reminders, order updates, and automated service workflows. SMEs also benefit from AI-driven personalization without heavy infrastructure investments. As cloud adoption increases across developing markets, MaaP penetration in small businesses continues to grow rapidly.
- For instance, Twilio’s cloud messaging platform supports more than 10 million registered developer accounts and handles more than 100 billion annual interactions, enabling SMEs to integrate automated chatbots, reminders, and onboarding flows without deploying local servers or complex infrastructure.
Key Challenges
Data Privacy Concerns and Regulatory Compliance Issues
MaaP adoption faces challenges as companies handle sensitive customer information across multiple messaging channels. Strict data protection laws such as GDPR, HIPAA, and regional telecom regulations increase compliance complexity. Enterprises must ensure data encryption, secure authentication, and safe message routing on all platforms. Non-compliance risks financial penalties and customer trust loss. These concerns slow adoption in sectors with high security requirements, pushing providers to invest in stronger governance frameworks.
Fragmented Messaging Ecosystem and Integration Complexity
The MaaP ecosystem remains fragmented due to varying capabilities across SMS, RCS, OTT, and in-app channels. Businesses face integration challenges when unifying multiple messaging APIs, templates, and compliance standards. Differences in telecom infrastructure, device compatibility, and channel availability create operational complexity. Companies must invest in middleware or specialized platforms to manage omnichannel communication effectively. This fragmentation slows large-scale deployments, especially for enterprises operating across multiple countries.
Regional Analysis
North America
North America holds a 37% share, driven by strong adoption of RCS business messaging, widespread use of OTT platforms, and advanced digital customer engagement strategies. Enterprises across retail, banking, telecom, and healthcare use MaaP to support automated customer service, personalized marketing, and secure transactional messaging. The region benefits from mature telecom infrastructure and high smartphone penetration, enabling rich media messaging at scale. Strong investments in AI-powered chatbots and cloud-based communication APIs further accelerate MaaP adoption. Continuous integration of MaaP solutions with CRM and analytics platforms strengthens regional leadership in omnichannel engagement.
Europe
Europe accounts for a 27% share, supported by high regulatory compliance standards, strong digital transformation initiatives, and growing adoption of RCS across major telecom operators. Enterprises focus on secure customer communication, enhancing demand for encrypted OTT messaging and platform-based automation. Industries such as BFSI, travel, and retail rely on MaaP to improve customer interaction quality and strengthen service consistency. EU-driven privacy laws encourage the use of structured messaging platforms with enhanced control and traceability. Expanding cross-border business communication and rising interest in AI-driven engagement fuel market growth throughout the region.
Asia Pacific
Asia Pacific holds a 28% share, driven by growing smartphone populations, rapid digitalization, and massive use of OTT messaging platforms such as WeChat, WhatsApp, and LINE. Businesses leverage MaaP to support high-volume customer interaction, instant notifications, and promotional campaigns across retail, fintech, and e-commerce sectors. Strong telecom expansion supports RCS adoption, particularly in India, China, South Korea, and Japan. SMEs widely adopt cloud-based MaaP tools to automate customer service and marketing workflows. Increasing mobile-first behavior and rising demand for conversational commerce strengthen long-term regional growth.
Latin America
Latin America holds a 5% share, with demand growing due to strong penetration of OTT platforms and rising interest in mobile-based customer engagement. WhatsApp Business dominates enterprise communication in Brazil and Mexico, enabling rich messaging and automated conversational flows. Businesses adopt MaaP solutions to manage customer support, appointment reminders, and interactive marketing campaigns. Limited RCS deployment slows adoption, but expanding telecom investments are improving access. Growing e-commerce activity and rising demand for affordable cloud communication tools support steady MaaP adoption across the region.
Middle East & Africa
The Middle East & Africa region accounts for a 3% share, driven by increasing digital engagement across banking, telecom, and government services. Strong mobile usage supports the adoption of OTT messaging channels for customer communication, especially in Gulf countries. Organizations deploy MaaP platforms to enhance service automation, reduce call-center load, and deliver real-time alerts. RCS adoption remains gradual but is expanding with ongoing telecom modernization. African markets show rising interest in conversational platforms as digital payments, e-commerce, and online services expand. Growing cloud adoption supports steady market development across the region.
Market Segmentations:
By Component
- Platforms
- Services
By Application
- Customer Engagement
- Marketing & Advertising
- Customer Support & Chatbots
- Others
By Messaging Channel
- SMS
- RCS (Rich Communication Services)
- OTT Messaging Platforms (WhatsApp, Messenger, WeChat)
- In-App Messaging
By Industry Vertical
- BFSI
- Retail & E-commerce
- Healthcare
- Others
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape includes major players such as Google, Twilio Inc., Sinch AB, Infobip Ltd., MessageBird, Tata Communications, Vonage, Orange Business Services, Vodafone Group, and Telefónica S.A. These companies compete by offering advanced MaaP platforms that integrate conversational AI, omnichannel APIs, rich media messaging, and automated customer engagement tools. Leading providers focus on expanding RCS capabilities, strengthening enterprise adoption of OTT business messaging, and enhancing chatbot-driven interactions. Many players invest in AI-powered analytics and cloud-native communication models to deliver personalized and scalable messaging solutions. Strategic partnerships with telecom operators, enterprises, and app developers expand global reach and improve service reliability. Companies also prioritize secure messaging frameworks and regulatory compliance to address rising data privacy concerns. Continuous innovation in conversational commerce, API orchestration, and multi-channel integration strengthens competitiveness in the evolving MaaP ecosystem.
Key Player Analysis
- Twilio Inc.
- Sinch AB
- Infobip Ltd.
- MessageBird
- Tata Communications
- Vonage (Ericsson)
- Orange Business Services
- Vodafone Group
- Telefónica S.A.
Recent Developments
- In July 2025, Infobip Ltd. was named a Leader in the 2025 Gartner, Inc. Magic Quadrant for Communications Platform-as-a-Service, marking its third consecutive year in that position.
- In June 2025, Infobip also became the first global communications platform to launch RCS messaging across all four major U.S. telecom carriers.
- In May 2025, Twilio Inc. unveiled its next-generation customer engagement platform at its SIGNAL conference, emphasising communications, data and AI as a unified infrastructure layer.
Report Coverage
The research report offers an in-depth analysis based on Component, Application, Messaging Channel, Industry Vertical and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Adoption of MaaP will rise as enterprises shift toward mobile-first customer engagement.
- RCS business messaging will expand as telecom operators accelerate global network rollout.
- OTT platforms will strengthen their role in conversational commerce and customer service.
- AI-powered chatbots will handle more interactions, reducing support costs and response times.
- Cloud-based MaaP platforms will gain traction due to easier integration and scalability.
- Personalization will improve as analytics and machine learning enhance message targeting.
- SMEs will adopt MaaP more widely as low-cost API solutions become accessible.
- Security and compliance features will advance to address stricter data-protection regulations.
- Omnichannel orchestration will become essential for seamless cross-platform communication.
- Deeper partnerships between telecom operators and MaaP providers will expand enterprise use cases.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Messaging as a Platform (MaaP) market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Messaging as a Platform (MaaP) market projected to grow between 2025 and 2032?
Which Messaging as a Platform (MaaP) market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Messaging as a Platform (MaaP) market?
Who are the leading companies in the Messaging as a Platform (MaaP) market?
Which region commanded the largest share of the Messaging as a Platform (MaaP) market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Messaging as a Platform (MaaP) Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Messaging as a Platform (MaaP) Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 3.51 billion → 2032: USD 8.09 billion)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Messaging as a Platform (MaaP) Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Messaging as a Platform (MaaP) Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Messaging as a Platform (MaaP) Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Messaging as a Platform (MaaP) Market Drivers
- 3.3 Messaging as a Platform (MaaP) Market Restraints & Challenges
- 3.4 Messaging as a Platform (MaaP) Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Messaging as a Platform (MaaP) Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Messaging as a Platform (MaaP) Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Messaging as a Platform (MaaP) category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Messaging as a Platform (MaaP) Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Messaging as a Platform (MaaP) Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Messaging as a Platform (MaaP) market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Messaging as a Platform (MaaP) Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Messaging as a Platform (MaaP) Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Messaging as a Platform (MaaP) Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Messaging as a Platform (MaaP) (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Messaging as a Platform (MaaP) Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Messaging as a Platform (MaaP) Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Messaging as a Platform (MaaP) Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Messaging as a Platform (MaaP) Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Messaging as a Platform (MaaP) Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Messaging as a Platform (MaaP) Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Messaging as a Platform (MaaP) Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Messaging as a Platform (MaaP) Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Messaging as a Platform (MaaP) Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
