
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
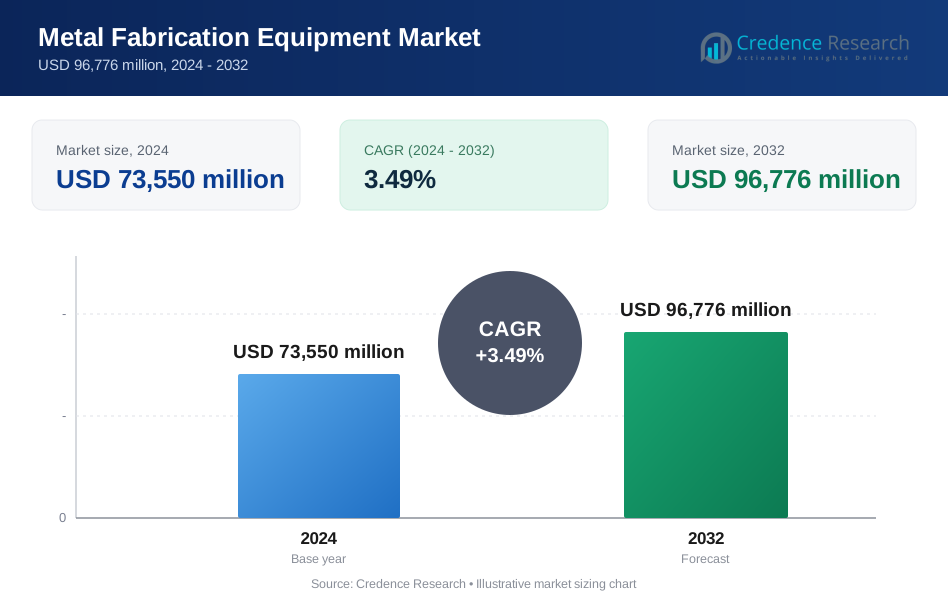
| Metal Fabrication Equipment Market Size 2024 | USD 73,550 million |
| Metal Fabrication Equipment Market, CAGR | 3.49% |
| Metal Fabrication Equipment Market Size 2032 | USD 96,776 million |
Market Overview
The Metal Fabrication Equipment Market is projected to grow from USD 73,550 million in 2024 to USD 96,776 million by 2032, expanding at a CAGR of 3.49%.
The Metal Fabrication Equipment Market growth is driven by increasing demand from automotive, aerospace, construction, and manufacturing industries that require efficient and precise metal processing solutions. Rising adoption of automation and robotics in fabrication processes enhances productivity and reduces labor costs, further fueling market expansion. Advancements in CNC (Computer Numerical Control) technologies improve accuracy and speed, meeting the growing need for customized and complex metal components. Trends include the integration of Industry 4.0 technologies such as IoT and AI, enabling real-time monitoring, predictive maintenance, and enhanced operational efficiency. The shift toward lightweight and high-strength metals in end-use industries promotes demand for advanced equipment capable of handling diverse materials. Growing investments in infrastructure development and renovation projects across emerging economies also support market growth. Manufacturers increasingly focus on developing eco-friendly and energy-efficient equipment to comply with environmental regulations, reflecting sustainability trends in the sector. These factors collectively drive steady growth in the Metal Fabrication Equipment Market through the forecast period.
The Metal Fabrication Equipment Market experiences strong growth across key regions with Asia Pacific leading, holding 38% of the market share due to rapid industrialization and infrastructure development in China, India, and Japan. North America accounts for 27%, supported by advanced automation and a robust manufacturing sector in the U.S. and Canada. Europe holds 21%, driven by precision engineering and sustainable practices. Emerging markets in Latin America and the Middle East & Africa contribute 14%, fueled by infrastructure expansion and industrial investments. Key players such as Amada Co., Ltd., Trumpf Group, Mitsubishi Electric, Bystronic Laser AG, and Lincoln Electric lead through innovation and global reach. Regional companies like BTD Manufacturing and Kapco Metal Stamping also play vital roles by addressing local market needs, enhancing overall industry growth.
Market Insights
- The Metal Fabrication Equipment Market is projected to grow from USD 73,550 million in 2024 to USD 96,776 million by 2032, expanding at a CAGR of 3.49%.
- Growth is driven by rising demand from automotive, aerospace, construction, and manufacturing industries requiring precise and efficient metal processing solutions.
- Automation, robotics, and CNC technologies improve productivity, reduce labor costs, and support customization of complex metal components.
- Integration of Industry 4.0 technologies such as IoT and AI enables real-time monitoring, predictive maintenance, and operational efficiency.
- Asia Pacific leads with 40% market share due to rapid industrialization and infrastructure growth, followed by North America with 30% and Europe with 20%.
- Challenges include high initial investment, maintenance costs, and skilled labor shortages that slow adoption, especially among small and medium enterprises.
- Sustainability trends encourage development of energy-efficient, eco-friendly equipment, aligning market growth with stricter environmental regulations and global green initiatives.
Market Drivers
Rising Demand from Automotive and Aerospace Industries
The Metal Fabrication Equipment Market benefits from strong demand in the automotive and aerospace sectors. These industries require precise and durable metal components for manufacturing vehicles and aircraft. Increasing production volumes and stricter quality standards compel manufacturers to invest in advanced fabrication equipment. It enables faster production cycles, enhanced accuracy, and consistent output. Growing adoption of electric vehicles and lightweight materials further intensifies the need for specialized metal fabrication technologies.
For instance, FANUC CORPORATION supplies advanced robots and CNC machines to the automotive industry, enabling automated welding, painting, and precision machining of vehicle components, which enhances cycle times and productivity for major car manufacturers.
Advancements in Automation and CNC Technologies
Automation and CNC technologies drive significant growth in the Metal Fabrication Equipment Market. Automated systems improve operational efficiency by reducing manual errors and labor costs. CNC machines offer high precision and flexibility, supporting complex designs and customized products. It allows manufacturers to scale production while maintaining quality standards. Integration of robotics accelerates fabrication processes, meeting the rising demand for fast turnaround times in competitive markets.
Infrastructure Development and Industrial Expansion
Infrastructure development in emerging economies fuels the Metal Fabrication Equipment Market. Large-scale construction and industrial projects demand robust metal structures and components. It encourages investment in state-of-the-art fabrication equipment that supports diverse applications across sectors. Industrial expansion and urbanization also increase demand for fabricated metal parts in utilities, transportation, and commercial buildings. This growth creates sustained opportunities for equipment manufacturers to serve expanding markets.
For instance, Piranha’s combination punch plasma machines enabled fabrication shops in Oklahoma, Kansas, Virginia, and Saskatchewan to improve part quality, increase production speeds, and decrease per-part costs, directly supporting large-scale industrial and construction projects.
Focus on Sustainability and Energy Efficiency
Sustainability and energy efficiency trends impact the Metal Fabrication Equipment Market positively. Governments and industries enforce stricter environmental regulations that require eco-friendly manufacturing processes. It prompts the development of equipment with lower energy consumption and reduced waste generation. Manufacturers innovate to offer machines that minimize carbon footprints and enhance resource utilization. This focus on green technology strengthens market growth and aligns with global efforts toward sustainable industrial practices.
Market Trends
Integration of Industry 4.0 Technologies Enhances Operational Efficiency
The Metal Fabrication Equipment Market increasingly incorporates Industry 4.0 technologies such as IoT, AI, and data analytics. These innovations enable real-time monitoring, predictive maintenance, and remote control of fabrication processes. It helps manufacturers optimize machine performance, reduce downtime, and improve product quality. The adoption of smart factories accelerates digital transformation in metal fabrication, supporting agile production and faster response to market demands. This trend reshapes traditional manufacturing toward more connected and efficient operations.
- For instance, John Deere implemented Intel’s AI-powered quality assurance system in its welding lines, enabling real-time defect detection and immediate corrective action, which significantly reduced scrap and rework costs.
Rising Adoption of Robotics and Automation for Precision and Speed
Robotics and automation continue to transform the Metal Fabrication Equipment Market by improving precision and production speed. Automated welding, cutting, and assembly systems reduce manual intervention, minimizing errors and enhancing consistency. It enables manufacturers to handle complex designs and high-volume orders with improved repeatability. The trend toward collaborative robots (cobots) offers flexibility and safety by working alongside human operators. This development supports scalability and cost-effective fabrication in diverse industries.
- For instance, Raymath, a sheet metal manufacturer, deployed four Universal Robots’ cobot welders in 2022, enabling them to manage complex welding tasks with greater repeatability and reduced human error.
Shift Toward Lightweight and Advanced Metal Materials
The Metal Fabrication Equipment Market observes a growing focus on processing lightweight and advanced metals like aluminum alloys, titanium, and composites. These materials provide strength while reducing product weight, critical for automotive, aerospace, and defense applications. It drives demand for specialized equipment capable of handling diverse material properties without compromising precision. The trend supports innovation in fabrication methods to meet evolving requirements for performance and fuel efficiency in end-use sectors.
Increasing Demand for Customization and Small Batch Production
Customization and small batch production gain prominence in the Metal Fabrication Equipment Market due to changing customer preferences. Manufacturers seek flexible equipment that supports rapid design changes and low-volume production runs. It allows businesses to deliver tailored solutions with shorter lead times while controlling costs. This trend encourages adoption of modular machinery and digital design tools that simplify setup and programming. It helps companies address niche markets and increase competitiveness through product differentiation.
Market Challenges Analysis
High Initial Investment and Maintenance Costs Limit Market Penetration
The Metal Fabrication Equipment Market faces challenges due to the high initial investment required for advanced machinery and automation systems. Small and medium-sized enterprises often struggle to afford cutting-edge equipment, limiting their ability to compete with larger manufacturers. It also incurs significant maintenance and operational costs that impact overall profitability. The need for skilled technicians to operate and maintain complex equipment further increases expenses. These factors slow down adoption rates, especially in developing regions with budget constraints.
Skilled Labor Shortage and Technological Complexity Hinder Market Growth
A shortage of skilled labor poses a major challenge for the Metal Fabrication Equipment Market. Operating sophisticated fabrication machinery demands specialized knowledge and technical training. It creates barriers for companies to fully leverage advanced technologies like CNC, robotics, and Industry 4.0 solutions. Rapid technological changes require continuous workforce upskilling, which can be costly and time-consuming. This gap limits productivity gains and affects the efficient utilization of equipment, restraining market expansion.
- For instance, the American Welding Society estimates a shortage of 400,000 welders by 2024, highlighting the urgent need for skilled professionals to operate advanced welding equipment.
Market Opportunities
Expansion in Emerging Economies Drives Market Growth Potential
The Metal Fabrication Equipment Market finds significant opportunities in emerging economies undergoing rapid industrialization and infrastructure development. Growing investments in construction, automotive, and manufacturing sectors create strong demand for advanced metal fabrication solutions. It enables local manufacturers to upgrade production capabilities and meet international quality standards. Increasing government initiatives supporting manufacturing modernization further accelerate market adoption. This growth potential encourages equipment providers to expand their presence and tailor offerings to regional requirements.
Technological Innovation and Customization Enhance Competitive Advantage
Innovation in fabrication technologies presents opportunities for the Metal Fabrication Equipment Market to cater to evolving industry needs. The rise of smart, energy-efficient machines with IoT connectivity allows manufacturers to optimize operations and reduce costs. It opens avenues for offering customized and modular equipment that supports diverse applications and small batch production. Embracing digital tools and automation enables companies to differentiate their products and improve customer satisfaction. This focus on innovation strengthens market positioning and drives long-term growth.
Market Segmentation Analysis:
By Equipment Type
The Metal Fabrication Equipment Market segments by equipment type into cutting, machining, welding, bending, and others. Cutting equipment leads due to its critical role in shaping and sizing metal components with high precision and speed. Machining equipment follows, providing versatility for detailed shaping and finishing processes. Welding equipment maintains strong demand from industries requiring durable metal joints. Bending equipment supports forming applications across sectors. Each equipment type plays a vital role in meeting diverse fabrication needs, driving overall market growth.
By Application
The Metal Fabrication Equipment Market divides by application into job shops, automotive, aerospace and defense, mechanical applications, and others. The automotive sector dominates due to the high volume of metal components required in vehicle manufacturing. Aerospace and defense demand precision fabrication for critical components, supporting steady market expansion. Job shops benefit from flexible and small-batch production capabilities. Mechanical applications cover machinery and industrial equipment manufacturing, contributing significantly to equipment utilization.
By Material
The Metal Fabrication Equipment Market segments by material into steel, aluminium, stainless steel, titanium, and others. Steel remains the most used material due to its strength and cost-effectiveness. Aluminium gains traction for lightweight applications in automotive and aerospace industries. Stainless steel finds extensive use in corrosion-resistant and hygiene-sensitive sectors. Titanium supports high-performance demands with its strength-to-weight ratio. Market demand for specialized equipment grows with the increasing use of diverse metal materials.
Segments:
Based on Equipment Type
- Cutting
- Machining
- Welding
- Bending
- Others
Based on Application
- Job Shops
- Automotive
- Aerospace and Defence
- Mechanical Applications
- Others
Based on Material
- Steel
- Aluminium
- Stainless Steel
- Titanium
- Others
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America holds a significant share of 30% in the Metal Fabrication Equipment Market. It benefits from advanced manufacturing infrastructure and strong demand from automotive, aerospace, and defense industries. The presence of leading equipment manufacturers and early adoption of Industry 4.0 technologies support market growth. It experiences continuous investments in automation and robotics to improve fabrication efficiency. Strict regulatory standards drive the need for precise and high-quality metal components. Expansion in renewable energy and infrastructure projects also contributes to steady equipment demand.
Asia Pacific
Asia Pacific commands the largest market share of 40% in the Metal Fabrication Equipment Market, driven by rapid industrialization and infrastructure development. Countries like China, India, and Japan lead manufacturing activities requiring advanced fabrication solutions. It experiences strong growth in automotive production, electronics, and construction sectors. Government initiatives to modernize manufacturing and increase exports encourage adoption of sophisticated equipment. Rising labor costs motivate automation, further boosting demand. The region’s expanding job shops and small-scale manufacturers also support market expansion.
Europe
Europe accounts for 20% of the Metal Fabrication Equipment Market share, fueled by the automotive and aerospace sectors. It benefits from technological innovation and focus on sustainable manufacturing practices. It leads in adopting energy-efficient and eco-friendly equipment to meet stringent environmental regulations. Industrial modernization programs and investments in smart factories enhance market potential. The region's skilled workforce supports the use of advanced fabrication technologies. Demand for customized metal components in machinery and defense strengthens the market further.
Key Player Analysis
- Watson Engineering Inc.
- STANDARD IRON and WIRE WORKS INC.
- DMG MORI
- R5 Metal Fabricators Inc.
- Kapco Metal Stamping
- Aleris Corporation
- Mayville Engineering Company Inc.
- Matcor-Matsu Group
- Interplex Holdings Pte. Ltd.
- Generation Growth Capital
- BTD Manufacturing
Competitive Analysis
The Metal Fabrication Equipment Market features intense competition among established global players and emerging regional manufacturers. Leading companies focus on product innovation, expanding their portfolios with advanced automation, CNC technologies, and energy-efficient solutions designed to improve productivity and reduce environmental impact. It drives differentiation through enhanced precision, speed, and integration capabilities that address complex fabrication needs. Companies continuously update their equipment to include smart features and connectivity options, increasing operational efficiency. Strategic partnerships, mergers, and acquisitions strengthen market presence and broaden geographic reach, allowing firms to enter new markets rapidly and leverage complementary strengths. Companies invest heavily in research and development to address evolving customer demands and regulatory requirements, ensuring compliance with safety and quality standards. Pricing strategies and after-sales services also play crucial roles in securing client loyalty and expanding market share by providing customized support and maintenance contracts. Emerging players compete by offering cost-effective and customized equipment targeting small and medium enterprises, focusing on niche segments often overlooked by larger firms.
Recent Developments
- In May 2024, J&L Machine and Fabrication expanded its production capacity by $2.1 million in Stanley, N.C., resulting in the creation of 33 new jobs.
- As of May 2025, Watson Engineering Inc. continues to expand its operations with the integration of advanced automation in its metal fabrication processes, including CNC machining, robotic welding, laser cutting, and automated material handling.
- In late November 2024, Milwaukee-based private equity firm Generation Growth Capital acquired three Midwest metal fabricators—Federal Tool & Engineering (Wisconsin), BP Metals (Minnesota), and Rockford Specialties (Illinois)—to form a new manufacturing platform called American Consolidated Metals.
- In May 2025, Aalberts acquired Paulo Heat Treating, Metals Finishing, and Brazing, which operates six facilities across North America. This acquisition strengthens Aalberts’ presence in the automotive, aerospace, defense, and power generation sectors, expanding its market reach within these industries.
Market Concentration & Characteristics
The Metal Fabrication Equipment Market demonstrates a moderately concentrated structure, dominated by several global players alongside numerous regional manufacturers. It features intense competition driven by continuous innovation, product differentiation, and expansion strategies such as mergers and acquisitions. Leading companies invest heavily in research and development to introduce advanced automation, CNC technologies, and energy-efficient solutions that meet evolving industry standards. The market benefits from the presence of established firms with extensive distribution networks and strong customer relationships. Smaller and regional players compete by offering customized and cost-effective equipment tailored to niche segments and local demands. It experiences dynamic shifts due to technological advancements and changing end-user requirements across automotive, aerospace, and construction industries. Pricing strategies and after-sales support play a critical role in maintaining market share and customer loyalty. The Metal Fabrication Equipment Market’s competitive landscape drives ongoing improvements and supports steady growth through innovation and expanding applications.
Report Coverage
The research report offers an in-depth analysis based on Equipment Type, Material, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Metal Fabrication Equipment Market will see increased adoption of automation and robotics to enhance production efficiency.
- Integration of Industry 4.0 technologies will enable smarter, data-driven fabrication processes.
- Manufacturers will focus on developing energy-efficient and eco-friendly equipment to meet environmental regulations.
- Demand for lightweight and high-strength metal processing will rise, driven by automotive and aerospace industries.
- Customized and flexible fabrication solutions will gain importance to address diverse industry needs.
- Emerging economies will experience rapid market growth due to industrialization and infrastructure development.
- Skilled labor shortages will push companies to invest in user-friendly and automated machinery.
- Collaboration between technology providers and manufacturers will accelerate innovation in fabrication equipment.
- Small and medium enterprises will increasingly adopt cost-effective equipment to remain competitive.
- Advancements in CNC and laser cutting technologies will improve precision and reduce production times.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Metal Fabrication Equipment Market?
What factors are driving the growth of the Metal Fabrication Equipment Market?
What are some challenges faced by the Metal Fabrication Equipment Market?
Who are the major players in the Metal Fabrication Equipment Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Metal Fabrication Equipment Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Metal Fabrication Equipment Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 73,550 million → 2032: USD 96,776 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Metal Fabrication Equipment Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Metal Fabrication Equipment Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Metal Fabrication Equipment Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Metal Fabrication Equipment Market Drivers
- 3.3 Metal Fabrication Equipment Market Restraints & Challenges
- 3.4 Metal Fabrication Equipment Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Metal Fabrication Equipment Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Metal Fabrication Equipment Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Metal Fabrication Equipment category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Metal Fabrication Equipment Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Metal Fabrication Equipment Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Metal Fabrication Equipment market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Metal Fabrication Equipment Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Metal Fabrication Equipment Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Metal Fabrication Equipment Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Metal Fabrication Equipment (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Metal Fabrication Equipment Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Metal Fabrication Equipment Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Metal Fabrication Equipment Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Metal Fabrication Equipment Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Metal Fabrication Equipment Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Metal Fabrication Equipment Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Metal Fabrication Equipment Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Metal Fabrication Equipment Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Metal Fabrication Equipment Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
