
Metal Pail Market Overview:
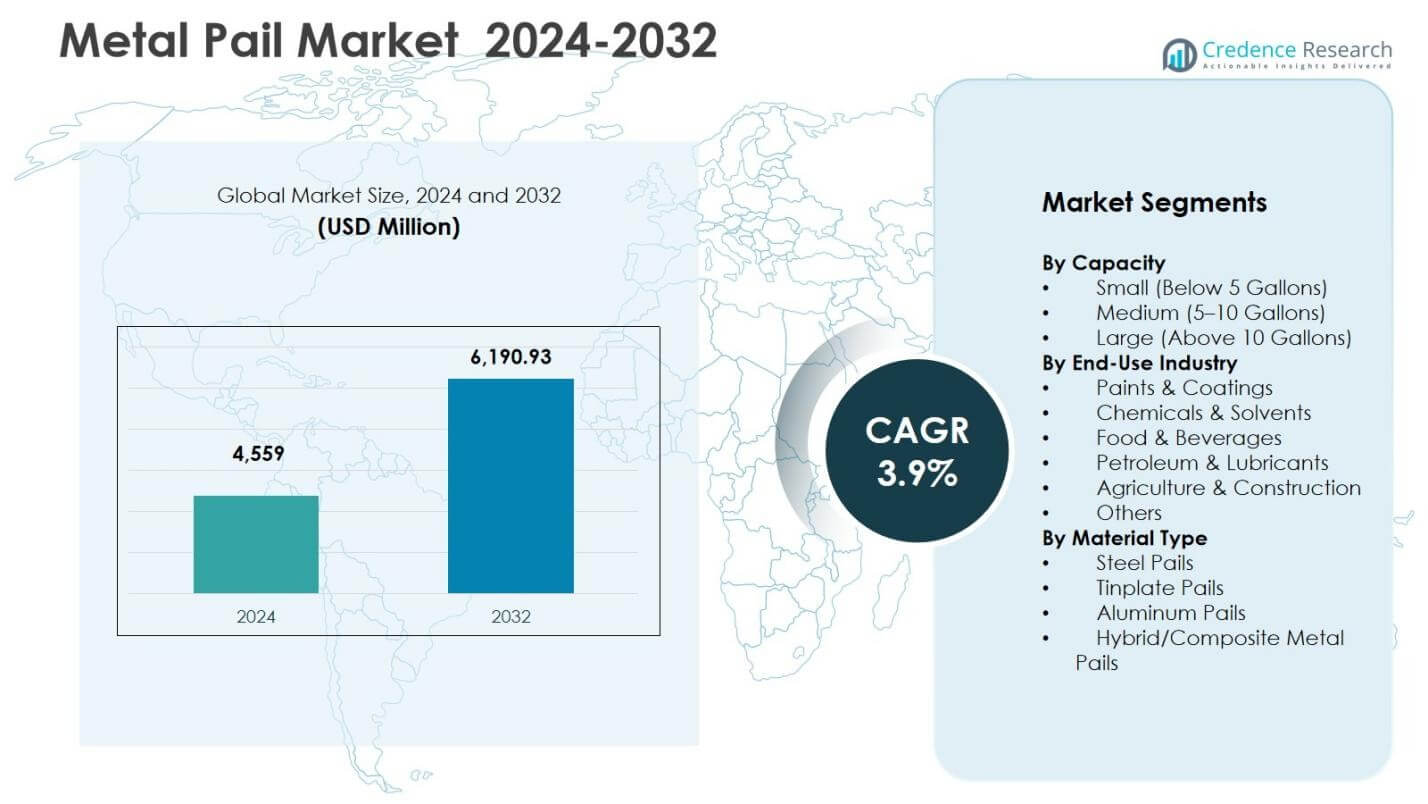
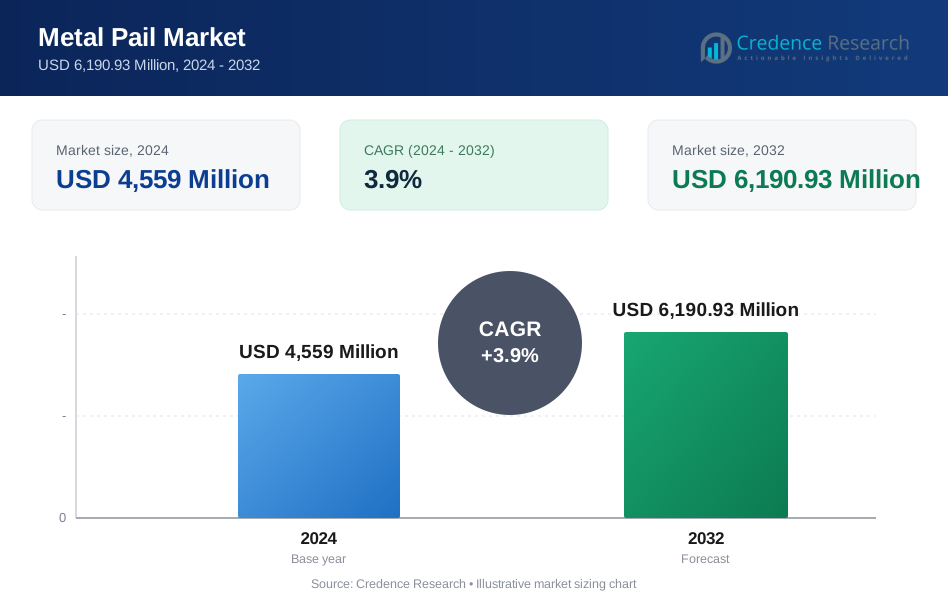
Metal Pail Market size was valued USD 4,559 Million in 2024 and is anticipated to reach USD 6,190.93 Million by 2032, at a CAGR of 3.9% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Metal Pail Market Size 2024 | USD 4,559 million |
| Metal Pail Market, CAGR | 3.9% |
| Metal Pail Market Size 2032 | USD 6,190.93 million |
Metal Pail Market Insights
- Market overview highlights strong adoption of metal pails in paints, coatings, chemicals, lubricants, and food ingredients, with the Medium (5–10 Gallons) capacity segment holding a 46.2% share in 2024 due to balanced storage efficiency and suitability for industrial packaging and automated filling systems.
- Markets driver is fueled by rising demand from industrial and chemical sectors that require durable, compliant, and reusable packaging, along with expanding construction activities and increasing consumption of protective and decorative coatings across manufacturing and infrastructure applications.
- Markets trends indicate growing focus on recyclable and circular metal packaging, lightweight steel and tinplate designs, and product customization, while leading players strengthen product reliability, reconditioning services, and technology upgrades to enhance supply capabilities across end-use industries.
- Regional analysis shows Asia-Pacific leading with 38.6% share in 2024, followed by North America at 24.7% and Europe at 22.3%, while Latin America and Middle East & Africa expand steadily through industrialization and coatings-driven demand.
Metal Pail Market Segmentation Analysis:
By Capacity
In the Metal Pail Market, the Medium (5–10 Gallons) segment held the dominant position with a 46.2% share in 2024, driven by its widespread use in paints, coatings, chemicals, and lubricants where balanced storage capacity and handling efficiency are essential. This segment benefits from strong adoption in industrial packaging, regulatory suitability for hazardous material transport, and compatibility with automated filling systems. The Small (Below 5 Gallons) segment accounted for 31.5% share, supported by demand in retail packaging and consumer goods, while the Large (Above 10 Gallons) segment captured 22.3% share, led by bulk material storage in agriculture and construction.
- For instance, BASCO’s UN-rated 5-gallon open-head steel pail with lever-lock closure is designed to meet DOT/49 CFR hazardous liquid requirements, making it suitable for chemicals and coatings that need compliant medium-capacity packaging.
By End-Use Industry
The Paints & Coatings segment emerged as the leading end-use category in the Metal Pail Market with a 34.7% share in 2024, driven by expanding infrastructure development, rising protective coating demand, and strong consumption in automotive and industrial finishing applications. The Chemicals & Solvents segment represented 27.9% share, supported by stringent safety-compliant metal packaging requirements, while Food & Beverages accounted for 15.6% share, primarily in edible oil and ingredient storage. Petroleum & Lubricants captured 12.4% share, and Agriculture & Construction represented 6.8% share, with the Others category holding 2.6% share across specialty and niche uses.
- For instance, AkzoNobel and Nippon Paint Holdings have ramped up demand for durable steel pails to supply corrosion-resistant coatings used in construction and industrial maintenance sectors.
By Material Type
Within the material category, Steel Pails dominated the Metal Pail Market with a 58.3% share in 2024, owing to their superior strength, corrosion resistance, recyclability, and suitability for hazardous and industrial liquid packaging. Tinplate Pails followed with a 21.4% share, supported by demand in food, adhesives, and specialty chemicals requiring protective lining properties. Aluminum Pails accounted for 12.6% share, driven by lightweight handling and premium industrial applications, while Hybrid/Composite Metal Pails represented 7.7% share, gaining traction in applications seeking durability with reduced weight and enhanced performance characteristics.
Key Growth Drivers
Rising Demand from Industrial and Chemical Packaging
The Metal Pail Market is experiencing strong growth due to increasing demand from industrial and chemical sectors that require durable, compliant, and secure packaging for hazardous and high-value materials. Metal pails offer superior structural strength, leak resistance, and compatibility with solvents, coatings, lubricants, and adhesives, making them preferred over plastic alternatives in regulated environments. Growth in manufacturing, petrochemicals, and specialty chemicals further strengthens consumption, supported by global expansion in infrastructure, automotive refinishing, and protective coatings. The need for UN-certified, tamper-resistant, and reusable packaging solutions continues to reinforce the commercial relevance of metal pails across industrial supply chains.
- For instance, Berlin Packaging offers 5-gallon epoxy-lined UN-rated open-head steel pails that are specified for a wide range of non-food liquids and semi-solids, including industrial chemicals, lubricants, and coatings, where the lining protects against corrosion and product interaction while maintaining structural integrity during storage and transport.
Expansion of Paints, Coatings, and Construction Activities
Accelerating construction and infrastructure development across emerging and developed economies remains a major driver for the Metal Pail Market, particularly through the paints and coatings industry. Metal pails are widely used for decorative paints, industrial coatings, sealants, and waterproofing products due to their durability, stacking ability, and compatibility with viscous materials. Growth in residential renovation, commercial building projects, and protective anticorrosion coatings in heavy industry further boosts consumption. Additionally, the increasing adoption of water-based and specialty coatings for sustainability compliance continues to strengthen the demand for metallic packaging formats that support product integrity and transportation safety.
- For instance, Emballator Metal Group partnered with Henkel Adhesive Technologies to adopt phthalate-free Darex COV 73 sealant for pail lids in 2024. Applied via nozzle on tinplate, it ensures low permeability, chemical resistance, and secure sealing for paints and sealants without CMR ingredients.
Sustainability, Recyclability, and Circular Packaging Adoption
Sustainability initiatives and a growing shift toward recyclable and reusable packaging are significantly supporting market growth for metal pails. Steel and tinplate pails offer high recyclability rates, long service life, and compatibility with circular economy objectives, positioning them as environmentally responsible alternatives to single-use plastic containers. Governments and industry stakeholders increasingly encourage metal-based packaging for waste reduction and emissions control. Industrial end users also favor metal pails for reconditioning and reuse programs, reducing lifecycle costs and environmental impact. This alignment with ESG commitments and resource-efficient packaging strategies continues to expand market adoption across key application segments.
Key Trends and Opportunities
Adoption of Lightweight and Hybrid Metal Pail Designs
A major market trend is the development of lightweight, performance-optimized, and hybrid metal pail structures designed to reduce transportation costs and improve handling efficiency without compromising strength. Manufacturers are introducing thinner-gauge metal bodies, reinforced rims, and advanced coatings to enhance corrosion resistance and interior product compatibility. Opportunities are emerging in composite metal-plastic hybrid pails that balance durability with reduced weight, supporting logistics optimization. Growth in automated filling lines and industrial productivity requirements is further accelerating demand for ergonomically engineered pails, creating avenues for innovation in closure systems, stacking stability, and tamper-evident packaging formats.
- For instance, Pipeline Packaging's 1-gallon hybrid paint can (610 x 713 size) merges metal and plastic for lighter weight, ideal for water-based products while maintaining strength. This supports ergonomic handling and logistics optimization.
Growth Opportunities in Food, Lubricants, and Specialty Product Packaging
Expanding applications in food ingredients, edible oils, lubricants, adhesives, and specialty materials are creating new revenue opportunities in the Metal Pail Market. Metal pails provide excellent barrier properties, flavor and chemical stability, and compliance with hygiene and transport standards, making them well-suited for premium and industrial-grade packaging. Demand is rising in sectors requiring secure storage under varying temperature and environmental conditions. Increasing focus on brand differentiation and product safety is also encouraging adoption of lithographed, coated, and decorative metal pails, supporting value-added packaging opportunities across emerging consumer-industrial product categories.
- For instance, L. Smith supplies steel pails specifically for packaging edible oils, providing robust protection against leaks and environmental factors in industrial shipping. Their pails meet standards for safe transport of oils alongside other liquids.
Key Challenges
Competition from Plastic and Alternative Packaging Materials
One of the major challenges in the Metal Pail Market is increasing competition from plastic containers, composite drums, and flexible packaging formats that offer lower production costs and lighter weight. In applications where chemical compatibility and regulatory constraints are less stringent, plastic pails can replace metal formats, particularly in cost-sensitive markets. Rising resin innovations such as high-density polyethylene alternatives also pressure metal pail adoption. To address this challenge, manufacturers must emphasize durability, reusability, recyclability, and performance reliability to retain market relevance and differentiate metal pails in segments where safety and rigidity remain critical.
Volatility in Raw Material Prices and Manufacturing Costs
Fluctuations in steel, tinplate, and aluminum prices pose a significant challenge to the Metal Pail Market by directly impacting production costs and profit margins. Global supply chain disruptions, energy costs, and geopolitical factors can influence raw material availability and lead times, affecting pricing stability for both manufacturers and end users. High capital investment requirements in forming, coating, and welding technologies further intensify cost pressures. These factors may encourage customers to shift toward lower-cost packaging alternatives. To mitigate this risk, market participants increasingly focus on supply optimization, recycled material integration, and lean manufacturing strategies.
Regional Analysis
Asia-Pacific
Asia-Pacific held the largest share of the Metal Pail Market with 38.6% share in 2024, driven by strong industrial manufacturing, paints and coatings demand, and rapid infrastructure development across China, India, and Southeast Asia. Expanding chemical processing, lubricants packaging, and food-grade metal container applications further strengthen market adoption. The region benefits from cost-efficient metal fabrication, high production capacity, and growing export-oriented packaging industries. Rising investments in construction, automotive refinishing, and protective coating activities continue to accelerate consumption, while sustainability initiatives and increasing use of reusable industrial packaging support long-term growth momentum across regional end-use sectors.
North America
North America accounted for 24.7% share in 2024 in the Metal Pail Market, supported by mature demand across chemicals, solvents, petroleum lubricants, and industrial coatings sectors where regulatory-compliant and UN-certified packaging remains essential. The region is characterized by strong adoption of recyclable steel pails, reconditioning programs, and circular packaging initiatives driven by environmental standards. Growth in residential renovation, infrastructure maintenance, and specialty coatings further contributes to consumption. Advanced manufacturing, automation in filling operations, and premium-grade packaging requirements in chemical and adhesive applications reinforce ongoing demand for high-performance metal pails across the United States and Canada.
Europe
Europe represented 22.3% share in 2024, driven by stringent packaging safety regulations, environmental compliance frameworks, and widespread adoption of recyclable metal containers in industrial and specialty product applications. The region experiences consistent demand from paints and surface protection coatings, automotive refinishing, agricultural chemicals, and lubricants segments. Strong presence of metal packaging manufacturers, technological upgrades in coating and corrosion-protection processes, and increasing focus on sustainable and reusable packaging solutions enhance market growth. Industrial refurbishment, infrastructure retrofitting, and expansion in building maintenance activities across Western and Central Europe further support the continued consumption of metal pails.
Latin America
Latin America captured 8.1% share in 2024 in the Metal Pail Market, supported by increasing demand from construction activities, agricultural chemicals, lubricants, and paints and coatings applications across Brazil, Mexico, and Argentina. Growth in industrial production, expanding food-processing sectors, and improved distribution networks are contributing to steady adoption. Rising infrastructure investments and refurbishment projects generate additional consumption in protective and decorative coating segments. While cost-sensitive markets encourage material substitution, the durability, reusability, and regulatory suitability of metal pails continue to strengthen their relevance in industrial packaging, particularly in chemicals, solvents, and petroleum-related product categories.
Middle East & Africa
The Middle East & Africa region accounted for 6.3% share in 2024, driven by increasing demand from oil and gas lubricants packaging, construction materials, industrial coatings, and chemicals distribution sectors. Large-scale infrastructure development, urban expansion, and industrial modernization programs across GCC economies and parts of Africa support consumption growth. Metal pails remain preferred in segments requiring robust containment, heat resistance, and secure transport conditions. The market is further supported by rising adoption of corrosion-resistant containers, growth in industrial maintenance coatings, and strengthening trade activity, which collectively enhance the demand outlook for metal pails in regional industrial supply chains.
Metal Pail Market Segmentations:
By Capacity
- Small (Below 5 Gallons)
- Medium (5–10 Gallons)
- Large (Above 10 Gallons)
By End-Use Industry
- Paints & Coatings
- Chemicals & Solvents
- Food & Beverages
- Petroleum & Lubricants
- Agriculture & Construction
- Others
By Material Type
- Steel Pails
- Tinplate Pails
- Aluminum Pails
- Hybrid/Composite Metal Pails
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
Competitive landscape in the Metal Pail Market features leading manufacturers such as Mauser Packaging Solutions, Greif Inc., Berlin Packaging, Cleveland Steel Container Corporation, Behrens Manufacturing LLC, CL Smith LLC, Lancaster Container Inc., Industrial Packaging, P. Wilkinson Containers Ltd., and TANKS INTERNATIONAL SRL. The market is characterized by strong emphasis on product quality, regulatory compliance, recyclability, and performance reliability, particularly for industrial, chemical, and coatings applications where safety and durability standards are critical. Players focus on capacity expansion, metal reconditioning services, and lightweight pail innovations to enhance logistics efficiency and sustainability alignment. Strategic initiatives include technology upgrades in coating and corrosion-resistant finishes, investments in automation and UN-certified packaging formats, and partnerships with end-use industries to strengthen supply chain integration. Increasing demand for circular packaging solutions and reusable metal containers continues to shape competitive positioning, encouraging manufacturers to differentiate on cost efficiency, product customization, and environmentally responsible packaging capabilities across global and regional markets.
Key Player Analysis
- Mauser Packaging Solutions
- CL Smith LLC
- P. Wilkinson Containers Ltd.
- TANKS INTERNATIONAL SRL
- Behrens Manufacturing LLC
- Industrial Packaging
- Lancaster Container Inc.
- Cleveland Steel Container Corporation
- Berlin Packaging
- Greif Inc.
Recent Developments
- In December 2025, Mauser Packaging Solutions acquired Siena Plastics LLC, strengthening its portfolio and reinforcing its market presence in plastic and metal pail solutions.
- In October 2024, Cleveland Steel Container (CSC) formally acquired Lancaster Container, Inc., a steel pail manufacturer with over 60 years of expertise.
- In November 2023, Mauser Packaging Solutions announced an agreement to acquire Taenza, S.A. de C.V., a Mexico-based producer of steel pails and tin-steel aerosol cans.
Report Coverage
The research report offers an in-depth analysis based on Capacity, End Use Industry, Material Type and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will witness steady growth as demand from industrial, chemical, and coatings applications continues to expand.
- Manufacturers will increasingly focus on recyclable, reusable, and circular packaging solutions to align with sustainability goals.
- Adoption of lightweight and hybrid metal pail designs will rise as industries seek improved handling efficiency and cost optimization.
- Automation in manufacturing and filling processes will strengthen the demand for precision-engineered and durable metal pails.
- Growth in infrastructure, construction, and maintenance activities will continue to support consumption across paints and protective coatings.
- The market will see wider use of corrosion-resistant coatings and advanced metal finishes to enhance product performance.
- Value-added packaging, including customized printing and branding on metal pails, will gain greater adoption in premium segments.
- Emerging economies will contribute significantly to future demand through expanding industrialization and packaging modernization.
- Partnerships between manufacturers and end-use industries will increase to support supply stability and product innovation.
- Competitive differentiation will rely on cost efficiency, sustainability leadership, and enhanced material engineering capabilities.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Metal Pail Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Metal Pail Market projected to grow between 2024 and 2032?
Which Metal Pail Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Metal Pail Market?
Who are the leading companies in the Metal Pail Market?
Which region commanded the largest share of the Metal Pail Market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Metal Pail Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Metal Pail Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 4,559 Million → 2032: USD 6,190.93 Million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Metal Pail Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Metal Pail Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Metal Pail Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Metal Pail Market Drivers
- 3.3 Metal Pail Market Restraints & Challenges
- 3.4 Metal Pail Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Metal Pail Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Metal Pail Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Metal Pail category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Metal Pail Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Metal Pail Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Metal Pail market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Metal Pail Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Metal Pail Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Metal Pail Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Metal Pail (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Metal Pail Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Metal Pail Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Metal Pail Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Metal Pail Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Metal Pail Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Metal Pail Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Metal Pail Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Metal Pail Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Metal Pail Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
