
Market Overview:
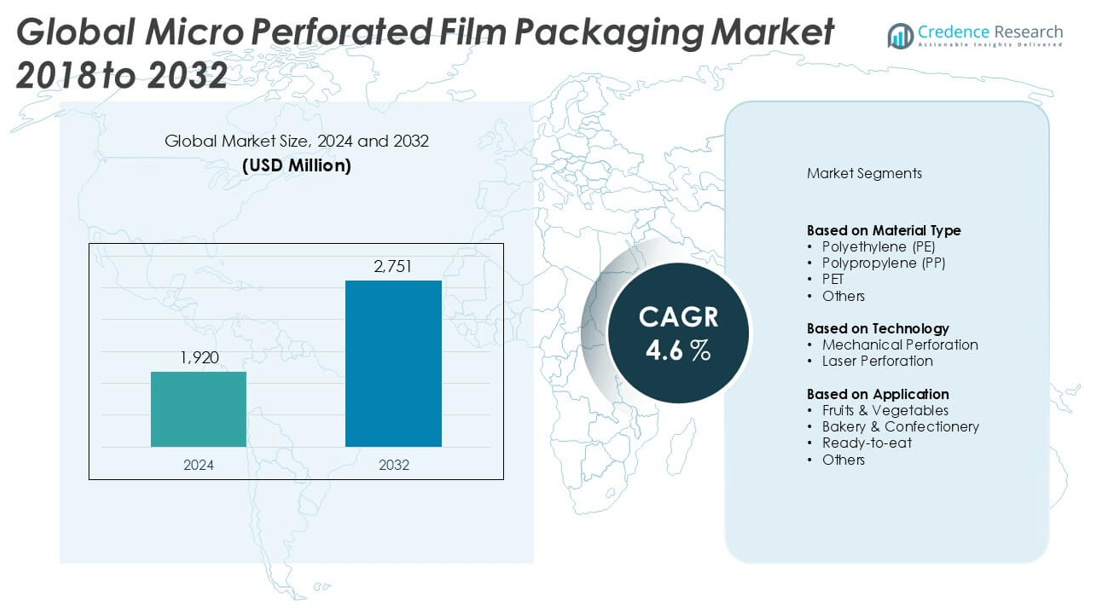
The Micro Perforated Film Packaging market size was valued at USD 1,920 million in 2024 and is anticipated to reach USD 2,751 million by 2032, at a CAGR of 4.6% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Micro Perforated Film Packaging Market Size 2024 | USD 1,920 million |
| Micro Perforated Film Packaging Market, CAGR | 4.6% |
| Micro Perforated Film Packaging Market Size 2032 | USD 2,751 million |
The Micro Perforated Film Packaging market is led by key players such as Amcor Limited, Sealed Air Corporation, Mondi Group, Coveris Holdings S.A., and Uflex Ltd., all of which hold strong positions due to their global presence, advanced technological capabilities, and broad product offerings. These companies prioritize innovation in sustainable materials and precision perforation techniques to meet the rising demand for extended shelf-life and eco-friendly packaging. Asia-Pacific dominates the global market, accounting for approximately 32% of total market share in 2024, driven by expanding retail infrastructure, increasing consumption of fresh and ready-to-eat foods, and growing investments in food packaging technologies.
Market Insights
- The Micro Perforated Film Packaging market was valued at USD 1,920 million in 2024 and is projected to reach USD 2,751 million by 2032, growing at a CAGR of 4.6% during the forecast period.
- Rising demand for fresh produce and minimally processed foods is driving adoption of breathable packaging that extends shelf life while maintaining product quality.
- Technological advancements in laser and mechanical perforation, along with the growing preference for recyclable and biodegradable materials, are key market trends influencing product development.
- The market is moderately fragmented, with leading players including Amcor Limited, Sealed Air Corporation, Mondi Group, and Uflex Ltd. competing through innovation, strategic partnerships, and regional expansions.
- Asia-Pacific leads the market with a 32% share, followed by North America at 28% and Europe at 26%; by application, the Fruits & Vegetables segment holds the largest share due to high demand for extended shelf-life packaging solutions.
Market Segmentation Analysis:
By Material Type
Polyethylene (PE) dominated the Micro Perforated Film Packaging market in 2024, accounting for the largest market share among material types. Its widespread use is attributed to its cost-effectiveness, flexibility, and excellent moisture barrier properties, which make it ideal for perishable food packaging. PE is particularly favored in fresh produce packaging where extended shelf life and breathability are essential. Additionally, the growing demand for lightweight and recyclable packaging materials further supports the dominance of PE. While Polypropylene (PP) and PET are also gaining traction due to their clarity and strength, PE remains the material of choice for most manufacturers.
- For instance, Amcor Limited developed its PE-based AmLite Ultra Recyclable film, which offers oxygen transmission rates below 0.2 cc/m²/day, significantly enhancing produce shelf life while meeting recyclability standards.
By Technology
Mechanical perforation held the leading market share in 2024, outperforming laser perforation in terms of volume and affordability. This method is widely adopted due to its ease of integration into existing production lines and its cost-effectiveness for high-volume packaging applications. Mechanical perforation is especially popular among manufacturers of fruit and vegetable packaging, where consistent airflow and rapid processing are required. However, laser perforation is gaining attention in premium and ready-to-eat food segments for its precision and ability to create micro holes without compromising film integrity. Still, the mechanical perforation segment continues to lead due to its economic viability and scalability.
- For instance, Mondi Group's mechanical perforation systems can process film rolls at speeds of over 600 meters per minute, allowing for large-scale packaging operations without compromising hole consistency.
By Application
Fruits & Vegetables emerged as the dominant application segment in the Micro Perforated Film Packaging market, capturing the highest market share in 2024. This dominance is driven by the increasing global demand for fresh produce and the need for packaging that maintains freshness by regulating gas exchange and moisture levels. Micro perforated films help reduce spoilage and extend shelf life, making them essential for retail and export packaging of fruits and vegetables. The bakery & confectionery and ready-to-eat segments are also growing steadily, driven by changing lifestyles and the rising popularity of convenience foods, but remain secondary to the fresh produce segment.
Market Overview
Rising Demand for Fresh and Minimally Processed Foods
The increasing consumer preference for fresh, minimally processed food is a key driver for the micro perforated film packaging market. These films enhance product shelf life by enabling controlled respiration in perishable items such as fruits, vegetables, and bakery goods. As global consumption of fresh produce rises-especially in urban areas-retailers and food manufacturers are adopting breathable packaging solutions to reduce spoilage and maintain quality. This shift in dietary trends continues to create consistent demand for advanced packaging technologies that preserve freshness without relying heavily on preservatives.
- For instance, Sealed Air Corporation’s Cryovac Freshness Plus range demonstrated a reduction in mold growth by up to 34 days in trials with fresh berries, supporting longer retail shelf life with minimal processing.
Expansion of Organized Retail and E-commerce
The rapid growth of organized retail chains and e-commerce platforms is significantly contributing to market expansion. These channels require reliable packaging solutions that ensure product integrity during storage and transit. Micro perforated films meet this requirement by offering durability and extended freshness, particularly for temperature-sensitive items. Additionally, the proliferation of online grocery and meal delivery services is increasing the need for effective packaging that balances shelf life with visual appeal. This trend is especially strong in emerging economies where modern retail infrastructure is expanding rapidly.
- For instance, Uflex Ltd. supplies perforated films for BigBasket in India, supporting fulfillment of over 60,000 daily fresh food deliveries with consistent thermal and respiratory performance.
Sustainability and Regulatory Push for Eco-friendly Packaging
Sustainability concerns and evolving regulatory standards are driving the shift toward recyclable and environmentally friendly packaging materials. Micro perforated films, especially those made from biodegradable or recyclable polymers, are gaining traction as brands strive to reduce plastic waste and carbon footprints. Government policies promoting sustainable packaging practices and consumer demand for green alternatives are compelling manufacturers to invest in innovative materials and perforation technologies. These factors are accelerating adoption across multiple industries, particularly in food packaging, where both performance and environmental compliance are critical.
Key Trends & Opportunities
Technological Advancements in Perforation Techniques
Advancements in laser and mechanical perforation technologies are enabling precise control over hole size, density, and distribution in micro perforated films. These innovations improve packaging performance by optimizing airflow and moisture control, thereby extending product shelf life. The growing availability of high-speed and automated perforation systems is also improving manufacturing efficiency and scalability. This trend opens opportunities for companies to offer customized packaging solutions tailored to specific food types and storage conditions, giving them a competitive edge in a highly fragmented market.
- For instance, Bolloré Group’s laser perforation units achieve micro-hole diameters as small as 50 microns with positioning accuracy of ±5 microns, allowing tailored solutions for respiration-sensitive food categories.
Increasing Adoption in Emerging Economies
Emerging markets in Asia-Pacific and Latin America are witnessing increased adoption of micro perforated film packaging, driven by growing middle-class populations, urbanization, and shifts in food consumption patterns. Rising demand for packaged and ready-to-eat foods, combined with the expansion of cold chain logistics and retail infrastructure, is creating new growth avenues. Local manufacturers are increasingly investing in advanced packaging solutions to meet the rising standards of food safety and freshness. This trend presents a strategic opportunity for global players to expand their presence and form partnerships in these high-potential regions.
- For instance, Avery Dennison’s Performance Tapes division supported over 100 packaging lines in Brazil and India in 2023 by installing localized micro perforation units with throughput capacities of 4 million meters of film per month.
Key Challenges
High Cost of Advanced Materials and Perforation Equipment
One of the primary challenges facing the market is the high cost associated with premium materials and advanced perforation equipment, particularly laser systems. Small and medium-sized manufacturers may find it difficult to invest in such capital-intensive technologies, limiting their competitiveness. Additionally, the use of biodegradable or specialty films further increases production costs, potentially affecting product pricing. This financial barrier can restrict market penetration in cost-sensitive regions, despite the rising demand for high-performance and sustainable packaging.
Complexity in Achieving Optimal Breathability
Achieving the right balance between breathability and barrier protection is technically challenging in micro perforated film packaging. Different food products require customized oxygen and moisture transmission rates, and failure to optimize these parameters can lead to reduced shelf life or product spoilage. This complexity demands in-depth knowledge of food science, product-specific respiration rates, and environmental factors, which not all manufacturers possess. As a result, improper application or design flaws can lead to compromised product quality and customer dissatisfaction.
Regulatory Compliance and Recycling Limitations
While demand for sustainable packaging is growing, regulatory compliance remains a major challenge, especially in regions with strict packaging and environmental laws. Many micro perforated films, particularly multilayered or composite ones, pose difficulties in recycling due to their mixed-material composition. This limits their suitability for circular economy initiatives and increases scrutiny from environmental agencies. Manufacturers must continuously adapt to evolving regulations, which can involve additional R&D investment and reformulation of existing product lines to remain compliant and competitive.
Regional Analysis
North America
North America held a significant share of the micro perforated film packaging market in 2024, accounting for approximately 28% of global revenue. The region’s dominance stems from strong demand for packaged fresh produce, baked goods, and convenience foods. The presence of established retail chains and e-commerce platforms further drives the need for effective, shelf-life-extending packaging solutions. Additionally, stringent food safety regulations encourage the adoption of high-performance materials and advanced perforation technologies. The United States remains the primary contributor due to its advanced packaging infrastructure and growing emphasis on sustainable packaging alternatives.
Europe
Europe accounted for nearly 26% of the global micro perforated film packaging market in 2024, supported by its mature food packaging sector and heightened environmental regulations. Countries such as Germany, France, and the U.K. are driving demand, particularly for sustainable and recyclable films used in fresh produce and bakery packaging. The European Union's push for circular economy practices has spurred investment in biodegradable materials and eco-friendly perforation technologies. Moreover, increasing health awareness and preference for fresh food products are boosting market growth across both Western and Eastern Europe, reinforcing the region’s position as a major consumer of breathable packaging solutions.
Asia-Pacific
Asia-Pacific led the micro perforated film packaging market with the largest share of approximately 32% in 2024, driven by rising demand for packaged fruits, vegetables, and ready-to-eat meals across emerging economies. Rapid urbanization, population growth, and expanding retail and cold chain infrastructure have fueled adoption in countries like China, India, and Indonesia. Local manufacturers are increasingly investing in affordable and scalable packaging technologies to meet domestic consumption and export demands. Moreover, government initiatives promoting food safety and hygiene continue to support the adoption of high-performance packaging, establishing the region as a key growth engine for the global market.
Latin America
Latin America captured around 8% of the global micro perforated film packaging market in 2024, with Brazil and Mexico being the dominant contributors. The market is primarily driven by the growing consumption of fresh produce and bakery items, along with expanding food processing industries. Improvements in retail infrastructure and increased exports of fruits and vegetables are encouraging local manufacturers to adopt breathable packaging solutions. However, market penetration remains moderate due to limited access to advanced perforation technologies and cost constraints, presenting opportunities for foreign investments and technological collaborations to address existing gaps.
Middle East & Africa (MEA)
The Middle East & Africa accounted for nearly 6% of the global micro perforated film packaging market in 2024. Although relatively smaller in size, the region is experiencing steady growth driven by rising demand for packaged food, growing retail expansion, and increasing import of fresh produce. Countries like the UAE and South Africa are witnessing a shift toward quality packaging solutions to meet international food safety standards. However, limited manufacturing capabilities and high dependency on imports restrict large-scale adoption. Nevertheless, the growing middle-class population and rising health consciousness provide long-term growth potential in the region.
Market Segmentations:
By Material Type
- Polyethylene (PE)
- Polypropylene (PP)
- PET
- Others
By Technology
- Mechanical Perforation
- Laser Perforation
By Application
- Fruits & Vegetables
- Bakery & Confectionery
- Ready-to-eat
- Others
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the Micro Perforated Film Packaging market is characterized by the presence of both global packaging giants and specialized regional players. Companies such as Amcor Limited, Sealed Air Corporation, Mondi Group, and Coveris Holdings S.A. lead the market with extensive product portfolios, strong R&D capabilities, and global distribution networks. These firms focus on innovation in film materials and perforation technologies to meet evolving consumer and regulatory demands, particularly for sustainable and high-performance packaging. Meanwhile, regional players like Uflex Ltd., TCL Packaging Ltd., and Now Plastics Inc. cater to niche segments and offer customized solutions at competitive prices. Strategic initiatives including mergers, acquisitions, capacity expansions, and collaborations are commonly employed to enhance market share and technological capabilities. Additionally, growing investments in biodegradable films and precision laser perforation techniques highlight the industry's shift toward sustainability and efficiency. The competitive environment remains dynamic, driven by continuous innovation and evolving customer preferences.
Key Player Analysis
- Amcor Limited
- Sealed Air Corporation
- Mondi Group
- Coveris Holdings S.A.
- Uflex Ltd.
- Bolloré Group
- TCL Packaging Ltd.
- Avery Dennison Corporation
- Amerplast
- Now Plastics Inc.
Recent Developments
- In May 2025, Sealed Air Corporation reported strong Q1 2025 financial results, highlighting steady volume growth in its food packaging segment. The company also achieved improved margins through strategic cost control measures, reflecting progress in its ongoing business transformation and operational efficiency initiatives.
- In April 2025, Amcor finalized its acquisition of Berry Global, forming one of the largest packaging conglomerates worldwide. The merger significantly enhances Amcor’s R&D capabilities and broadens its geographic footprint. This consolidation is expected to streamline operations and accelerate innovation in micro-perforated film technologies, particularly for applications in fresh produce and breathable packaging solutions.
- In August 2024, Specialty Polyfilms announced that they would participate in the Global Produce and Floral Show held in Atlanta, GA. Specialty Polyfilms is a team member of the International Fresh Produce Association, and it welcomes all Fresh Produce and Foodservice industry stakeholders to visit its booth C1501 in the business solution sections. Team members will demonstrate the distinguished attributes of Forvara Foodservice Films, Forvara Cheese Wrapping Films, Forvara Mushroom Films, and Forvara Fresh Produce Films from October 17-19, 2024. Forvara Mushroom Films is available in boreholes and micro-perforated options and helps to improve the shelf life of mushrooms.
- In August 2024, a global partnership for the supply of sustainable packaging materials from recycled plastics was announced with the signing of an MOU (Memorandum of Understanding) by Winpak Ltd. and SK Geo Centric (SKGC).
- In August 2023, at Labelexpo Europe 2023, two new decorative linerless solutions, pressure-sensitive labels, and developments in connected packaging, which is a micro-perforated technology launched by Avery Dennison. It is helpful for traceability and reduced environmental impact.
- In December, 2022, Laser micro-perforated bags were developed by Perfo Tec to increase the shelf life of products. Fresh products that are packaged have better quality and longer shelf lives thanks to this laser micro-perforation technique. According to PerfoTec study, utilizing this technique increases the shelf life of certain foods, including spinach, from seven to 21 days.
Market Concentration & Characteristics
The Micro Perforated Film Packaging Market shows moderate market concentration, with a mix of global leaders and regional manufacturers shaping its competitive dynamics. Large multinational companies, including Amcor Limited, Sealed Air Corporation, and Mondi Group, dominate due to their extensive distribution networks, advanced technology, and strong customer relationships. These players invest in R&D and focus on sustainability, targeting growing consumer demand for eco-friendly packaging. Regional players compete on cost efficiency and customized solutions, particularly in emerging markets. It demonstrates steady growth due to its essential role in preserving the freshness of perishable products across food segments. The market exhibits high demand elasticity, closely linked to consumer trends in fresh and ready-to-eat food products. Standardization and product differentiation are key characteristics, influenced by regulatory requirements and end-use application needs. It remains innovation-driven, with players introducing advanced perforation techniques and recyclable materials to strengthen market position. The presence of both established and emerging players ensures continuous competition and innovation.
Report Coverage
The research report offers an in-depth analysis based on Material Type, Technology, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will continue to grow steadily due to increasing demand for fresh and minimally processed food.
- Advancements in laser and mechanical perforation will improve packaging precision and performance.
- Sustainability initiatives will push manufacturers to adopt recyclable and biodegradable materials.
- Demand from e-commerce and organized retail sectors will expand usage in perishable goods packaging.
- Asia-Pacific will maintain its lead due to rising consumption and expanding food supply chains.
- Fruits and vegetables will remain the dominant application segment throughout the forecast period.
- Food safety regulations will drive innovation in breathable and hygienic packaging solutions.
- Global players will increase investment in emerging markets to strengthen regional presence.
- Product customization will grow as brands seek differentiation in competitive retail environments.
- Rising energy and raw material costs may pressure profit margins, especially for smaller manufacturers.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Growth in Fresh and Minimally Processed Food Consumption
Consumers are increasingly seeking fresh produce and minimally processed foods, which require packaging that maintains freshness and extends shelf life. Micro perforated film packaging enables controlled respiration, reducing spoilage and supporting the distribution of perishable goods.
Advancements in Perforation Technologies
Innovations in both mechanical and laser perforation techniques allow for precise control over airflow and moisture, improving the performance of packaging films. These advancements enable manufacturers to tailor packaging solutions to specific food types, enhancing shelf life and product quality.
Expansion of Organized Retail and E-commerce
The rapid growth of organized retail chains and online grocery platforms increases the need for reliable, durable packaging that preserves product integrity during storage and transit. Micro perforated films are well-suited for these channels, especially for temperature-sensitive and perishable items.
Sustainability and Regulatory Push for Eco-friendly Packaging
Rising environmental concerns and stricter regulations are driving demand for recyclable and biodegradable micro perforated films. Manufacturers are investing in sustainable materials and processes to meet both regulatory requirements and consumer expectations for green packaging.
Rising Investments in Food Packaging Infrastructure in Emerging Markets
Emerging economies, particularly in Asia-Pacific and Latin America, are investing in modern retail and cold chain logistics. This expansion fuels demand for advanced packaging solutions like micro perforated films, supporting the safe and efficient distribution of fresh and ready-to-eat foods.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Micro Perforated Film Packaging Market?
What are the key segments within the Micro Perforated Film Packaging Market?
Which segment is leading the Micro Perforated Film Packaging Market share?
What are the market drivers in the Micro Perforated Film Packaging Market?
Who are the major players in the Micro Perforated Films Packaging market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Technology
- 1.2.1 Mechanical Perforation
- 1.2.2 Laser Perforation
- 1.3 By Application
- 1.3.1 Fruits & Vegetables
- 1.3.2 Bakery & Confectionery
- 1.3.3 Ready-to-eat
- 1.3.4 Others
- 1.4 By Material Type
- 1.4.1 Polyethylene (PE)
- 1.4.2 Polypropylene (PP)
- 1.4.3 PET
- 1.4.4 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 1,920 million → 2032: USD 2,751 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Micro Perforated Film Packaging Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Micro Perforated Film Packaging Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Micro Perforated Film Packaging Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Micro Perforated Film Packaging Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Micro Perforated Film Packaging Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Micro Perforated Film Packaging Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Micro Perforated Film Packaging Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Micro Perforated Film Packaging Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 1,920 million → 2032: USD 2,751 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Micro Perforated Film Packaging Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Technology - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Mechanical Perforation
- 12.3.7.2 Laser Perforation
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Fruits & Vegetables
- 12.4.7.2 Bakery & Confectionery
- 12.4.7.3 Ready-to-eat
- 12.4.7.4 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Material Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Polyethylene (PE)
- 12.5.7.2 Polypropylene (PP)
- 12.5.7.3 PET
- 12.5.7.4 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Micro Perforated Film Packaging End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Micro Perforated Film Packaging Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Micro Perforated Film Packaging Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Micro Perforated Film Packaging Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Amcor Limited
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Sealed Air Corporation
- 18.4 Mondi Group
- 18.5 Coveris Holdings S.A.
- 18.6 Uflex Ltd.
- 18.7 Bolloré Group
- 18.8 TCL Packaging Ltd.
- 18.9 Avery Dennison Corporation
- 18.10 Amerplast
- 18.11 Now Plastics Inc.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

