
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Microbiology Testing Market Size 2024 | USD 3395 Million |
| Microbiology Testing Market, CAGR | 9.2% |
| Microbiology Testing Market Size 2032 | USD 6864.689 Million |
Market Overview:
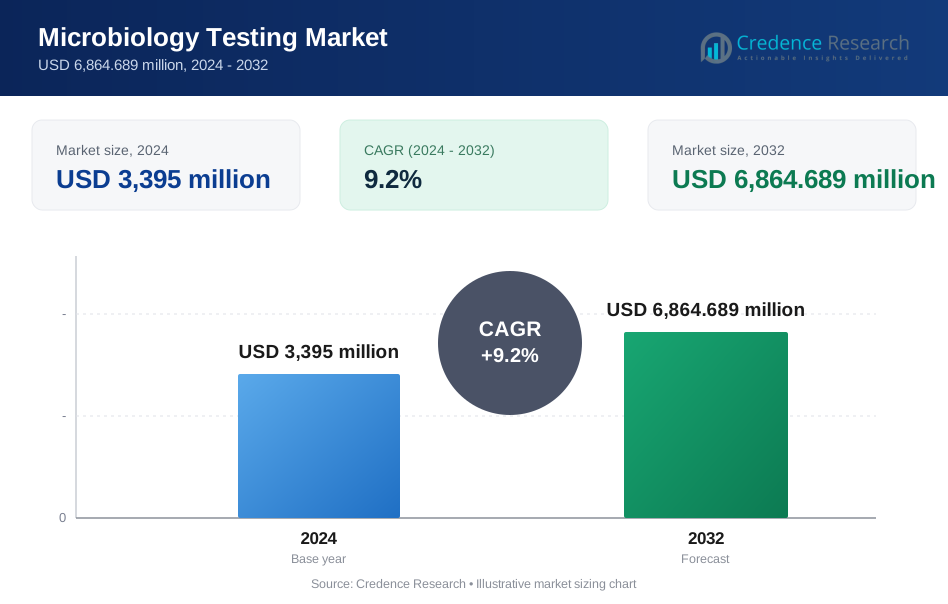
The Microbiology Testing Market is projected to grow from USD 3395 million in 2024 to an estimated USD 6864.689 million by 2032, with a compound annual growth rate (CAGR) of 9.2% from 2024 to 2032.
The growth of the Microbiology Testing market is propelled by several key drivers. The rising incidence of infectious diseases such as COVID-19, tuberculosis, and hospital-acquired infections has significantly increased the demand for rapid and accurate microbiological testing. Additionally, stringent regulatory guidelines for food and water safety, especially in developed regions, are driving the adoption of advanced microbiology testing solutions. The technological advancements in testing methods, such as the development of automated and rapid microbiological techniques, are also contributing to market growth. Moreover, the increasing investment in research and development by key players to develop novel diagnostic tests and kits is expected to further boost market demand.
North America dominates the Microbiology Testing market, accounting for the largest share due to the presence of well-established healthcare infrastructure, high healthcare expenditure, and a strong focus on research and development. The U.S. is the major contributor within this region, driven by the high adoption of advanced testing technologies and a strong presence of key market players. Europe follows closely, with countries like Germany, the U.K., and France being significant markets due to stringent food safety regulations and a growing emphasis on public health. The Asia-Pacific region is expected to witness the fastest growth during the forecast period, fueled by the increasing prevalence of infectious diseases, rising healthcare awareness, and growing investments in healthcare infrastructure in countries like China, India, and Japan.
Market Drivers:
Rising Prevalence of Infectious Diseases:
The increasing prevalence of infectious diseases is one of the primary drivers of the Microbiology Testing market. For instance, according to the World Health Organization's Global Tuberculosis Report 2022, an estimated 10.6 million people fell ill with tuberculosis in 2021, representing a 4.5% increase from 2020. The global burden of infections such as COVID-19, tuberculosis, HIV, and hospital-acquired infections has heightened the need for rapid and accurate diagnostic methods. The ongoing threat of pandemics and emerging pathogens has led to a surge in demand for microbiological testing to ensure timely diagnosis and treatment. This growing need for early detection and management of infectious diseases is pushing healthcare providers and laboratories to adopt advanced microbiology testing solutions, thus driving market growth.
Technological Advancements in Microbiology Testing:
Technological innovations are playing a crucial role in shaping the growth trajectory of the Microbiology Testing market. The shift from conventional culture-based methods to automated and rapid microbiological techniques has revolutionized the field. For instance, Innovations such as polymerase chain reaction (PCR), next-generation sequencing (NGS), and mass spectrometry have enhanced the accuracy, speed, and efficiency of microbiological tests. The National Healthcare Safety Network (NHSN) reported that in 2019, approximately 687,000 healthcare-associated infections (HAIs) occurred in U.S. acute care hospitals. These advancements allow for the detection of pathogens with higher sensitivity and specificity, reducing the time required for diagnosis and enabling more effective patient management. The continuous development of novel diagnostic tools and the integration of artificial intelligence (AI) and machine learning (ML) in microbiology testing are expected to further accelerate market growth.
Stringent Regulatory Standards and Food Safety Concerns:
The increasing emphasis on food safety and stringent regulatory standards are significant drivers of the Microbiology Testing market. Regulatory bodies across the globe, including the U.S. Food and Drug Administration (FDA), the European Food Safety Authority (EFSA), and the World Health Organization (WHO), have implemented strict guidelines to ensure the safety of food, water, and pharmaceuticals. These regulations mandate regular microbiological testing to detect and prevent contamination, leading to increased adoption of testing solutions by industries such as food and beverage, pharmaceuticals, and water treatment. The growing consumer awareness regarding foodborne illnesses and the demand for safe and high-quality products are also contributing to the expansion of the market.
Growing Investments in Research and Development:
The Microbiology Testing market is witnessing significant growth due to increasing investments in research and development by key market players and governments. These investments are aimed at developing innovative diagnostic tests, improving existing testing methods, and enhancing the overall accuracy and efficiency of microbiology testing. Pharmaceutical and biotechnology companies are focusing on the development of advanced testing kits and instruments to cater to the rising demand for microbiology testing in various applications. Additionally, government initiatives to strengthen healthcare infrastructure and promote the adoption of advanced diagnostic technologies are further fueling market growth. The collaboration between academic institutions, research organizations, and industry players is also fostering innovation and contributing to the expansion of the Microbiology Testing market.
Market Trends:
Increasing Adoption of Automated and Rapid Testing Methods:
One of the prominent trends in the Microbiology Testing market is the growing adoption of automated and rapid testing methods. Traditional culture-based techniques, while effective, are time-consuming and labor-intensive. In contrast, automated systems and rapid microbiological methods offer faster results with higher accuracy, enabling quicker decision-making in clinical settings. The introduction of technologies like real-time PCR, microarrays, and next-generation sequencing has significantly reduced the time required for pathogen detection and identification. Laboratories are increasingly adopting these advanced methods to enhance efficiency, reduce turnaround times, and improve patient outcomes, driving the market forward.
Integration of Artificial Intelligence and Machine Learning:
The integration of artificial intelligence (AI) and machine learning (ML) into microbiology testing is an emerging trend that is transforming the industry. AI and ML algorithms are being utilized to analyze complex microbiological data, identify patterns, and predict outcomes with greater accuracy. These technologies are particularly beneficial in the interpretation of large datasets generated by advanced diagnostic tools like NGS. AI-driven platforms can assist in the early detection of outbreaks, antimicrobial resistance patterns, and emerging pathogens. For instance, data from BioFire Diagnostics indicates that their FilmArray system can identify more than 20 pathogens in a single test within about an hour, significantly reducing time to diagnosis for respiratory infections. The ability of AI and ML to improve diagnostic precision and optimize laboratory workflows is encouraging their adoption across the microbiology testing landscape, leading to innovative solutions and enhanced testing capabilities.
Focus on Point-of-Care Testing (POCT):
The shift towards point-of-care testing (POCT) is another significant trend in the Microbiology Testing market. POCT offers the advantage of delivering rapid results at or near the site of patient care, which is critical in managing infectious diseases and controlling outbreaks. For instance, data from Cepheid indicates that their GeneXpert Xpress SARS-CoV-2 test can provide results in about 45 minutes, enabling rapid triage of patients in healthcare settings. The development of portable and user-friendly microbiological testing devices has enabled healthcare providers to conduct tests outside traditional laboratory settings, such as in clinics, emergency rooms, and even at home. The COVID-19 pandemic has further accelerated the adoption of POCT, as it highlighted the need for quick and accurate diagnostics. As the demand for decentralized testing continues to rise, the market is witnessing a surge in the development and deployment of POCT devices tailored for microbiology testing.
Expansion of Microbiome Research:
The growing interest in microbiome research is influencing trends in the Microbiology Testing market. The human microbiome, consisting of trillions of microorganisms residing in the body, plays a crucial role in health and disease. Advances in microbiology testing technologies, such as metagenomics and high-throughput sequencing, have enabled a deeper understanding of the microbiome and its implications for conditions like gastrointestinal disorders, metabolic diseases, and even mental health. This expanding field of research is driving the demand for specialized microbiology testing solutions that can analyze complex microbial communities. The ongoing exploration of the microbiome's impact on health is expected to open new avenues for market growth, as researchers and healthcare providers increasingly rely on microbiological testing to unlock the potential of personalized medicine and therapeutic interventions.
Market Restraints and Challenges:
High Costs of Advanced Testing Technologies:
One of the key restraints in the Microbiology Testing market is the high cost associated with advanced testing technologies. While automated and rapid microbiological methods offer significant advantages in terms of accuracy and speed, they often require substantial investment in specialized equipment and reagents. Smaller laboratories and healthcare facilities, particularly in developing regions, may find it challenging to adopt these technologies due to budget constraints. The high costs can also limit the affordability of these tests for patients, potentially hindering widespread adoption and market growth.
Regulatory and Compliance Challenges:
Navigating the complex regulatory landscape is another significant challenge in the Microbiology Testing market. The stringent requirements imposed by regulatory bodies, such as the U.S. FDA and the European Medicines Agency (EMA), necessitate rigorous validation and compliance processes for new microbiological testing products. Meeting these regulatory standards can be time-consuming and costly, delaying the launch of innovative testing solutions. Additionally, variations in regulations across different regions create complexities for companies seeking to expand their global footprint, further complicating market dynamics.
Limited Availability of Skilled Professionals:
The shortage of skilled professionals trained in microbiology testing poses a challenge to the market. Advanced microbiological techniques require specialized knowledge and expertise to operate sophisticated equipment and interpret complex data. However, there is a growing gap between the demand for such professionals and their availability, particularly in emerging markets. This shortage can lead to operational inefficiencies, increased turnaround times, and a potential decline in the quality of testing services. The need for continuous education and training to keep pace with technological advancements also adds to the challenge of maintaining a skilled workforce in this rapidly evolving field.
Impact of Reimbursement Policies:
Reimbursement policies for microbiology testing can significantly impact market growth. In many regions, reimbursement rates for diagnostic tests may not fully cover the costs of advanced microbiology testing, making it less economically viable for healthcare providers to offer these services. The variability in reimbursement policies across different healthcare systems creates uncertainty for market participants, potentially limiting the adoption of new and innovative testing methods. This challenge underscores the importance of aligning reimbursement policies with the evolving landscape of microbiology testing to support sustainable market growth.
Market Segmentation Analysis:
By Product:
The market is divided into instruments, reagents, and consumables. Instruments, including automated systems and incubators, hold a substantial share due to their crucial role in streamlining microbiological testing processes. Reagents and consumables are essential for conducting tests and maintaining equipment, and their demand is driven by the need for regular replacements and updates.
By Test Type:
The market encompasses traditional culturing methods, molecular diagnostics, and immunoassays. Molecular diagnostics, including PCR and next-generation sequencing, are growing rapidly due to their high sensitivity and speed. Traditional culturing methods remain significant for their reliability and established protocols, while immunoassays are valued for their specificity in detecting pathogens.
By Application:
The primary applications include clinical diagnostics, environmental testing, food and beverage testing, and pharmaceutical testing. Clinical diagnostics is the largest segment, driven by the need for accurate and rapid identification of infectious diseases. Environmental and food testing are expanding due to heightened awareness of contamination risks and stringent safety regulations. Pharmaceutical testing is crucial for ensuring the quality and safety of drug products.
By End User:
Key end users are hospitals and diagnostic laboratories, pharmaceutical companies, research institutions, and environmental testing agencies. Hospitals and diagnostic laboratories dominate due to their extensive need for microbiological testing in patient care. Pharmaceutical companies and research institutions rely on microbiology testing for drug development and research, while environmental testing agencies focus on monitoring and maintaining safety standards in various environments.
Segmentation:
By Product:
- Instruments,
- Reagents,
- Consumables
By Test Type:
- Traditional culturing methods,
- Molecular diagnostics,
- Immunoassays
By Application:
- Clinical diagnostics,
- Environmental testing,
- Food and beverage testing,
- Pharmaceutical testing.
By End User:
- Hospitals and diagnostic laboratories,
- Pharmaceutical companies,
- Research institutions,
- Environmental testing agencies.
- North America
- The U.S
- Canada
- Mexico
- Europe
- Germany
- France
- The U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of Middle East and Africa
Regional Analysis:
North America
North America holds the largest share of the global Microbiology Testing market, accounting for approximately 35% of the total market in 2023. The region's dominance is primarily attributed to its advanced healthcare infrastructure, high healthcare expenditure, and early adoption of innovative testing technologies. The United States, in particular, is a key contributor to this market, driven by a strong focus on research and development, a well-established regulatory environment, and a high prevalence of infectious diseases. The robust presence of leading market players and continuous government support for healthcare initiatives further bolster market growth in North America.
Europe
Europe follows closely with a market share of around 28%. The region's growth is driven by stringent regulatory standards for food and water safety, which necessitate regular microbiological testing. Countries such as Germany, the United Kingdom, and France are significant markets within the region due to their advanced healthcare systems and strong emphasis on public health. The European market also benefits from the growing demand for rapid and accurate diagnostic tests, particularly in response to the rising incidence of infectious diseases and hospital-acquired infections. Additionally, the increasing focus on antimicrobial resistance and the development of new testing methods contribute to the market's expansion in Europe.
Asia-Pacific
The Asia-Pacific region is expected to witness the fastest growth during the forecast period, with a current market share of approximately 22%. The region's rapid expansion is driven by the increasing prevalence of infectious diseases, rising healthcare awareness, and growing investments in healthcare infrastructure. Countries like China, India, and Japan are leading the market in Asia-Pacific, supported by large populations, expanding middle-class demographics, and government initiatives to improve healthcare access. The region's market growth is further fueled by the increasing adoption of advanced testing technologies and the expansion of multinational companies into emerging markets.
Latin America and the Middle East & Africa
Latin America and the Middle East & Africa collectively account for the remaining 15% of the market. While these regions currently have smaller market shares, they are poised for growth due to improving healthcare infrastructure, increasing awareness of infectious diseases, and efforts to enhance diagnostic capabilities. Brazil and Mexico are the leading markets in Latin America, while South Africa and the Gulf Cooperation Council (GCC) countries are key contributors in the Middle East & Africa region. The growing focus on public health and the gradual adoption of advanced microbiology testing methods are expected to drive market growth in these regions over the coming years.
Key Player Analysis:
- Abbott Laboratories
- Agilent Technologies Inc.
- Baxter (U.S.)
- Beckman Coulter, Inc.
- Becton Dickinson and Company
- Biomerieux SA
- Bio-Rad Laboratories Inc.
- Bruker Corporation
- Cerner Corporation (U.S.)
- Cisco (U.S.)
- Danaher Corporation (Cepheid Inc.)
- Digi International Inc. (U.S.)
- Hoffmann-La Roche Ltd
- General Electric (U.S.)
- Hill-Rom Services Inc. (U.S.)
- Hologic Corporation
- Iatric Systems Inc. (U.S.)
- iHealth Labs Inc., (U.S.)
- Koninklijke Philips N.V. (Netherlands)
- Masimo (U.S.)
- Medicollector (U.S.)
- Medtronic (Ireland)
- Merck KGaA
- NEOGEN Corporation
- QIAGEN
- Shimadzu Corporation
- Silex Technology America, Inc. (Japan)
- Silicon & Software Systems Ltd. (Ireland)
- Spectrum Medical (U.K.)
- Stryker (U.S.)
- TE Connectivity (Switzerland)
- Thermo Fisher Scientific Inc.
Competitive Analysis:
The Microbiology Testing market is highly competitive, characterized by the presence of several key players striving for market leadership through innovation and strategic collaborations. Major companies such as bioMérieux, Thermo Fisher Scientific, Danaher Corporation, and Becton, Dickinson and Company dominate the market, offering a wide range of advanced diagnostic solutions. These companies focus on expanding their product portfolios, investing in research and development, and acquiring smaller firms to enhance their market presence. Emerging players are also entering the market, driven by technological advancements and the growing demand for rapid testing methods. The competitive landscape is further intensified by the increasing adoption of automation and artificial intelligence in microbiology testing, pushing companies to continuously innovate and improve their offerings. As the market evolves, strategic partnerships and geographic expansion remain critical strategies for maintaining a competitive edge.
Recent Developments:
- In 2022, IDEXX acquired Tecta-PDS, a Canadian company known for its innovative automation in water microbiology testing for parameters such as E. coli and total coliforms. This acquisition enhanced IDEXX's portfolio of water microbiology testing solutions, expanding options for both laboratory and in-field testing.
- In 2022, Archer Daniels Midland (ADM) opened a new microbiology laboratory at its ADM Specialty Manufacturing facility in Decatur, Illinois. This expansion significantly increased the laboratory’s footprint and boosted its testing capabilities.
Market Concentration & Characteristics:
The Microbiology Testing market exhibits moderate market concentration, with a few major players holding a significant share of the market. Companies like bioMérieux, Thermo Fisher Scientific, and Danaher Corporation lead the industry due to their extensive product portfolios, global reach, and strong research and development capabilities. These key players dominate the market through continuous innovation, advanced technology adoption, and strategic mergers and acquisitions. The market is characterized by rapid technological advancements, particularly in automation and molecular diagnostics, which are reshaping traditional microbiology testing methods. The increasing demand for faster, more accurate diagnostic tools is driving the adoption of next-generation sequencing, real-time PCR, and point-of-care testing devices. The market also shows a growing trend towards personalized medicine and the integration of artificial intelligence, reflecting the evolving needs of healthcare providers and the push towards more efficient and precise diagnostic solutions
Report Coverage:
The research report offers an in-depth analysis based on By Product, By Test Type, By Application, and By End User. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Rapid technological advancements will continue to drive market growth, particularly in automated and molecular diagnostic methods.
- Increased adoption of AI and machine learning will enhance data analysis capabilities, leading to more accurate and faster microbiology testing.
- Expansion of point-of-care testing will make diagnostics more accessible, particularly in decentralized healthcare settings.
- Growing focus on antimicrobial resistance will boost demand for specialized microbiology testing solutions.
- Rising investments in healthcare infrastructure in emerging markets will open new growth opportunities.
- Advancements in microbiome research will drive demand for novel testing solutions that can analyze complex microbial communities.
- Strategic collaborations and partnerships among key players will foster innovation and expand market reach.
- Regulatory developments will shape market dynamics, with evolving standards influencing product approvals and adoption.
- Shift towards personalized medicine will increase the need for microbiology testing in tailored treatment plans.
- Sustained growth in infectious disease testing will remain a key market driver, particularly in response to global health challenges.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Prevalence of Infectious Diseases
The increasing incidence of infectious diseases such as COVID-19, tuberculosis, and hospital-acquired infections is driving demand for rapid and accurate microbiology testing to enable timely diagnosis and treatment.
Technological Advancements in Testing Methods
Innovations like PCR, next-generation sequencing, and automated systems have improved the speed, accuracy, and efficiency of microbiology testing, encouraging broader adoption across healthcare and industrial sectors.
Stringent Regulatory Standards and Food Safety Concerns
Global regulatory bodies require regular microbiological testing for food, water, and pharmaceuticals, pushing industries to adopt advanced testing solutions to comply with safety standards and prevent contamination.
Growing Investments in Research and Development
Increased funding from both private companies and governments is accelerating the development of novel diagnostic tests and kits, expanding the capabilities and applications of microbiology testing.
Expansion of Point-of-Care and Decentralized Testing
The shift toward point-of-care testing, especially highlighted during the COVID-19 pandemic, is making microbiology diagnostics more accessible and enabling faster clinical decision-making outside traditional laboratory settings.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the Microbiology Testing market?
What are the main drivers of market growth?
Which region dominates the Microbiology Testing market?
What are the challenges facing the Microbiology Testing market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product
- 1.2.1 Instruments
- 1.2.2 Reagents
- 1.2.3 Consumables
- 1.3 By End User
- 1.3.1 Hospitals and diagnostic laboratories
- 1.3.2 Pharmaceutical companies
- 1.3.3 Research institutions
- 1.3.4 Environmental testing agencies
- 1.4 By Test Type
- 1.4.1 Traditional culturing methods
- 1.4.2 Molecular diagnostics
- 1.4.3 Immunoassays
- 1.5 By Application
- 1.5.1 Clinical diagnostics
- 1.5.2 Environmental testing
- 1.5.3 Food and beverage testing
- 1.5.4 Pharmaceutical testing
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 3,395 million → 2032: USD 6,864.689 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Microbiology Testing Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Microbiology Testing Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Microbiology Testing Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Microbiology Testing Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Microbiology Testing Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Microbiology Testing Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Microbiology Testing Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Microbiology Testing Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 3,395 million → 2032: USD 6,864.689 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Microbiology Testing Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Instruments
- 12.3.7.2 Reagents
- 12.3.7.3 Consumables
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End User - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Hospitals and diagnostic laboratories
- 12.4.7.2 Pharmaceutical companies
- 12.4.7.3 Research institutions
- 12.4.7.4 Environmental testing agencies
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Test Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Traditional culturing methods
- 12.5.7.2 Molecular diagnostics
- 12.5.7.3 Immunoassays
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Application - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Clinical diagnostics
- 12.6.7.2 Environmental testing
- 12.6.7.3 Food and beverage testing
- 12.6.7.4 Pharmaceutical testing
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Microbiology Testing End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Microbiology Testing Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Microbiology Testing Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Microbiology Testing Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 bioMérieux SA
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Thermo Fisher Scientific Inc.
- 18.4 Danaher Corporation (Cepheid Inc.)
- 18.5 Becton Dickinson and Company
- 18.6 QIAGEN
- 18.7 Abbott Laboratories
- 18.8 Agilent Technologies Inc.
- 18.9 Bio-Rad Laboratories Inc.
- 18.10 Merck KGaA
- 18.11 Hoffmann-La Roche Ltd
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

