
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Microcatheter Market Size 2024 | USD 2,144.82 million |
| Microcatheter Market, CAGR | 5.09% |
| Microcatheter Market Size 2032 | USD 3,182.70 million |
Market Overview
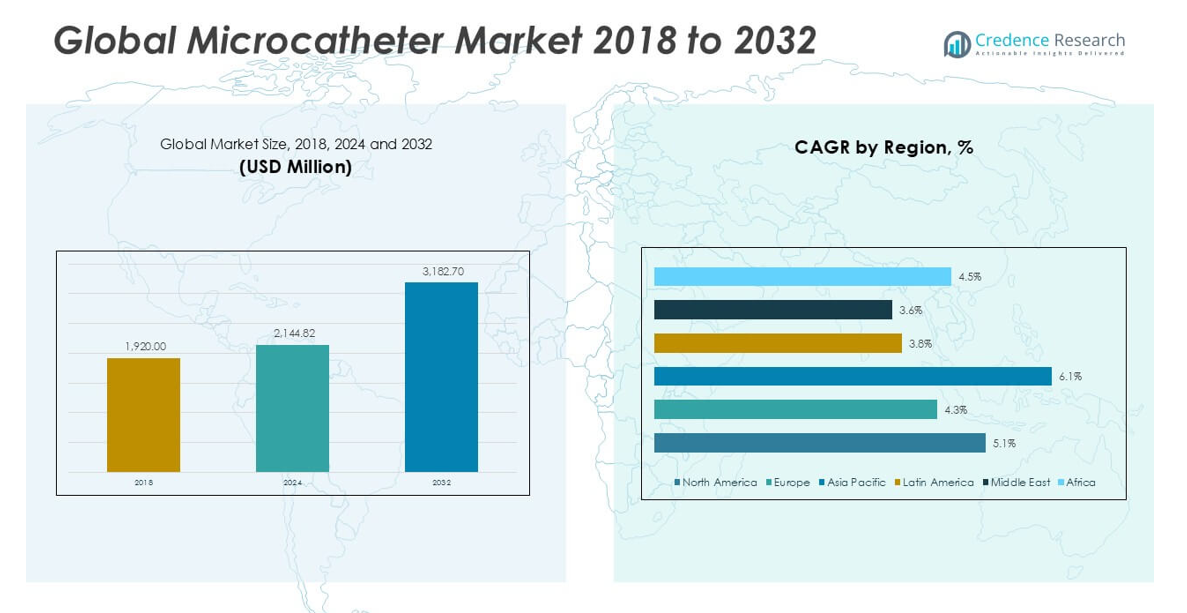
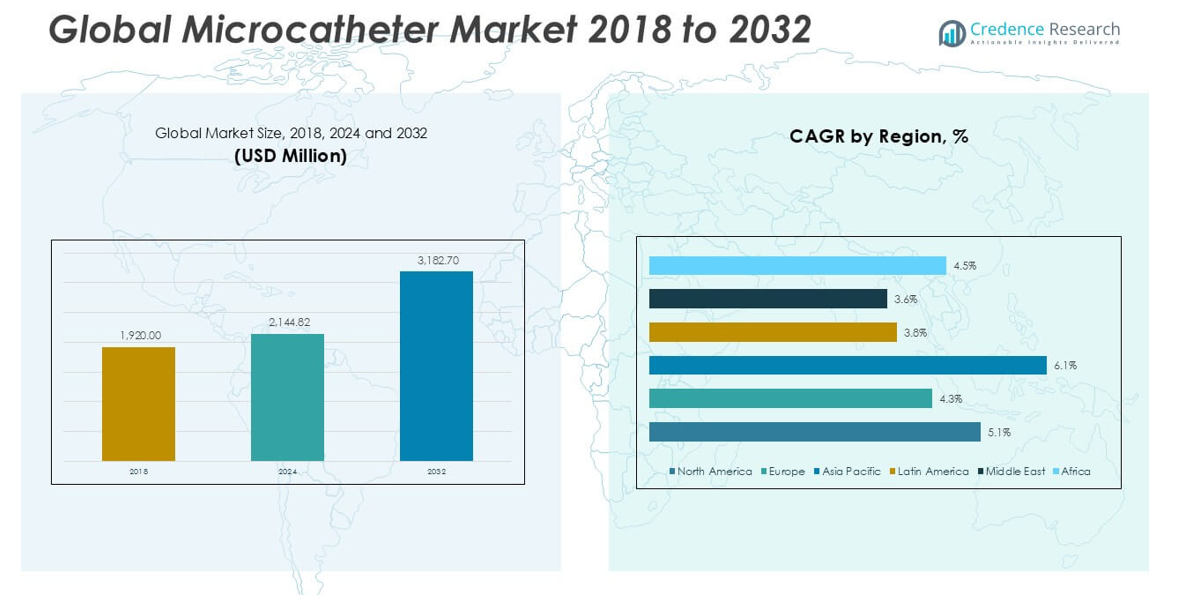
The Global Microcatheter Market is projected to grow from USD 2,144.82 million in 2024 to an estimated USD 3,182.70 million based on 2032, with a compound annual growth rate (CAGR) of 5.09% from 2025 to 2032.
Key drivers of the microcatheter market include technological advancements such as dual-lumen and torque-enhanced microcatheters, which improve procedural accuracy and safety. The shift toward image-guided and catheter-based interventions has elevated the importance of microcatheters in clinical practice. Trends indicate increasing adoption of drug-delivery microcatheters and growing usage in embolization procedures. Healthcare infrastructure development and rising geriatric population also support market momentum. Manufacturers are focusing on product customization and expanding indications to address specialty-specific needs.
North America holds a dominant share of the global microcatheter market due to high procedural volumes, established reimbursement policies, and early adoption of advanced devices. Europe follows closely, supported by robust healthcare systems and increased focus on minimally invasive treatment options. The Asia-Pacific region is expected to exhibit the fastest growth, driven by rising healthcare investments and medical tourism in countries such as India and China. Key players include Medtronic plc, Boston Scientific Corporation, Terumo Corporation, Stryker Corporation, and Merit Medical Systems, Inc., all competing through innovation, geographic expansion, and strategic acquisitions.
Market Insights
- The global microcatheter market is projected to grow from USD 2,144.82 million in 2024 to USD 3,182.70 million by 2032, registering a CAGR of 5.09% during the forecast period.
- Increased adoption of minimally invasive procedures in cardiology, neurology, and oncology is a primary factor boosting demand for microcatheters worldwide.
- Development of dual-lumen, torque-responsive, and drug-delivery microcatheters enhances procedural precision and expands therapeutic applications.
- The high cost of advanced microcatheters and limited reimbursement in emerging economies restrict adoption in resource-constrained healthcare systems.
- Successful use of microcatheters often depends on clinician expertise and specialized training, posing challenges in lower-tier hospitals.
- North America held the largest market share in 2024 due to high procedure volumes and established healthcare reimbursement infrastructure.
- Asia Pacific is projected to grow at the highest CAGR of 6.1%, driven by expanding healthcare investments and strong demand from India and China.
Market Drivers
Rising Prevalence of Chronic Diseases Driving Minimally Invasive Interventions
The increasing incidence of cardiovascular, neurovascular, and oncological disorders continues to drive demand for microcatheters. Physicians prefer minimally invasive procedures to reduce patient recovery time, lower complication risks, and shorten hospital stays. The Global Microcatheter Market benefits from this shift toward catheter-based treatment strategies in both developed and emerging economies. It supports precise navigation through complex vasculature, making it ideal for procedures like embolization, stent delivery, and coil deployment. Growing awareness among clinicians and patients about minimally invasive benefits accelerates procedural volumes. Hospitals and outpatient facilities invest in advanced devices to enhance treatment outcomes and expand their interventional portfolios.
- For instance, according to the American College of Cardiology, over 1.3 million catheter-based coronary interventions were performed in the United States in 2023, illustrating the widespread adoption of minimally invasive techniques that rely on microcatheters.
Technological Advancements Enhancing Device Performance and Applications
Continuous innovation in microcatheter technology enhances device flexibility, torque response, and navigation precision. Dual-lumen, tapered-tip, and hydrophilic-coated designs improve procedural efficiency and safety across various specialties. The Global Microcatheter Market gains momentum from the development of drug-eluting and steerable microcatheters, which support broader therapeutic applications. Integration of imaging guidance, such as DSA and IVUS compatibility, strengthens the role of microcatheters in real-time diagnostics and therapy. It supports accurate lesion targeting and improves success rates in complex cases. Companies invest in R\&D to offer specialty-specific solutions for neurointerventional, peripheral vascular, and coronary procedures.
- For instance, its 2024 annual innovation update that it launched 12 new microcatheter models globally in a single year, each designed for specific clinical applications and enhanced imaging compatibility.
Expanding Use in Embolization and Targeted Drug Delivery Procedures
The growing number of embolization therapies and targeted drug delivery procedures stimulates microcatheter adoption. Interventional radiologists use it for selective delivery of embolic agents in uterine fibroid embolization, liver cancer treatment, and gastrointestinal bleeding control. The Global Microcatheter Market benefits from increasing preference for super-selective embolization, which demands precise and reliable catheter performance. It enables effective therapy with minimal damage to surrounding tissues. High procedural success rates and patient tolerability encourage hospitals to incorporate microcatheters into routine practice. Demand rises across oncology, urology, and gynecology departments seeking to expand non-surgical treatment options.
Improving Healthcare Access and Investments in Emerging Economies
Healthcare systems in Asia-Pacific, Latin America, and the Middle East increase investments in interventional infrastructure and advanced diagnostic facilities. Governments prioritize expanding access to minimally invasive procedures through public-private partnerships and import support policies. The Global Microcatheter Market grows rapidly in these regions due to rising medical tourism, higher diagnostic rates, and skilled workforce development. It aligns with broader health reforms aimed at reducing surgery-related costs and improving outcomes. Local distributors collaborate with global manufacturers to expand device availability and training programs. Rising disposable income and insurance penetration further boost patient access to advanced interventions.
Market Trends
Growing Integration of Image-Guided and Navigation-Assisted Microcatheters
Healthcare providers increasingly adopt microcatheters compatible with real-time imaging technologies to improve procedural outcomes. Image-guided systems such as fluoroscopy, intravascular ultrasound (IVUS), and digital subtraction angiography (DSA) enable physicians to visualize anatomy during device navigation. The Global Microcatheter Market benefits from this integration, especially in neurovascular and coronary interventions. It allows accurate targeting, better lesion access, and improved safety margins in complex procedures. Manufacturers develop devices with radiopaque markers and enhanced visibility to support these imaging standards. This trend reflects the clinical demand for precision, control, and patient-specific therapy planning.
- For instance, Philips Healthcare reported delivering over 3,800 integrated IVUS and DSA imaging systems to hospitals worldwide in 2024, supporting the widespread use of image-guided microcatheter procedures
Rising Adoption of Specialty-Specific and Custom-Designed Microcatheters
Device customization to meet specialty requirements is shaping purchasing decisions across hospitals and surgical centers. Manufacturers design microcatheters for specific applications such as neurovascular thrombectomy, hepatic embolization, or peripheral occlusion therapy. The Global Microcatheter Market sees growth from this trend as clinicians demand tailored solutions that fit procedural nuances. It improves efficiency and reduces the risk of intra-procedural complications. Surgeons increasingly prefer devices with specific torque response, tip shape, and shaft length configurations. This tailored design approach enhances clinical confidence and patient outcomes in high-risk or anatomically challenging cases.
- For instance, more than 1,200 hospitals in the United States adopted at least three different specialty-specific microcatheter models for neurovascular and peripheral interventions within the year.
Increasing Demand for Drug-Eluting and Coated Microcatheters
Drug-eluting microcatheters attract clinical interest for their ability to deliver localized therapy in vascular and oncological interventions. These devices reduce systemic drug exposure while increasing therapeutic concentration at the target site. The Global Microcatheter Market gains value through the adoption of coated catheters that provide enhanced trackability and lower friction. It supports smoother navigation through tortuous vessels and reduces procedure time. Research continues into integrating anti-thrombotic and anti-inflammatory coatings for safer long-term outcomes. Hospitals prioritize these advanced microcatheters for complex cases requiring sustained drug release or reduced restenosis risk.
Expansion of Outpatient and Ambulatory Interventional Procedures
Shifting clinical workflows toward ambulatory settings fuels demand for compact, easy-to-use microcatheters. Outpatient centers focus on increasing throughput and reducing procedure costs while maintaining quality care standards. The Global Microcatheter Market aligns with this trend by offering single-use, sterile-packed, and highly maneuverable devices. It enables faster turnover and minimizes cross-contamination risks in high-volume environments. Growth in ambulatory surgery centers and day-care interventional labs drives procurement of simplified microcatheter systems. This shift encourages innovation toward cost-effective, procedure-ready solutions for routine and advanced interventions.
Market Challenges
High Device Costsand Reimbursement Limitations Affecting Market Penetration
The high cost of microcatheters and related consumables limits adoption, especially in cost-sensitive and low-resource healthcare settings. Many hospitals face budget constraints that restrict investment in premium interventional tools. The Global Microcatheter Market struggles in regions where public health systems lack structured reimbursement for advanced procedures. It deters smaller hospitals and ambulatory centers from expanding interventional portfolios. Price sensitivity among end-users pressures manufacturers to balance innovation with affordability. Unfavorable reimbursement policies and inconsistent insurance coverage further complicate market access in several countries.
- For instance, a national study in the United States found that among catheter users with commercial insurance, the average annual out-of-pocket cost for catheters and supplies reached $2,188 for United Healthcare members, $1,670 for BlueCross BlueShield, and $1,385 for Aetna, with over 1 in 10 users reporting reuse of catheters due to cost and lack of coverage
Technical Complexity and Operator Skill Requirements Restraining Usage
Microcatheter procedures demand a high level of precision and operator expertise, which limits their widespread use. Interventional success often depends on the clinician’s ability to navigate complex vasculature and manage device performance. The Global Microcatheter Market faces resistance in facilities with limited training infrastructure or inconsistent procedural volumes. It hinders adoption in secondary and tertiary care institutions without experienced staff. Prolonged learning curves and lack of specialized support teams increase procedural risk and slow institutional adoption. Manufacturers must invest in clinician education and simulation-based training to overcome skill-related barriers
Market Opportunities
Expanding Applications in Oncology, Urology, and Peripheral Interventions
Microcatheters are gaining traction beyond cardiology and neurovascular segments, with increasing use in oncology, urology, and peripheral vascular procedures. Physicians rely on microcatheters for targeted drug delivery, tumor embolization, and selective angiography in complex anatomical regions. The Global Microcatheter Market finds new growth avenues through these expanding clinical applications. It supports tailored therapies with reduced systemic side effects and higher procedural precision. Growing incidence of cancer and non-cardiac vascular disorders presents a sizable opportunity for product diversification. Manufacturers can capitalize on unmet needs by developing application-specific variants and cross-specialty platforms.
Rising Demand Across Emerging Markets and Ambulatory Care Settings
Emerging economies invest heavily in healthcare infrastructure, creating favorable conditions for advanced interventional procedures. Rising disposable income, increasing insurance coverage, and growing awareness of minimally invasive options encourage broader microcatheter use. The Global Microcatheter Market stands to benefit from rapid expansion of ambulatory surgical centers and outpatient labs. It aligns with health systems focusing on efficient, high-throughput solutions that reduce hospital burden. Companies that offer training programs, cost-effective models, and regional partnerships can gain significant market share. Localization strategies and customized product offerings will strengthen presence in high-growth geographies.
Market Segmentation Analysis
By Product
The Global Microcatheter Market comprises a diverse range of product types tailored for specific clinical needs. Delivery microcatheters hold a dominant share due to their extensive use in therapeutic procedures such as stent placement and embolization. Aspiration microcatheters are gaining momentum in thrombus removal and neurovascular interventions. Diagnostic microcatheters support lesion access and vessel imaging, while steerable microcatheters improve navigation through tortuous anatomy. Emerging products focus on improving trackability, pushability, and safety. It continues evolving with innovations that enhance multi-specialty performance and clinical precision.
- For instance, in 2024, dual lumen microcatheters generated $1,473.8 million in revenue, making them the largest product segment by sales volume in the global market.
By Application
The market spans a wide array of clinical applications, with cardiology and neurology leading in procedural volume and device demand. Peripheral vascular and oncology interventions represent growing segments driven by rising cases of vascular disease and targeted tumor therapies. Urology and otolaryngology applications are expanding through minimally invasive techniques in delicate anatomical areas. The Global Microcatheter Market aligns with clinical shifts toward non-surgical interventions across these domains. It supports super-selective access and targeted treatment delivery. Applications across emerging specialties contribute to segment diversification and sustained growth.
- For instance, in 2024, the cardiology segment accounted for the highest procedural volume, with over 610,000 microcatheter-assisted cardiac interventions performed globally.
By End-User
Hospitals and clinics form the largest end-user group due to high patient volumes, advanced infrastructure, and availability of trained specialists. Ambulatory surgical centers are rapidly adopting microcatheters, seeking to deliver cost-efficient and timely care. The Global Microcatheter Market benefits from the operational flexibility and growing procedural capabilities of these centers. Other settings include specialty care units and diagnostic labs that require high-precision tools for image-guided interventions. It supports wide-scale adoption across various clinical environments.
By Product Design
Single lumen microcatheters dominate due to their simplicity, versatility, and broad applicability in standard procedures. Dual lumen microcatheters are increasingly preferred in complex cases requiring simultaneous injection or wire access. The Global Microcatheter Market reflects a growing interest in advanced lumen designs to enhance procedural efficiency. It enables controlled navigation and supports innovation in device engineering. Design selection depends on clinical objectives and anatomical complexity.
Segments
Based on Product
- Delivery Microcatheters
- Product 2
- Aspiration Microcatheters
- Diagnostic Microcatheters
- Steerable Microcatheters
Based on Application
- Cardiology
- Neurology
- Peripheral Vascular
- Oncology
- Urology
- Otolaryngology
- Others
Based on End-user
- Hospitals and Clinics
- Ambulatory Surgical Centers
- Others
Based on Product Design
- Single Lumen
- Dual Lumen
Based on Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis
North America Microcatheter Market
North America holds the largest share in the global microcatheter market, accounting for 34.1% of the total revenue in 2024. The market is projected to grow from USD 731.80 million in 2024 to USD 1,082.09 million by 2032, at a CAGR of 5.1%. The region benefits from advanced healthcare infrastructure, high procedural volumes, and strong reimbursement frameworks. The United States drives demand through widespread use in cardiology and neurointerventional procedures. It supports rapid adoption of newer technologies and maintains a steady demand for precision-driven devices. The microcatheter market continues expanding with increased focus on minimally invasive treatments and outpatient care.
Europe Microcatheter Market
Europe represents a significant share of the global market with 24.3% of revenue in 2024. It is projected to grow from USD 520.70 million in 2024 to USD 728.05 million by 2032, registering a CAGR of 4.3%. Germany, France, and the UK lead in procedural adoption due to their strong public health systems and investment in interventional technology. The region focuses on neurovascular and peripheral interventions, supported by skilled professionals and access to advanced tools. The microcatheter market in Europe maintains steady growth through clinical research initiatives and cross-border healthcare programs. It shows resilience through integration of specialty-specific devices in diverse medical settings.
Asia Pacific Microcatheter Market
Asia Pacific accounts for 30.6% of global revenue in 2024 and shows the fastest growth, with a CAGR of 6.1%. The market is expected to rise from USD 655.98 million in 2024 to USD 1,050.75 million by 2032. China, Japan, and India lead the region, supported by increasing healthcare investment, rising chronic disease prevalence, and expanding medical tourism. The microcatheter market benefits from strong procedural demand across cardiology, oncology, and neurology. It gains traction through local manufacturing, government support, and growing clinician expertise. Asia Pacific is a focal point for cost-effective innovation and strategic product expansion.
Latin America Microcatheter Market
Latin America holds 5.1% of the global market in 2024 and is forecasted to grow from USD 108.08 million in 2024 to USD 144.91 million by 2032, at a CAGR of 3.8%. Brazil and Mexico drive market growth through improving access to interventional healthcare and expanding private sector investments. The microcatheter market sees growing adoption in oncology and peripheral vascular procedures. It aligns with regional priorities focused on non-surgical treatment options and reducing surgical wait times. Increased collaborations between public institutions and device manufacturers support training and device availability. Latin America remains a modest but growing contributor to global volume.
Middle East Microcatheter Market
The Middle East microcatheter market is projected to grow from USD 70.34 million in 2024 to USD 93.19 million by 2032, reflecting a CAGR of 3.6% and contributing 3.3% to global revenue. The UAE and Saudi Arabia lead in adopting advanced interventional solutions due to rising chronic disease burden and strong infrastructure investment. The microcatheter market benefits from demand in cardiovascular care and expansion of specialty clinics. Regional healthcare reforms prioritize early diagnosis and minimally invasive treatment patways. It reflects steady growth supported by training programs and medical equipment procurement from global manufacturers.
Africa Microcatheter Market
Africa accounts for 2.7% of the global market and is expected to grow from USD 57.92 million in 2024 to USD 83.71 million by 2032, registering a CAGR of 4.5%. South Africa and Egypt anchor regional demand through growing investments in interventional radiology and surgical infrastructure. The microcatheter market expands through donor funding, public health initiatives, and introduction of cost-effective solutions. It supports broader access to cardiac and cancer care in urban centers. Training and awareness efforts remain key to expanding procedural capacity. Africa represents a high-potential region for future market development.
Key players
- Medtronic
- Terumo Corporation
- Merit Medical Systems
- Stryker
- Penumbra, Inc.
- Boston Scientific Corporation
- Teleflex Incorporated
- ASAHI INTECC USA, INC.
- Surmodics, Inc.
- BIOCARDIA, INC.
Competitive Analysis
The global microcatheter market features a competitive landscape dominated by established medical device companies with broad product portfolios. Medtronic, Boston Scientific, and Terumo lead through continuous innovation, strategic acquisitions, and expansive global reach. Stryker and Penumbra focus on neurovascular applications with specialized devices and strong R\&D pipelines. Teleflex and Merit Medical invest in expanding procedural coverage and clinician engagement. ASAHI INTECC and Surmodics emphasize material technology and coating innovations to enhance product performance. The market rewards companies that align device development with specialty-specific needs and clinical workflow efficiency. It reflects strong competition in product differentiation, global distribution, and value-based offerings.
Recent Developments
- In March 2024, Boston Scientific launched the Direxion Microcatheter family, which incorporates a slotted nitinol hypotube for enhanced torqueability and flexibility, according to Boston Scientific. This technology allows for improved control and handling, especially in challenging anatomies. The microcatheter is available in six tip configurations and various lumen sizes.
Market Concentration and Characteristics
The global microcatheter market shows moderate concentration, with a few multinational players controlling a significant share. Companies like Medtronic, Boston Scientific, and Terumo set industry standards through advanced product lines and global distribution networks. It features high entry barriers due to strict regulatory requirements, complex manufacturing processes, and the need for clinical validation. The market favors firms with strong R&D capabilities and established relationships with hospitals and interventional specialists. Product differentiation, performance reliability, and procedural versatility define competitive success. It remains innovation-driven, with demand focused on precision, safety, and specialty-specific functionality.
Report Coverage
The research report offers an in-depth analysis based on Product, Application, End-user, Product Design and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Clinical trials will extend microcatheter use into targeted drug delivery for solid tumors, increasing demand and therapeutic precision.
- Rising incidence of stroke and aneurysm cases will drive adoption of specialized neurovascular microcatheters.
- Manufacturers will integrate high-performance polymers and hydrophilic coatings for improved trackability and reduced friction.
- Next‑generation steerable and dual‑lumen catheters will support complex procedures and enhance procedural efficiency.
- Image‑guided systems such as IVUS, OCT, and DSA will become standard in catheter compatibility, improving procedural accuracy.
- Growing outpatient surgical center volumes will increase preference for compact, single-use microcatheter systems.
- Healthcare expansion in Asia, Latin America, and Africa will elevate microcatheter adoption in non‑metropolitan regions.
- Expanded reimbursement policies and regulatory clarity will encourage more hospitals to include microcatheters in standard protocols.
- Smart catheters with embedded sensors and real‑time feedback capabilities will gain traction in interventional suites.
- Global device manufacturers will seek co‑development agreements with specialty biotech firms to accelerate innovation and market reach.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected size of the global microcatheter market by 2032 and its growth rate?
Which technologies are advancing microcatheter performance in clinical practice?
Which region dominates the global microcatheter market?
Who are the key players in the global microcatheter market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Microcatheters Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Microcatheters Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 2,144.82 million → 2032: USD 3,182.70 million)
- 2.1.2 Volume & Revenue – Global Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Microcatheters Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Microcatheters Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Microcatheters Market Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Microcatheters Market Drivers
- 3.3 Microcatheters Market Restraints & Challenges
- 3.4 Microcatheters Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Microcatheters Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Microcatheters Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Microcatheters category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Microcatheters Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Region – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Priority market opportunity scorecards reflect the geographic scope and strategic relevance of the study. Listed markets are indicative and may be adapted to the industry.
Chapter 5. Microcatheters Cross-Border Trade & Market Access Analysis
- 5.1 International Trade & Cross-Border Activity Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024) (Volume Where Applicable)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter applies where cross-border trade or delivery is relevant to Microcatheters. Goods, services, and digital offerings are assessed using applicable classifications and transaction measures. Import-export volumes, trade balances, and route analyses are included only where meaningful to the market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Microcatheters Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Microcatheters Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company (Volume Where Applicable)
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Global Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Microcatheters Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Microcatheters (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Microcatheters
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Microcatheters Market – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share (Volume Where Applicable)
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region (Volume Where Applicable)
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. North America Microcatheters Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Microcatheters Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Microcatheters Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Microcatheters Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Microcatheters Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Microcatheters Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Microcatheters Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
