
Market Overview:
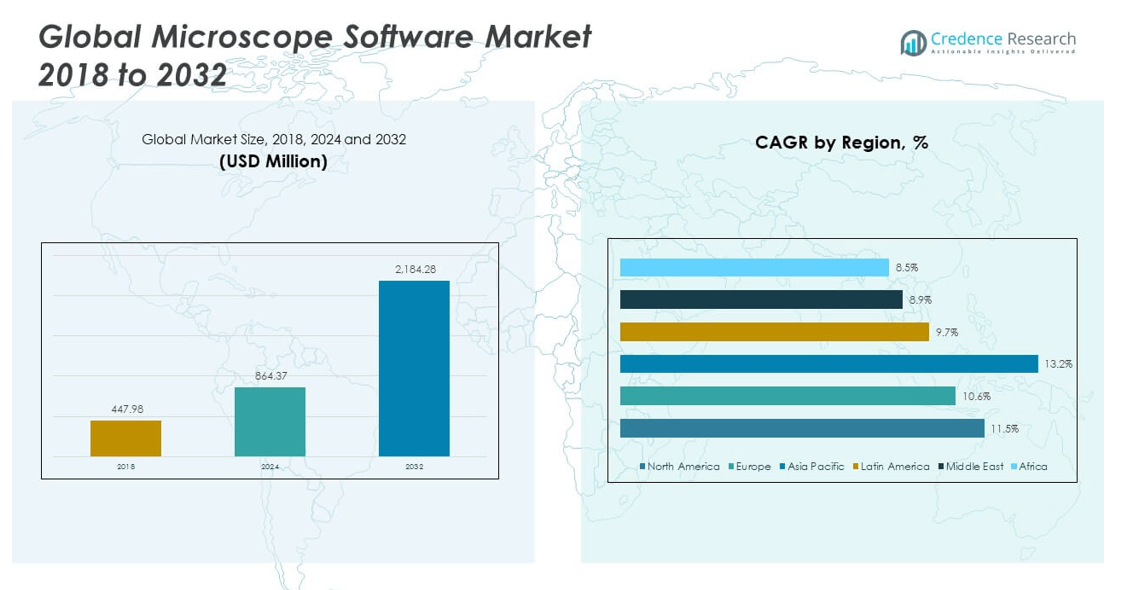
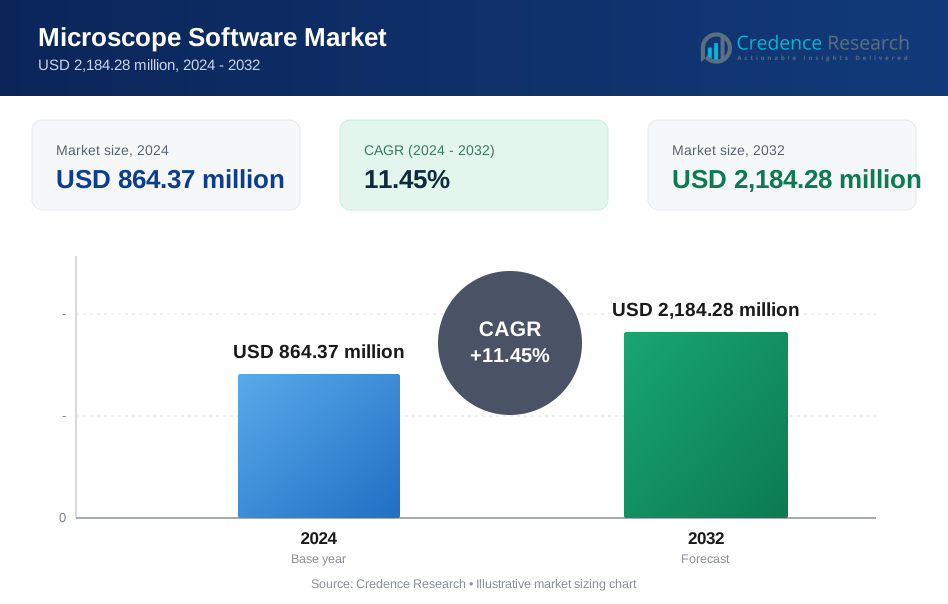
The Global Microscope Software Market size was valued at USD 447.98 million in 2018 to USD 864.37 million in 2024 and is anticipated to reach USD 2,184.28 million by 2032, at a CAGR of 11.45% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Microscope Software Market Size 2024 | USD 864.37 million |
| Microscope Software Market, CAGR | 11.45% |
| Microscope Software Market Size 2032 | USD 2,184.28 million |
The market is driven by increasing demand for high-precision imaging solutions in life sciences, nanotechnology, and material research. Rising adoption of integrated software platforms enhances workflow efficiency and data management. Growth in research and development activities, coupled with the need for automation and advanced analytics, further stimulates market expansion. Strong industrial applications in semiconductors, pharmaceuticals, and academic institutions continue to fuel software deployment and innovation.
North America and Europe lead the market due to extensive research infrastructure, well-established laboratories, and strong industrial presence. Asia Pacific shows rapid growth, driven by rising investments in scientific research, increasing academic institutions, and expanding industrial manufacturing. Emerging markets in Latin America, the Middle East, and Africa are witnessing gradual adoption due to growing awareness, government initiatives, and infrastructure development. This geographic diversity supports broad market expansion and sustained global demand
Market Insights:
- The Global Microscope Software Market was valued at USD 447.98 million in 2018, USD 864.37 million in 2024, and is projected to reach USD 2,184.28 million by 2032, growing at a CAGR of 11.45%.
- North America leads with 43.7% share in 2024, supported by advanced research infrastructure and strong biotechnology investments.
- Europe holds 26.6% share, driven by robust pharmaceutical R&D and digital healthcare adoption, while Asia Pacific accounts for 20.8% with rising academic and industrial demand.
- Asia Pacific is the fastest-growing region, benefiting from expanding research infrastructure, government support, and cost-effective manufacturing strength.
- Life science dominates application growth, while integrated software drives higher adoption due to its efficiency in workflow and data management.
Market Drivers
Growing Integration of Advanced Imaging Solutions in Life Sciences and Clinical Diagnostics
The Global Microscope Software Market is expanding with the growing use of high-resolution imaging in life sciences, medical diagnostics, and pharmaceutical research. Research institutions rely on software to analyze large image datasets accurately, supporting drug discovery and disease diagnosis. Clinical laboratories demand advanced visualization and analysis tools to detect complex cellular structures. It enables automation of imaging tasks, improving efficiency in medical research. Pharmaceutical companies apply these solutions to accelerate product development and reduce laboratory errors. Rising dependence on accurate data interpretation makes microscope software indispensable. Demand continues to grow with increasing investments in medical R&D and clinical trials.
- For instance, in March 2025, ZEISS introduced upgrades to its ZEN Core software, adding robust database connectivity that enables integrated data management across instruments, laboratories, and locations, supporting efficient organization and retrieval of microscopy imaging results.
Rapid Adoption of Artificial Intelligence and Machine Learning in Imaging Applications
Artificial intelligence and machine learning drive demand by transforming microscope imaging into automated, precise, and predictive processes. It reduces human error, enhances efficiency, and delivers consistent analysis outcomes. Integration of AI algorithms allows automated detection of irregularities in samples and improved diagnostic accuracy. Academic institutions and biotechnology companies invest in AI-enabled platforms to achieve better results in cancer research, infectious disease monitoring, and genetic analysis. Rising importance of predictive analytics in microscopy further enhances its relevance. Governments support AI-led healthcare and biosciences projects, fueling adoption. This driver highlights the shift toward automation-driven microscopy in multiple industries.
- For example, in August 2024, Nikon Instruments released an update for its ECLIPSE Ji imaging system (NIS-Elements ver. 6.10), adding three new assays Cell Cycle-Fucci, Wound Healing, and Neurite Outgrowth to support oncology, neurology, and regenerative medicine research.
Growing Digitalization of Research Workflows Across Academic and Industrial Laboratories
Digitalization of laboratories supports the deployment of microscope software for seamless data management, collaboration, and cloud integration. Research organizations aim to streamline workflow efficiency with software that stores, processes, and shares microscopy data. It creates opportunities for digital collaboration across borders, enabling global research teams to analyze data simultaneously. Laboratories in industrial sectors apply digital tools for materials testing and quality control. Cloud-enabled microscope software enhances accessibility and security for sensitive data. Growing pressure to publish research outcomes faster pushes institutions toward digital platforms. This driver underlines the critical role of digital transformation in market growth.
Expansion of Biotechnology and Pharmaceutical R&D Activities Worldwide
The demand for microscope software is closely linked with increasing pharmaceutical and biotechnology research activities. Companies invest heavily in advanced platforms to analyze cellular interactions, molecular pathways, and drug responses. It accelerates product development timelines while maintaining high accuracy in testing. Regulatory agencies encourage use of validated and automated systems for compliance in trials. Growth in biologics and personalized medicine drives higher adoption of microscope software for real-time monitoring of drug effects. Academic partnerships with industry players further enhance adoption. Expanding R&D pipelines globally contribute strongly to market growth and long-term sustainability.
Market Trends
Rising Focus on Cloud-Based Microscope Software for Remote Research Access
The Global Microscope Software Market is experiencing a shift toward cloud-based deployment for seamless collaboration. Researchers increasingly require remote access to data and images, supported by cloud infrastructure. It enables storage of large datasets while ensuring data security and accessibility. Universities and research labs adopt subscription-based platforms for cost efficiency and flexibility. Collaborative projects between countries rely on cloud-based microscopy for real-time results. Demand for scalable and secure solutions grows in both academic and industrial domains. This trend ensures continuous data availability and supports international research collaborations. Cloud-based models redefine the delivery of microscopy solutions.
- For example, Thermo Fisher Scientific’s Connect Platform offers secure cloud-based storage connected to lab instruments, letting users access data from anywhere, share files across peers, and analyze scientific datasets using built-in apps. The platform integrates with legacy hardware via Connect Transfer, supports remote instrument monitoring, and delivers workflow orchestration tools that unify people, data, and software across the lab environment.
Emergence of Multi-Modal Imaging Platforms for Advanced Research Outcomes
Research institutions demand microscope software that supports integration of multi-modal imaging techniques for more comprehensive results. It allows researchers to combine fluorescence, electron, and confocal microscopy into unified data outputs. This trend enhances the scope of biomedical and material sciences studies. Multi-modal platforms offer advanced insights into cellular behavior, disease progression, and material properties. Integration reduces the need for separate imaging software, creating cost and efficiency benefits. Companies invest in software that enables synchronization of different modalities with minimal technical issues. Researchers gain broader perspectives and improved decision-making from integrated imaging outcomes. This trend supports innovation in microscopy.
Growing Use of Virtual Microscopy in Education and Research Training Programs
Virtual microscopy adoption is rising across universities and medical schools for teaching and training purposes. It offers digital slides accessible on devices, replacing traditional glass slide methods. The Global Microscope Software Market supports this trend with scalable, user-friendly platforms. Virtual tools enhance interactive learning experiences and reduce the costs of physical sample preparation. Students gain access to standardized datasets that improve knowledge sharing across institutions. Training programs benefit from faster evaluation processes and reproducible learning outcomes. Virtual microscopy aligns with digital education strategies, creating demand across global academic sectors. This trend strengthens future adoption of microscope software.
- For example, in 2022, Evident (formerly Olympus) introduced the SZX-AR1 augmented reality system, a module that retrofits existing SZX series stereo microscopes. The AR-1 system projects instructions, reference images, videos, and manuals directly into the microscope’s field of view to assist manufacturing, assembly, and training tasks. It enables assemblers to work without removing their eyes from the oculars, reducing errors and improving efficiency.
Integration of Augmented Reality and 3D Visualization in Microscope Software
Microscope software providers are developing augmented reality and 3D visualization features to enhance research experiences. It supports scientists in viewing samples in immersive formats for deeper analysis. 3D visualization allows reconstruction of complex cellular or material structures. Medical researchers use AR-enabled tools for advanced surgical planning and diagnostics. Software companies emphasize compatibility with AR devices and advanced imaging tools. This trend expands applications beyond laboratories into clinical practices. Industry players explore AR integration for training and simulation purposes. Adoption of immersive technologies reshapes microscopy, making it more intuitive and engaging for researchers.
Market Challenges Analysis
High Costs of Advanced Microscope Software and Integration with Legacy Systems
The Global Microscope Software Market faces challenges due to the high cost of advanced software solutions. Institutions with limited budgets struggle to invest in platforms equipped with AI, cloud, and 3D visualization features. Integration with existing legacy systems often creates technical issues, leading to higher setup costs. It becomes a barrier for small research institutions and laboratories in developing regions. Vendors face pressure to provide scalable solutions without compromising performance. High costs restrict adoption in education sectors where budget limitations are critical. This challenge impacts growth pace, despite rising demand for advanced microscopy applications worldwide.
Complexity of Data Management and Shortage of Skilled Professionals
Managing large microscopy datasets creates challenges for laboratories and institutions across sectors. Researchers struggle to handle storage, processing, and analysis due to the complexity of data structures. The Global Microscope Software Market is also affected by a shortage of skilled professionals trained in AI, digital microscopy, and bioinformatics. It slows down adoption in regions lacking specialized talent. Research centers require advanced training programs to build workforce expertise. Data security concerns further complicate adoption in sensitive industries such as pharmaceuticals. Companies must address user-friendly designs to overcome usability challenges. This issue remains a significant obstacle in market expansion.
Market Opportunities
Growing Demand for Personalized Medicine and Advanced Diagnostic Imaging Applications
The Global Microscope Software Market presents opportunities through rising demand for personalized medicine and advanced diagnostics. Healthcare providers adopt software to support precision imaging, enabling tailored treatment plans. It offers clinicians detailed insights into cellular and genetic variations critical for individualized therapies. Pharmaceutical companies focus on targeted therapies requiring real-time monitoring of drug effects. Diagnostic laboratories utilize advanced software for faster detection of diseases. Integration with AI platforms creates opportunities for predictive diagnostics. Growth in genomic and proteomic research boosts reliance on advanced microscope software. This opportunity enhances adoption across healthcare and biomedical industries.
Expansion Potential in Emerging Economies with Increasing Research Infrastructure Investments
Emerging economies are investing significantly in research infrastructure and healthcare modernization. Governments in Asia-Pacific, Latin America, and Middle East regions allocate funds to support biotechnology and life sciences. The Global Microscope Software Market benefits from these investments as laboratories expand capabilities. Universities establish new research programs with advanced imaging tools to attract global collaborations. Rising contract research organizations demand scalable, cost-effective solutions. It creates opportunities for software vendors to expand market presence. Infrastructure development and international partnerships fuel adoption in emerging markets. This opportunity positions these regions as future growth centers for microscope software adoption.
Market Segmentation Analysis:
The Global Microscope Software Market is segmented by type of software, type of microscopes, and application, each driving unique opportunities.
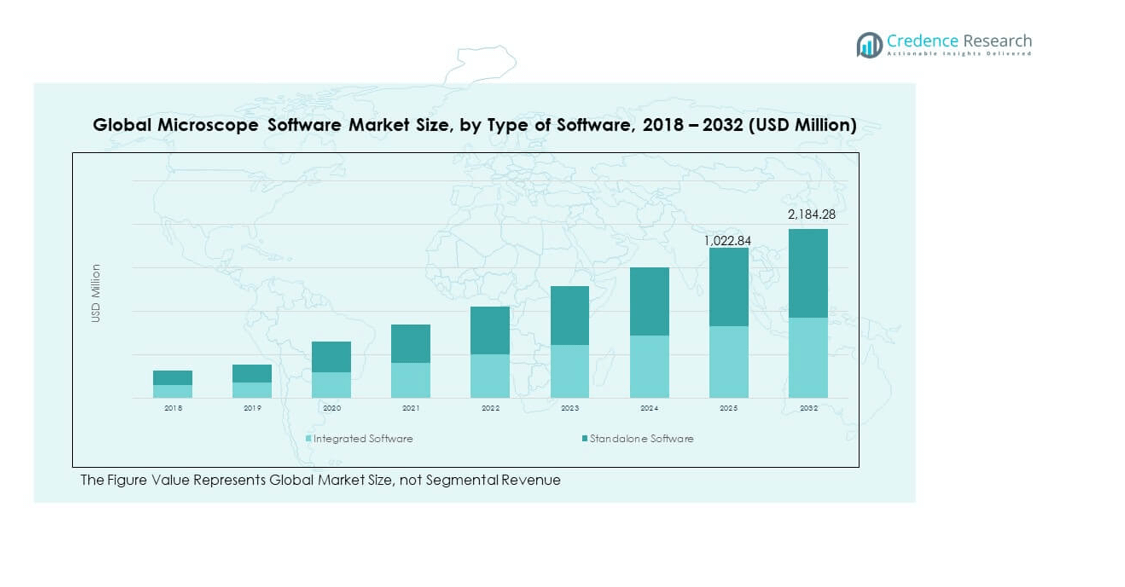
By type of software, integrated software dominates due to its ability to provide comprehensive control, data analysis, and automation across multiple microscope platforms. Standalone software remains significant in laboratories requiring specialized functionality and cost-efficient deployment.
- For example, Leica Microsystems’ Application Suite X (LAS X) integrates confocal, widefield, stereo, super-resolution, and light-sheet instruments in one software platform. It supports complex fluorescence analysis, multi-channel acquisition, and high-speed 3D rendering.
By type of microscopes, optical microscopes hold a substantial share due to their widespread use in research, education, and routine laboratory analysis. Electron microscopes show strong adoption in high-precision industrial and life science applications where detailed imaging is critical. Scanning probe microscopes cater to advanced nanotechnology and material science research, while other microscope types serve niche industrial and academic requirements, supporting market diversity.
- For example, the Olympus FV4000 confocal system offers ten laser lines from 405 nm to 785 nm, supports up to six simultaneous imaging channels, and includes environmental control modules for live-cell imaging. It delivers fast imaging via a resonant scanner and uses the SilVIR next-generation detector to improve sensitivity and image quality across fixed and live samples.
By application, life science leads the market, driven by demand for diagnostics, drug discovery, and biomedical research. Material science and nanotechnology applications are expanding, propelled by advanced imaging needs and industrial innovations. Semiconductor applications are growing due to precision requirements in microfabrication and quality control. Other applications, including environmental research and forensic analysis, contribute steadily to market growth.
Segmentation:
By Type of Software
- Integrated Software
- Standalone Software
By Type of Microscopes
- Optical Microscopes
- Electron Microscopes
- Scanning Probe Microscopes
- Other Microscopes
By Application
- Material Science
- Nanotechnology
- Life Science
- Semiconductors
- Others
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Southeast Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East
- GCC Countries
- Israel
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
Regional Analysis:
North America
The North America Global Microscope Software Market size was valued at USD 197.66 million in 2018 to USD 377.47 million in 2024 and is anticipated to reach USD 956.49 million by 2032, at a CAGR of 11.5% during the forecast period. North America holds 43.7% market share in 2024, making it the largest regional contributor. The region benefits from advanced research infrastructure, strong biotechnology investments, and high adoption of AI-driven imaging platforms. It supports innovation through collaborations between universities, pharmaceutical firms, and technology providers. The presence of leading microscope manufacturers and software developers strengthens competitiveness. Growing demand in clinical diagnostics and personalized medicine drives adoption. It also benefits from government funding supporting healthcare and life sciences research. North America remains a dominant hub for technology integration in microscope software.
Europe
The Europe Global Microscope Software Market size was valued at USD 123.75 million in 2018 to USD 229.93 million in 2024 and is anticipated to reach USD 546.08 million by 2032, at a CAGR of 10.6% during the forecast period. Europe accounts for 26.6% market share in 2024, supported by robust pharmaceutical R&D and established healthcare systems. Leading countries such as Germany, UK, and France drive innovation through investments in advanced imaging technologies. It benefits from collaborative EU research projects that promote digital microscopy adoption. Demand for nanotechnology and semiconductor applications fuels growth in academic and industrial laboratories. Universities and research institutions prioritize integrated platforms that streamline workflows. Expansion of healthcare digitization supports new opportunities for software providers. Europe sustains steady growth through regulatory alignment and cross-border scientific partnerships.
Asia Pacific
The Asia Pacific Global Microscope Software Market size was valued at USD 86.22 million in 2018 to USD 180.30 million in 2024 and is anticipated to reach USD 515.99 million by 2032, at a CAGR of 13.2% during the forecast period. Asia Pacific contributes 20.8% market share in 2024, reflecting its rapid expansion. Countries such as China, Japan, and India invest heavily in life sciences research and healthcare infrastructure. It benefits from rising demand in academic institutions, contract research organizations, and semiconductor industries. The growing presence of local manufacturers strengthens adoption across emerging markets. Government initiatives support biotechnology and nanotechnology advancements. Increasing partnerships between Asian and global firms expand the software ecosystem. Asia Pacific emerges as the fastest-growing market, supported by innovation and cost advantages.
Latin America
The Latin America Global Microscope Software Market size was valued at USD 21.16 million in 2018 to USD 40.32 million in 2024 and is anticipated to reach USD 90.18 million by 2032, at a CAGR of 9.7% during the forecast period. Latin America holds 4.6% market share in 2024, with Brazil leading regional demand. It benefits from expanding healthcare modernization and academic research initiatives. Universities and laboratories adopt digital imaging solutions to support clinical and life sciences research. Growth in pharmaceuticals and biotechnology encourages the use of advanced microscopy platforms. It faces cost-related barriers but shows improvement through regional collaborations. Multinational companies expand partnerships in the region to address growing opportunities. Latin America develops steadily with an emphasis on strengthening infrastructure.
Middle East
The Middle East Global Microscope Software Market size was valued at USD 11.80 million in 2018 to USD 20.69 million in 2024 and is anticipated to reach USD 43.55 million by 2032, at a CAGR of 8.9% during the forecast period. The region represents 2.4% market share in 2024, showing gradual adoption. GCC countries drive demand through rising healthcare investments and expanding biotechnology sectors. Israel emerges as a technology hub with strong academic and clinical research adoption. It benefits from government initiatives supporting digital transformation in healthcare. Academic institutions in Turkey and Saudi Arabia invest in nanotechnology and semiconductor-related research. Rising collaborations with global technology providers expand local opportunities. The Middle East continues to grow steadily with a focus on advanced research applications.
Africa
The Africa Global Microscope Software Market size was valued at USD 7.39 million in 2018 to USD 15.66 million in 2024 and is anticipated to reach USD 31.97 million by 2032, at a CAGR of 8.5% during the forecast period. Africa holds 1.8% market share in 2024, making it the smallest contributor. It experiences gradual adoption driven by South Africa and Egypt. Limited research infrastructure and budget constraints slow widespread use of microscope software. It benefits from international collaborations and donor-supported healthcare research programs. Universities in key countries expand training programs to build local expertise. The growing emphasis on public health research increases reliance on digital imaging. Adoption in material sciences and applied research also supports growth. Africa continues to show untapped potential with steady expansion.
Key Player Analysis:
- Olympus
- Thermo Fisher Scientific
- Hitachi High-Tech
- JEOL
- Carl Zeiss
- Nikon
- Oxford Instruments
Competitive Analysis:
The Global Microscope Software Market is characterized by strong competition among established multinational corporations and emerging regional players. Leading companies such as Olympus, Thermo Fisher Scientific, Carl Zeiss, Nikon, and Hitachi High-Tech focus on advanced imaging technologies, AI integration, and digital workflow solutions. It is shaped by strategic moves including mergers, acquisitions, and partnerships aimed at expanding global reach and product portfolios. Firms invest in research and development to enhance functionality, improve user experience, and support cloud-based platforms. Competition intensifies with growing demand from life sciences, nanotechnology, and semiconductor sectors. Regional players strengthen their presence by offering cost-effective, customizable solutions for academic and clinical use. Market leaders maintain dominance through innovation, brand strength, and extensive distribution networks, while new entrants seek opportunities in emerging economies. This competitive environment drives continuous product upgrades and service diversification to meet evolving research and diagnostic needs.
Recent Developments:
- In September 2025, Olympus announced the U.S. launch of the VISERA S OTV-S500 imaging platform, integrating advanced diagnostic capabilities for ENT and urology applications, with built-in imaging flexibility and enhanced compatibility for clinical workflows.
- In April 2025, ZEISS Research Microscopy Solutions launched the ZEN core software suite for all its scanning electron microscopes (SEMs), including focused ion beam SEMs. This universal platform now enables streamlined control over imaging, analytics, and multi-modal workflows for both light and electron microscopes, offering intuitive operation through a central Navigation Workspace.
Report Coverage:
The research report offers an in-depth analysis based on Type of Software, Type of Microscopes, Application, It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Growing integration of AI and machine learning will enhance automation and reduce diagnostic errors.
- Rising adoption of cloud-based platforms will strengthen global collaboration in research and diagnostics.
- Expansion of virtual microscopy in education will create long-term demand from academic institutions.
- Increased focus on multi-modal imaging will improve accuracy in life sciences and material research.
- Strong demand from nanotechnology and semiconductor industries will widen industrial applications.
- Government funding and healthcare digitization programs will accelerate adoption in developed regions.
- Emerging economies will expand market opportunities through investments in research infrastructure.
- Rising emphasis on personalized medicine will drive reliance on advanced imaging software.
- Strategic mergers and collaborations among leading firms will expand product portfolios and reach.
- Continuous innovation in 3D visualization and AR integration will reshape user experience and engagement.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Microscope Software Market?
At what Compound Annual Growth Rate is the Global Microscope Software Market projected to grow between 2024 and 2032?
What factors are driving the growth of the Microscope Software Market?
What are the key segments within the Microscope Software Market?
Who are the major players in the Microscope Software Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Microscope Software Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Microscope Software Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 864.37 million → 2032: USD 2,184.28 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Microscope Software Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Microscope Software Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Microscope Software Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Microscope Software Market Drivers
- 3.3 Microscope Software Market Restraints & Challenges
- 3.4 Microscope Software Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Microscope Software Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Microscope Software Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Microscope Software category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Microscope Software Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Microscope Software Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Microscope Software market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Microscope Software Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Microscope Software Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Microscope Software Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Microscope Software (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Microscope Software Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Microscope Software Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Microscope Software Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Microscope Software Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Microscope Software Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Microscope Software Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Microscope Software Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Microscope Software Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Microscope Software Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
