
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Middle East and Africa Underground Mining Equipment Market Size 2023 | USD 950.79 million |
| Middle East and Africa Underground Mining Equipment Market, CAGR | 2.79% |
| Middle East and Africa Underground Mining Equipment Market Size 2032 | USD 1,219.81 million |
Market Overview
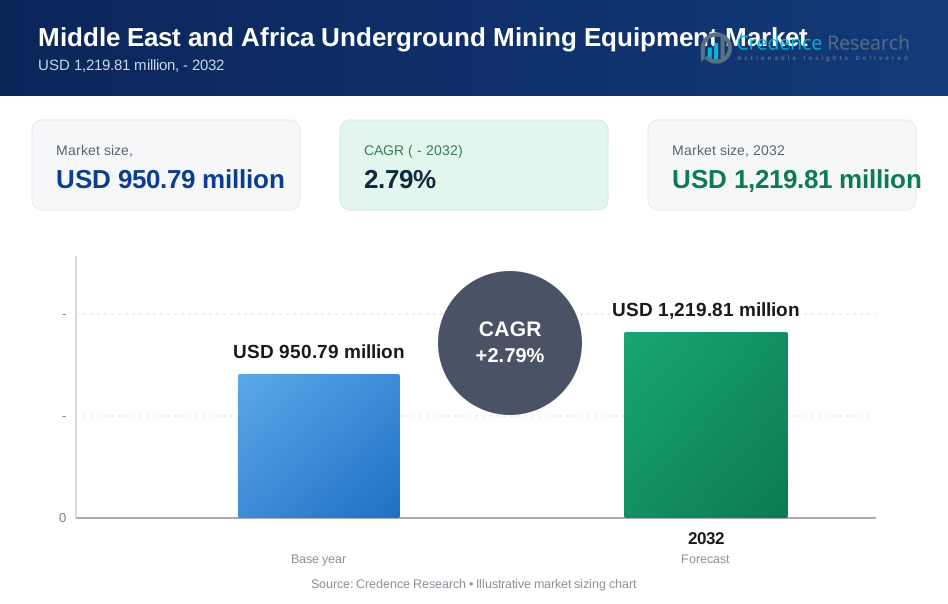
The Middle East and Africa Underground Mining Equipment Market is projected to grow from USD 950.79 million in 2023 to an estimated USD 1,219.81 million by 2032, registering a CAGR of 2.79% from 2024 to 2032. This growth reflects increasing investment in mining projects and infrastructure across the region, driven by the rising global demand for critical minerals and energy resources.
Key drivers of this growth include the region's abundant reserves of minerals such as gold, diamonds, platinum, and copper, as well as the rising demand for automation and efficiency in mining operations. Trends such as the adoption of electric and autonomous mining equipment are reshaping the market landscape. Additionally, increasing emphasis on worker safety and environmental sustainability is prompting mining companies to invest in advanced underground equipment.
Geographically, South Africa remains a prominent player due to its vast reserves and well-established mining sector, while countries like Ghana and the Democratic Republic of Congo are emerging as growth hotspots. Key market players include Caterpillar Inc., Komatsu Ltd., Sandvik AB, and Epiroc AB, which dominate the market with their innovative product offerings and robust service networks. These companies continue to expand their presence through strategic partnerships and investments in the region's mining projects, reinforcing their leadership.
Market Drivers
Abundance of Mineral Resources in the Region
The Middle East and Africa (MEA) region is home to vast reserves of high-demand minerals, including gold, platinum, diamonds, copper, and rare earth elements. Countries like South Africa, Ghana, and the Democratic Republic of Congo (DRC) have established themselves as leading mining hubs, attracting significant investments in exploration and extraction activities. For instance, South Africa is renowned for its rich deposits of gold and platinum, while Ghana is recognized for its significant gold reserves, and the DRC is a leading source of cobalt and diamonds. These countries have attracted substantial foreign investments aimed at exploring and extracting these valuable resources, which are essential for various global industries such as electronics and renewable energy. The increasing international demand for these minerals has led mining companies to enhance their underground operations, thereby escalating the need for specialized underground mining equipment. Additionally, many mining companies are shifting their focus to deeper reserves, necessitating advanced underground technologies to improve efficiency and safety.
Technological Advancements in Mining Equipment
The integration of advanced technologies in underground mining equipment is a significant driver of market growth. Innovations such as automation, electrification, and remote-controlled machinery are enhancing the efficiency, precision, and safety of mining operations. For instance, companies are increasingly implementing automated drilling rigs and remote-controlled machinery to improve operational efficiency. Electric mining equipment is becoming more prevalent due to its ability to lower operational costs and minimize environmental impact. Furthermore, autonomous vehicles are being deployed to perform tasks in hazardous environments, reducing the risk to human workers while enhancing productivity and extending the lifecycle of mining equipment.
Rising Focus on Worker Safety and Environmental Sustainability
The mining sector in the MEA region is increasingly emphasizing worker safety and environmental sustainability, creating a robust demand for advanced underground equipment. Traditional mining techniques often expose workers to significant health and safety risks. Modern underground mining equipment, equipped with features such as real-time monitoring, automated hazard detection, and enhanced ventilation systems, helps mitigate these risks. For instance, modern underground mining equipment now includes features like automated hazard detection systems and real-time monitoring technologies that significantly enhance worker safety. Regulatory changes are also encouraging mining companies to adopt cleaner technologies, aligning with global sustainability goals aimed at reducing emissions and protecting natural ecosystems. This growing emphasis on safety and sustainability is driving the demand for advanced underground mining equipment that meets these evolving standards.
Favorable Government Policies and Initiatives
Governments across the Middle East and Africa are playing an instrumental role in fostering the growth of the underground equipment market through supportive policies and strategic initiatives. Many governments are actively incentivizing infrastructure and mining projects by offering tax incentives, subsidies, and public-private partnerships to drive economic growth and development. The GCC countries, for example, are heavily investing in infrastructure diversification as part of their efforts to reduce dependency on oil revenues, thereby creating demand for underground construction and associated equipment. Additionally, regulatory frameworks that promote sustainable and safe mining and tunneling practices are further propelling the adoption of modern equipment. Policies aimed at reducing environmental impact and ensuring safety compliance in mining operations are encouraging stakeholders to invest in technologically advanced equipment, fostering overall market growth.
Market Trends
Shift Toward Automation and Electrification in Mining Operations
A significant trend shaping the Middle East and Africa underground mining equipment market is the adoption of automation and electrification. Mining companies are increasingly integrating automated systems to enhance operational efficiency, reduce costs, and improve worker safety in underground environments. For instance, autonomous haulage systems (AHS) are being implemented to transport materials without human intervention, which not only minimizes the risk of accidents but also optimizes the flow of operations by allowing continuous movement of resources. Additionally, remote-controlled equipment is becoming prevalent, enabling operators to manage machinery from a safe distance, thereby reducing human exposure to hazardous conditions. Real-time monitoring technologies are also being adopted to track equipment performance and operational parameters, facilitating proactive maintenance and enhancing overall productivity. Simultaneously, the electrification of underground equipment is gaining momentum as companies aim to meet stricter environmental regulations and reduce carbon emissions. Electric mining vehicles and equipment offer reduced operational costs, lower energy consumption, and minimized maintenance compared to diesel-powered alternatives, aligning with the industry's sustainability goals.
Increased Focus on Sustainability and Eco-Friendly Mining Practices
The Middle East and Africa region is witnessing a growing emphasis on sustainable mining practices, driven by global environmental standards and regional regulations. Mining companies are adopting advanced underground mining equipment designed to minimize environmental impact. For instance, equipment with energy-efficient technologies, such as advanced filtration systems and electric drives, is being deployed to reduce emissions and manage waste effectively. Additionally, companies are investing in renewable energy sources to power their operations; for example, integrating solar or wind energy into their mining activities has become a common practice among progressive mining firms. This trend is not only enhancing the environmental profile of mining companies but also improving their operational efficiency and reputation among stakeholders. Furthermore, these initiatives reflect the increasing alignment of the region’s mining industry with international sustainability frameworks, such as the United Nations’ Sustainable Development Goals (SDGs).
Market Restraints and Challenges
High Initial Costs and Limited Access to Advanced Technologies
The high capital expenditure associated with acquiring and deploying advanced underground mining equipment poses a significant restraint for market growth in the Middle East and Africa region. Many mining companies, especially small- and medium-sized enterprises, struggle to afford cutting-edge technologies due to limited budgets. These costs include not only the procurement of sophisticated equipment but also expenses related to training personnel and maintaining complex machinery. Furthermore, access to advanced technologies remains a challenge in remote mining regions, where infrastructure and supply chain networks are underdeveloped. This lack of access hampers the adoption of automation, electrification, and other modern mining innovations, leaving several operators reliant on traditional methods that are less efficient and more environmentally damaging.
Regulatory and Environmental Compliance Challenges
Stringent regulatory frameworks and environmental policies are becoming increasingly prominent in the region, posing challenges for mining companies. Governments and international organizations are implementing stricter emissions standards and safety regulations to ensure sustainable mining practices. While these measures are essential for environmental preservation and worker safety, they often require substantial investments in compliance, such as upgrading equipment or modifying operational practices. For companies operating on tight margins, these additional costs can be prohibitive. Moreover, navigating diverse regulatory environments across different countries in the region adds complexity, particularly for multinational mining corporations. Non-compliance can lead to fines, operational delays, or project cancellations, further hindering market growth.
Market Segmentation Analysis
By Product Type
The Middle East and Africa Underground Equipment Market features a diverse range of product types, each essential for specific mining and tunneling operations. Mining loaders are widely used for hauling materials, enhancing productivity and optimizing material handling in confined underground spaces. Mining trucks, designed for heavy-duty operations, are valued for their durability and capacity to transport large loads efficiently and safely in extensive mining projects. Mining drills, critical for both soft and hard rock mining, benefit from innovations in automated and electric drilling technologies that improve precision and reduce downtime. Mining bolters, which provide structural reinforcement in unstable areas, have gained importance with the rising focus on worker safety. Lastly, mining shearers, mainly used in soft rock mining for coal extraction, are being enhanced with technological advancements to improve cutting efficiency and operational safety.
By Mining Technique
The underground equipment market in the Middle East and Africa is segmented by mining technique into soft rock mining and hard rock mining. Soft rock mining, which involves extracting softer minerals like coal, potash, and gypsum, requires specialized equipment such as shearers and continuous miners, particularly in regions rich in these resources. In contrast, hard rock mining focuses on the extraction of tougher minerals, including gold, diamonds, and metal ores, and relies on robust equipment like drills, bolters, and loaders designed to withstand the more challenging conditions associated with harder mineral deposits.
Segments
Based on Product Type
- Mining Loaders
- Mining Trucks
- Mining Drills
- Mining Bolters
- Mining Shearer
Based on Mining Technique
- Soft Rock Mining
- Hard Rock Mining
Based on End User
- Mining Operators
- Rental Service Providers
Based on Region
- Middle East
- Africa
Regional Analysis
Middle East (28%):
The Middle East accounts for approximately 28% of the market share in 2023, driven by efforts to diversify economies away from oil dependence. Countries like Saudi Arabia and the United Arab Emirates (UAE) are spearheading this shift, investing heavily in mining as part of broader economic transformation plans. Saudi Arabia, under its Vision 2030 initiative, is positioning itself as a mining hub by exploiting its untapped reserves of gold, phosphate, and bauxite. Similarly, the UAE is leveraging its advanced infrastructure to attract global mining investments.
Africa (72%)
Africa dominates the regional market, accounting for approximately 72% of the total market share in 2023. This significant contribution is attributed to the continent's rich reserves of minerals such as gold, platinum, copper, diamonds, and rare earth elements. South Africa remains the largest market within the region due to its well-established mining industry and abundant resources. The country has a robust demand for underground mining equipment, driven by extensive gold and platinum mining operations.
Key players
- Sandvik AB
- Epiroc AB
- Caterpillar Inc.
- Komatsu Ltd.
- Atlas Copco AB
- Volvo Group
- Doosan Infracore
- Hitachi Construction Machinery Co., Ltd.
- Liebherr Group
- Terex Corporation
Competitive Analysis
The Middle East and Africa Underground Mining Equipment Market is highly competitive, with leading players employing strategic initiatives to maintain their market positions. Sandvik AB and Epiroc AB dominate with their advanced underground mining solutions, emphasizing automation, electrification, and sustainability. Caterpillar Inc. and Komatsu Ltd. leverage their global presence and innovative equipment portfolios, catering to diverse mining needs. Atlas Copco AB, known for its high-performance drilling and rock excavation solutions, strengthens its foothold through cutting-edge technology and efficient after-sales services. Volvo Group and Doosan Infracore focus on durability and operator safety, providing robust heavy machinery for underground operations. Meanwhile, Hitachi Construction Machinery Co., Ltd., Liebherr Group, and Terex Corporation emphasize customization and reliability to meet regional demands. These companies compete on technology, sustainability, and operational efficiency while investing in strategic partnerships and local manufacturing to capitalize on the region's growing mining infrastructure investments.
Recent Developments
- In September 2024, Caterpillar showcased new mining technologies at MINExpo 2024, including Cat Dynamic Energy Transfer system and battery-electric underground loaders.
- In July 2024, Doosan secured multiple orders in Middle East and Africa including:
- 27 excavators and wheel loaders for a mining company in Oman
- 35 excavators for a construction company in Qatar
- 35 excavators and wheel loaders in Morocco
- 20 excavators for gold mines in Ghana
- In July 2024, Komatsu completed acquisition of GHH Group, expanding its underground mining equipment offerings with factories in Southern Africa.
- In May 2024, HD Hyundai Infracore (formerly Doosan Construction) established new African office in Ghana and secured contracts for 29 machines in Angola.
- In March 2024, Liebherr-Aerospace participated in MRO Middle East 2024 in Dubai, showcasing customer service solutions.
- In January 2024, Hitachi Construction Machinery launched next-generation ZAXIS-7G excavator series in Muscat, Oman.
Market Concentration and Characteristics
The Middle East and Africa Underground Mining Equipment Market is moderately concentrated, with a mix of global giants and regional players competing for market share. Key players such as Sandvik AB, Epiroc AB, Caterpillar Inc., and Komatsu Ltd. dominate due to their technological advancements, extensive product portfolios, and strong distribution networks. The market is characterized by increasing demand for automation, electrification, and sustainable solutions, aligning with global mining trends. While larger companies benefit from economies of scale and innovation, smaller and regional players focus on offering cost-effective and customized equipment. Market competition is also influenced by regional infrastructure development, regulatory frameworks, and investment in mining activities. The industry's reliance on advanced technologies, high initial costs, and the need for specialized expertise act as barriers to entry, further shaping the competitive landscape. As the market evolves, partnerships and strategic collaborations are becoming critical for gaining a competitive edge.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Mining Technique, End User, and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market is expected to grow steadily, driven by rising investments in mining infrastructure and the increasing global demand for critical minerals such as gold, copper, and cobalt.
- Countries like South Africa, the Democratic Republic of Congo, and Ghana will continue to dominate mining activities, while emerging hubs such as Saudi Arabia and Tanzania will see accelerated growth.
- Automation, electrification, and remote-controlled mining equipment will gain widespread adoption, enhancing efficiency and safety in underground operations.
- The demand for eco-friendly mining equipment is anticipated to increase as companies align with global environmental standards and strive to reduce carbon footprints.
- Improved infrastructure in key mining regions will enable better access to advanced equipment and technologies, boosting operational capabilities.
- Stricter safety and environmental regulations will drive investments in modern equipment that meets compliance standards, creating opportunities for innovative manufacturers.
- Regional manufacturing of underground mining equipment is likely to grow as companies invest in local production to reduce costs and improve supply chain efficiency.
- Strategic collaborations between global and regional players will shape the competitive landscape, enabling the development of tailored solutions for local markets.
- Real-time monitoring systems, data analytics, and predictive maintenance technologies will become integral to underground mining, improving productivity and reducing operational risks.
- The Middle East's diversification efforts, particularly in Saudi Arabia and the UAE, will unlock new opportunities in mining, contributing to the region’s overall market growth.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Abundance of Mineral Resources
The Middle East and Africa region is rich in high-demand minerals such as gold, platinum, diamonds, copper, and rare earth elements. This abundance attracts significant investments in exploration and extraction, driving demand for advanced underground mining equipment to access deeper and more challenging reserves.
Technological Advancements in Mining Equipment
The integration of automation, electrification, and remote-controlled machinery is enhancing operational efficiency, safety, and precision in underground mining. These innovations are prompting mining companies to upgrade their equipment, fueling market growth.
Rising Focus on Worker Safety and Environmental Sustainability
Stricter safety regulations and environmental standards are pushing mining companies to adopt modern underground equipment with features like real-time monitoring, automated hazard detection, and improved ventilation, supporting safer and more sustainable operations.
Favorable Government Policies and Initiatives
Governments in the region are incentivizing mining and infrastructure projects through tax breaks, subsidies, and public-private partnerships. These supportive policies encourage investment in advanced underground mining equipment and foster market expansion.
Shift Toward Automation and Electrification
Mining operators are increasingly adopting automated and electric equipment to improve productivity, reduce operational costs, and comply with environmental regulations. This trend is accelerating the replacement of traditional machinery with advanced underground solutions.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the market size of the Middle East and Africa underground mining equipment market in 2023 and 2032, and its CAGR?
What are the key drivers of growth in the underground mining equipment market?
Which countries in the region are the major contributors to the market?
What technological advancements are shaping the market?
Who are the leading players in the market, and how are they maintaining their competitive edge?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End User
- 1.2.1 Mining Operators
- 1.2.2 Rental Service Providers
- 1.3 By Product Type
- 1.3.1 Mining Loaders
- 1.3.2 Mining Trucks
- 1.3.3 Mining Drills
- 1.3.4 Mining Bolters
- 1.3.5 Mining Shearer
- 1.4 By Mining Technique
- 1.4.1 Soft Rock Mining
- 1.4.2 Hard Rock Mining
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 950.79 million → 2032: USD 1,219.81 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Middle East and Africa Underground Mining Equipment Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Middle East and Africa Underground Mining Equipment Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Middle East and Africa Underground Mining Equipment Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Middle East and Africa Underground Mining Equipment Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Middle East and Africa Underground Mining Equipment Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Middle East and Africa Underground Mining Equipment Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Middle East and Africa Underground Mining Equipment Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Middle East and Africa Underground Mining Equipment Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 950.79 million → 2032: USD 1,219.81 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Middle East and Africa Underground Mining Equipment Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End User - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Volume Forecast, 2023-2032
- 12.3.5 Base-Year Market Share, 2023
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Mining Operators
- 12.3.7.2 Rental Service Providers
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Product Type - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Volume Forecast, 2023-2032
- 12.4.5 Base-Year Market Share, 2023
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Mining Loaders
- 12.4.7.2 Mining Trucks
- 12.4.7.3 Mining Drills
- 12.4.7.4 Mining Bolters
- 12.4.7.5 Mining Shearer
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Mining Technique - Market Size and Forecast, 2023-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2023-2032
- 12.5.4 Volume Forecast, 2023-2032
- 12.5.5 Base-Year Market Share, 2023
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Soft Rock Mining
- 12.5.7.2 Hard Rock Mining
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Middle East and Africa Underground Mining Equipment End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Middle East and Africa Underground Mining Equipment Geographic Market Outlook, 2023-2032
- 14.1 Regional Market Size and Country-Level Shares, 2023
- 14.2 Country Market Size Comparison, 2023
- 14.3 Country Market Forecasts, 2023-2032
- 14.4 Subregional Industrial and Demand Clusters
- 14.5 Intra-Regional Pricing and Cost Differences
- 14.6 Cross-Border Trade and Supply Networks
- 14.7 Regional Supply and Demand Balances
- 14.8 Country Opportunity Comparison and Prioritization
Note: Every listed country is covered on the structure shown under the first country.
Chapter 15 Middle East and Africa Underground Mining Equipment Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2023-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Middle East and Africa Underground Mining Equipment Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2023
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2023-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Sandvik AB
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Epiroc AB
- 18.4 Caterpillar Inc.
- 18.5 Komatsu Ltd.
- 18.6 Atlas Copco AB
- 18.7 Volvo Group
- 18.8 Doosan Infracore
- 18.9 Hitachi Construction Machinery Co., Ltd.
- 18.10 Liebherr Group
- 18.11 Terex Corporation
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

