
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Middle East Elevator Modernization Market Size 2023 | USD 273.90 million |
| Middle East Elevator Modernization Market, CAGR | 9.82% |
| Middle East Elevator Modernization Market Size 2032 | USD 579.51 million |
Market Overview
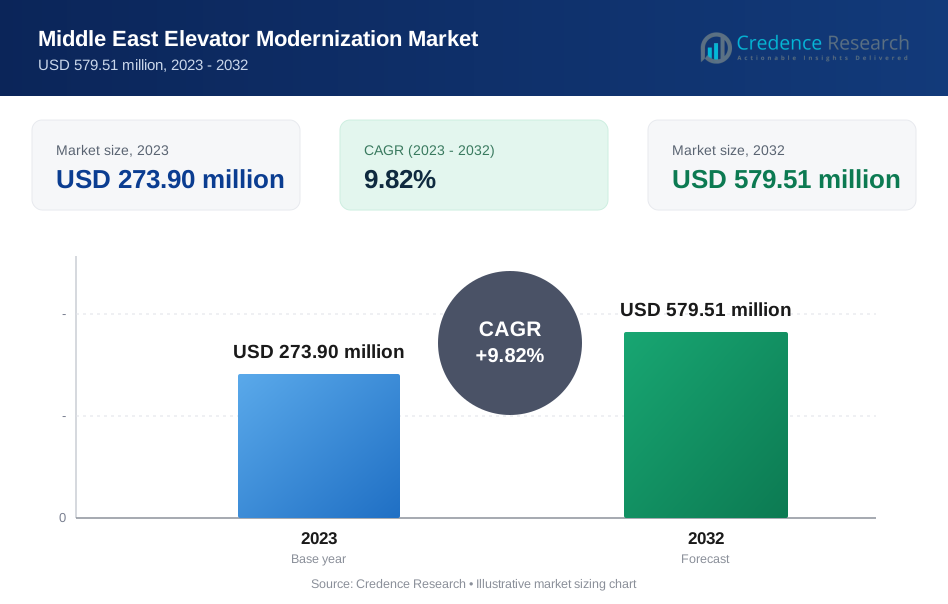
The Middle East elevator modernization market is projected to grow from USD 273.90 million in 2023 to USD 579.51 million by 2032, with a compound annual growth rate (CAGR) of 9.82%.
The Middle East elevator modernization market is driven by increasing urbanization, aging infrastructure, and rising demand for energy-efficient solutions. As cities across the region continue to grow, there is a significant push to upgrade existing elevator systems to meet modern safety, performance, and environmental standards. The focus on sustainability and energy conservation is encouraging the adoption of eco-friendly technologies, such as regenerative drives and smart elevators, which are boosting the market. Additionally, the need for enhanced accessibility and compliance with evolving regulations is prompting building owners to invest in modernization projects. Advancements in IoT and automation are also shaping trends, with connected elevators offering real-time monitoring and predictive maintenance capabilities, improving efficiency and reducing downtime. These drivers, combined with the increasing preference for advanced and comfortable elevator systems, are expected to accelerate the growth of the Middle East elevator modernization market.
The Middle East elevator modernization market is witnessing significant growth, driven by rapid urbanization and a focus on sustainability across the region. Key countries such as the UAE, Saudi Arabia, and Turkey are at the forefront of modernization efforts, with a strong emphasis on improving building efficiency, safety, and energy performance. Major players like Otis Elevator Company, KONE Corporation, Schindler Group, and Thyssenkrupp AG are leading the market with their innovative solutions and advanced technologies, including smart and energy-efficient elevators. Other notable companies such as Mitsubishi Electric, Fujitec Co., Ltd., and Hyundai Elevator are also contributing to the market's growth by offering high-quality products and services. As demand for modernized elevators increases, these key players are expanding their offerings to cater to various building sectors, including residential, commercial, and industrial, ensuring continued progress in the region’s modernization projects.
Market Insights
- The Middle East elevator modernization market was valued at USD 273.90 million in 2023 and is projected to reach USD 579.51 million by 2032, growing at a CAGR of 9.82%.
- Increased demand for energy-efficient, sustainable building solutions is driving the market, with a focus on reducing operational costs and complying with stricter environmental regulations.
- Technological advancements, including smart elevators and predictive maintenance systems, are key market trends that improve operational efficiency and user experience.
- Major players such as Otis, KONE, Schindler, and Thyssenkrupp dominate the competitive landscape, offering advanced solutions and extensive service networks.
- High initial costs for modernization and complex regulatory requirements act as market restraints, limiting investment in some regions.
- The UAE, KSA, and Turkey lead the market, with significant urbanization driving modernization efforts in residential and commercial buildings.
- Growing infrastructure development in Iran and other GCC countries presents emerging opportunities for market expansion.
Market Drivers
Urbanization and Infrastructure Development
The rapid urbanization in the Middle East is one of the primary drivers for elevator modernization. For instance, the Dubai Municipality reported that the city has over 1,000 high-rise buildings, many of which require modernization to meet current safety and performance standards. As cities expand and new high-rise buildings are constructed, the demand for efficient, safe, and advanced elevator systems increases. Aging elevator infrastructure in older buildings requires upgrades to keep pace with the modern needs of urban dwellers and businesses. This trend is particularly evident in metropolitan areas such as Dubai, Riyadh, and Doha, where there is an ongoing effort to improve the functionality and safety of existing buildings, prompting significant investment in elevator modernization projects.
Regulatory Compliance and Safety Standards
The Middle East is seeing stringent regulations surrounding building safety and accessibility, particularly for older infrastructure. For instance, the Saudi Building Code (SBC) has introduced updated guidelines to enhance passenger safety, including stricter requirements for fire safety, earthquake resistance, and accessibility for people with disabilities. Modernizing elevator systems ensures compliance with updated safety codes and regulations, such as those concerning fire safety, earthquake resistance, and accessibility for people with disabilities. Elevators with enhanced safety features and advanced control systems are now essential for meeting these legal requirements. Consequently, building owners and managers are prioritizing modernization to avoid penalties and ensure that their elevators are compliant with the latest standards.
Energy Efficiency and Sustainability
Growing concerns about energy consumption and sustainability are pushing the adoption of energy-efficient technologies in elevator systems. Modernization efforts focus on reducing power usage while maintaining high performance. Regenerative drives, energy-efficient motors, and smart control systems are among the innovations driving this change. These eco-friendly solutions not only lower operational costs but also contribute to the overall sustainability goals of buildings, aligning with the region's increasing focus on green building practices and environmental responsibility.
Technological Advancements and Smart Elevators
Technological advancements, including the integration of IoT, automation, and artificial intelligence, are transforming the elevator modernization landscape in the Middle East. Smart elevators equipped with features such as predictive maintenance, real-time monitoring, and remote diagnostics are gaining popularity. These technologies improve operational efficiency, minimize downtime, and offer a more comfortable and secure experience for users. As digitalization continues to shape the region’s infrastructure, the demand for technologically advanced elevator systems is expected to rise, further driving modernization initiatives.
Market Trends
Rise of Eco-Friendly Solutions
Sustainability is becoming a central theme in the Middle East elevator modernization market. For instance, KONE Corporation's EcoDisc® motor technology reduces energy consumption by up to 70% compared to conventional traction machines. As energy efficiency becomes a critical consideration, there is an increasing adoption of green technologies. Modernization projects are focusing on reducing energy consumption by integrating regenerative drives, LED lighting, and energy-efficient motors into elevator systems. These solutions not only help reduce carbon footprints but also lower operational costs, making them an attractive option for building owners looking to enhance the environmental performance of their properties. This trend aligns with the growing emphasis on sustainable urban development in the region.
Smart Elevator Technologies
The demand for smart elevators is on the rise in the Middle East as buildings increasingly incorporate digital technologies to improve performance and user experience. Modernized elevators are being equipped with IoT-based sensors, real-time monitoring, and predictive maintenance capabilities, allowing for enhanced operational efficiency and reduced downtime. These smart systems enable building managers to track elevator performance, identify potential issues before they arise, and optimize energy usage. The integration of features such as touchless controls, voice recognition, and personalized settings also adds convenience, making elevators more efficient and user-friendly.
Focus on Safety and Accessibility
In response to stricter regulations and heightened awareness around safety, modern elevator systems in the Middle East are incorporating advanced safety features. These include seismic sensors, fire-resistant materials, and emergency communication systems, which help ensure compliance with evolving safety standards. Additionally, the modernization of elevators in older buildings is driven by the need to enhance accessibility for people with disabilities. Elevator systems are now being upgraded with features like wider doors, audio-visual signals, and Braille controls to meet accessibility requirements, ensuring that elevators are safe and usable for all occupants.
Integration of Automation and AI
Automation and artificial intelligence (AI) are transforming elevator modernization trends in the region. The integration of AI-based algorithms enables predictive maintenance, which helps detect faults and reduce the need for manual interventions. Automation technologies, such as destination dispatch systems, are also being incorporated to improve the flow of passengers and optimize elevator usage. These advanced technologies not only improve operational efficiency but also enhance the overall passenger experience by reducing wait times and increasing convenience. As AI and automation continue to advance, they are set to play a pivotal role in the future of elevator modernization in the Middle East.
Market Challenges Analysis
High Initial Costs
One of the significant challenges facing the Middle East elevator modernization market is the high initial investment required for upgrading older systems. For instance, a report by the Dubai Municipality highlighted that modernization projects often involve substantial upfront costs, especially when incorporating advanced technologies such as energy-efficient motors, smart controls, and safety enhancements. For many building owners, especially those managing older properties or those with limited budgets, this can pose a barrier to modernization efforts. The need for specialized equipment and skilled technicians further drives up costs, making it a financial challenge for some property owners to undertake such projects. Despite the long-term benefits, such as reduced operational costs and improved energy efficiency, the high initial costs can delay or deter investment in elevator modernization.
Regulatory and Compliance Barriers
While the region’s evolving safety and accessibility regulations drive the need for modernization, the complexity of compliance can also be a challenge. Navigating the various local and national codes, especially across different countries in the Middle East, can be cumbersome for building owners and managers. In some cases, the regulations may differ from one country to another, further complicating the modernization process. Ensuring that the elevator systems meet the latest standards in terms of fire safety, earthquake resistance, and accessibility can be time-consuming and may require significant coordination with regulatory bodies and certification agencies. The constant evolution of these regulations adds to the uncertainty and complexity, making it challenging for building owners to keep their systems up to date and fully compliant.
Market Opportunities
Growing Demand for Sustainable Building Solutions
As the Middle East region continues to prioritize sustainability in its urban development strategies, there are significant opportunities in the elevator modernization market. With increasing pressure to reduce carbon footprints and improve energy efficiency, building owners are more inclined to invest in modernized elevator systems that offer eco-friendly solutions. The integration of energy-efficient technologies, such as regenerative drives, smart controls, and LED lighting, presents an opportunity for manufacturers and service providers to tap into the growing demand for green building practices. Furthermore, as governments in the region continue to implement stricter environmental regulations, the need for modernization to comply with these standards will drive further market growth.
Technological Advancements and Smart Elevators
The rapid advancement of digital technologies presents another opportunity for the Middle East elevator modernization market. As buildings become more interconnected with IoT and automation systems, the demand for smart elevators is expected to rise. Modernized elevators equipped with predictive maintenance capabilities, real-time monitoring, and AI-powered features can significantly enhance operational efficiency and improve user experience. There is also an opportunity for providers to offer tailored solutions that integrate with existing building management systems, providing building owners with more control and insights into elevator performance. As smart city initiatives gain momentum in the Middle East, the adoption of intelligent elevator systems will likely accelerate, creating opportunities for businesses to innovate and lead in this growing market segment.
Market Segmentation Analysis:
By Type:
The Middle East elevator modernization market is segmented by type into traction systems, hydraulic systems, and machine room-less (MRL) elevators. Traction systems are widely used in high-rise buildings due to their efficiency and ability to handle heavy loads, making them a dominant segment in the modernization market. These systems are increasingly being upgraded with advanced energy-saving features and smart technologies. Hydraulic systems, typically used in low-rise buildings, offer a cost-effective solution for modernization projects where space constraints exist. However, their higher energy consumption compared to traction systems limits their demand for upgrades. MRL elevators, which are gaining popularity due to their space-saving design and energy efficiency, present significant opportunities in the market. As more buildings adopt MRL elevators, especially in commercial and residential applications, the demand for their modernization is expected to grow.
By Application:
The market is also segmented based on application, including residential, commercial, industrial, and institutional buildings. Residential buildings account for a substantial share of the market due to the increasing focus on high-rise apartment complexes in urban areas. As these buildings age, the demand for elevator modernization rises to enhance safety and improve energy efficiency. Commercial buildings, particularly office complexes and shopping malls, represent another key segment, where the need for modernization is driven by the requirement to meet safety standards, enhance passenger experience, and integrate smart technologies. Industrial and institutional buildings, while smaller in comparison, also offer growth opportunities, especially in sectors like healthcare and education, where elevator performance and safety are critical. Each of these segments presents unique challenges and opportunities for modernization service providers, driving innovation and expansion in the Middle East market.
Segments:
Based on Type:
- Traction System
- Hydraulic System
- Machine Room-Less (MRL) Elevators
Based on Application:
- Residential Buildings
- Commercial Buildings
- Industrial Buildings
- Institutional Buildings
Based on Component:
- Control System
- Door System
- Cab Enclosure
- Power Units
- Others
Based on the Geography:
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
Regional Analysis
UAE
The United Arab Emirates (UAE) holds a substantial share of the Middle East elevator modernization market, accounting for approximately 30% of the regional market. This is primarily due to the country's rapid urbanization and the continuous development of high-rise buildings, especially in cities like Dubai and Abu Dhabi. The demand for modernization is driven by aging infrastructure in residential and commercial buildings, along with a strong push for sustainability and energy efficiency. As the UAE focuses on smart technologies, there is an increasing adoption of machine-room-less (MRL) elevators and advanced elevator systems. With the ongoing development of urban spaces and increasing regulatory focus on safety and energy efficiency, the UAE's market share is expected to continue to grow at a strong pace, making it a key player in the Middle East elevator modernization landscape.
KSA
The Kingdom of Saudi Arabia (KSA) holds a significant portion of the market, with a share of approximately 25%. Driven by the nation's Vision 2030 plan, which focuses on large-scale infrastructure projects and urban development, KSA is experiencing growing demand for elevator modernization. The modernization of both residential and commercial buildings is essential to accommodate the increasing population and meet new building regulations. The country's demand for efficient, energy-saving elevator systems is expected to grow, particularly in major cities such as Riyadh, Jeddah, and Mecca. The market share in KSA will likely continue expanding as modernization projects roll out to keep pace with the government’s focus on infrastructure and urban development.
Israel and Turkey
Israel and Turkey represent important but smaller markets in the Middle East elevator modernization landscape. Israel holds around 10% of the market share, driven by the modernization of older infrastructure in cities like Tel Aviv and Jerusalem, focusing on energy-efficient systems and advanced safety features. Turkey, with its blend of new and old infrastructure, contributes around 15% of the market share. The demand for elevator modernization in Turkey is fueled by the country’s focus on improving building safety and meeting international standards in cities such as Istanbul and Ankara. Both Israel and Turkey are poised to continue growing their respective market shares as modernization trends gain momentum, especially with increased investments in technology and sustainability.
Rest of the Middle East
The rest of the Middle East, including countries such as Iran, Qatar, Oman, and Kuwait, collectively hold about 20% of the regional market share. While these regions currently account for a smaller portion of the overall market, the potential for growth is significant. Iran’s urban areas, with their mix of old and new buildings, are increasingly investing in modernization projects. Similarly, other GCC nations, such as Qatar and Kuwait, are expanding their infrastructure and adopting energy-efficient technologies, driving the need for elevator upgrades. As urbanization continues and demand for more efficient, safer elevator systems rises, the market share in these regions is expected to grow steadily, contributing to the overall expansion of the Middle East elevator modernization market.
Key Player Analysis
- Otis Elevator Company
- KONE Corporation
- Schindler Group
- Thyssenkrupp AG
- Mitsubishi Electric Corporation
- Toshiba Elevator and Building Systems Corporation
- Gulf Elevators & Escalators Co. Ltd.
- Fujitec Co., Ltd.
- Hyundai Elevator Co., Ltd.
- Omega Elevators
Competitive Analysis
The Middle East elevator modernization market is highly competitive, with several key players driving innovation and growth. Leading companies such as Otis Elevator Company, KONE Corporation, Schindler Group, Thyssenkrupp AG, Mitsubishi Electric Corporation, Toshiba Elevator and Building Systems Corporation, Gulf Elevators & Escalators Co. Ltd., Fujitec Co., Ltd., Hyundai Elevator Co., Ltd., and Omega Elevators dominate the market with their strong product portfolios and extensive service networks. Companies in this market focus on delivering energy-efficient, safe, and sustainable modernization services to meet the evolving needs of urbanization and infrastructure development across the region. Many players are investing in research and development to integrate smart technologies, such as IoT and AI, to enhance the operational efficiency and safety features of elevators. Additionally, companies are leveraging predictive maintenance and real-time monitoring systems to improve service quality and reduce operational costs. Price competitiveness, quality, and the ability to meet local building regulations are significant factors influencing the competitive dynamics. Furthermore, players are expanding their service networks and offering customized solutions to cater to the diverse needs of residential, commercial, and industrial buildings. As the demand for modernization grows, competition will intensify, with companies focusing on innovation, service excellence, and energy-efficient solutions to maintain a strong market position.
Recent Developments
- In December 2024, Fujitec Indonesia successfully delivered 19 modernized elevators to the iconic Wisma 46office building in Jakarta. This modernization includes the introduction of the EZSHUTTLE destination dispatch system, which automates elevator assignments based on passenger destinations, improving operational efficiency.
- In October 2024, Otis Elevator announced its involvement in the modernization of elevators at the Eiffel Towerin Paris, enhancing the duolift™ elevators that serve millions of visitors annually. Additionally, they are set to begin modernization work at the Burj Khalifa in Dubai, which will include a 10-year maintenance and upgrading contract for 34 elevators.
- In September 2024, KONE Corporation unveiled its ambitious strategy called "Rise" for 2025-2030, which emphasizes driving modernization to unlock growth opportunities and enhance customer experiences. This strategy includes a focus on digital transformation and sustainability initiatives.
- In September 2024, Thyssenkrupp AG (TK Elevator) was awarded a contract to modernize escalators for the Cologne subway system in Germany. The project includes installing 23 victoria-type escalators equipped with MAX Smart Maintenance technology, which aims to reduce maintenance efforts and enhance operational efficiency.
Market Concentration & Characteristics
The market concentration in the Middle East elevator modernization sector is moderate, with a mix of global and regional players competing for market share. While large multinational companies dominate the market with advanced technological offerings, regional players are increasingly carving out their own space by providing tailored solutions at competitive prices. The market is characterized by the presence of well-established players that have significant resources, enabling them to innovate continuously and provide a wide range of services, including smart and energy-efficient elevator modernization solutions. These players also benefit from extensive service networks and strong relationships with building developers and property owners. However, smaller regional companies are gaining traction by focusing on niche segments and offering cost-effective, localized services that meet specific customer needs. The demand for energy-efficient, sustainable modernization solutions is a key characteristic of the market, driving both global and regional companies to develop advanced, environmentally-friendly technologies. The increasing urbanization in countries like the UAE, Saudi Arabia, and Turkey is further boosting market growth, creating opportunities for both established and emerging players. As modernization projects gain momentum across residential, commercial, and industrial sectors, the competition is expected to intensify, with companies emphasizing service quality, technological innovation, and regulatory compliance to stay ahead in the market.
Report Coverage
The research report offers an in-depth analysis based on Type, Application, Component and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Middle East elevator modernization market is expected to grow significantly, driven by rapid urbanization and the need for energy-efficient solutions.
- Increased demand for smart elevators and predictive maintenance technologies will drive innovation in the market.
- Sustainability regulations and energy-efficiency goals will push building owners to modernize elevators to meet new standards.
- The rise in high-rise buildings and mixed-use developments will fuel the demand for advanced elevator systems.
- The market will see a rise in machine-room-less (MRL) elevators due to space-saving advantages and energy efficiency.
- As urban infrastructure continues to expand, modernization projects in both residential and commercial buildings will accelerate.
- Investment in technology integration, such as IoT and AI, will enhance the operational efficiency of elevator systems.
- Regional players will continue to gain traction by offering localized solutions tailored to the unique needs of the Middle East market.
- Competitive pricing, service quality, and compliance with local regulations will remain key factors for companies to stay competitive.
- The market will be increasingly driven by government-backed infrastructure projects, creating opportunities for elevator modernization across various sectors.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Middle East Elevator Modernization Market?
What factors are driving the growth of the Middle East Elevator Modernization Market?
What are the key segments within the Middle East Elevator Modernization Market?
What are some challenges faced by the Middle East Elevator Modernization Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 273.90 million → 2032: USD 579.51 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Middle East Elevator Modernization Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Middle East Elevator Modernization Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Middle East Elevator Modernization Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Middle East Elevator Modernization Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Middle East Elevator Modernization Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Middle East Elevator Modernization Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Middle East Elevator Modernization Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Middle East Elevator Modernization Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 273.90 million → 2032: USD 579.51 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Middle East Elevator Modernization Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Middle East Elevator Modernization Geographic Market Outlook, 2023-2032
- 13.1 Regional Market Size and Country-Level Shares, 2023
- 13.2 Country Market Size Comparison, 2023
- 13.3 Country Market Forecasts, 2023-2032
- 13.4 Subregional Industrial and Demand Clusters
- 13.5 Intra-Regional Pricing and Cost Differences
- 13.6 Cross-Border Trade and Supply Networks
- 13.7 Regional Supply and Demand Balances
- 13.8 Country Opportunity Comparison and Prioritization
Note: Every listed country is covered on the structure shown under the first country.
Chapter 14 Middle East Elevator Modernization Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2023-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Middle East Elevator Modernization Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2023
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2023-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.
