
Mobility as a Service Market Overview:
The Mobility as a Service (MaaS) market was valued at USD 192,295.8 million in 2024 and is anticipated to reach USD 693,928.26 million by 2032, growing at a CAGR of 17.4% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Mobility as a Service Market Size 2024 | USD 192,295.8 million |
| Mobility as a Service Market, CAGR | 17.4% |
| Mobility as a Service Market Size 2032 | USD 693,928.26 million |
Leading players in the Mobility as a Service (MaaS) market include Uber Technologies, Lyft, Grab Holdings, Intel Corporation (Moovit), and BlaBlaCar, each offering distinct strengths across ride-hailing, multimodal planning, and regional carpooling. Uber and Lyft dominate North America with wide fleet coverage and advanced AI-driven route systems. Grab leads in Southeast Asia through super-app integration and payment platforms. Intel’s Moovit supports global city transit networks with data analytics and journey planning. BlaBlaCar maintains strong presence in Europe with its long-distance carpooling network. In 2024, Asia-Pacific emerged as the leading region, capturing 34% of the global MaaS market, followed by North America at 30% and Europe at 28%. These regions benefit from strong digital infrastructure, high urban density, and active regulatory support for smart mobility initiatives.
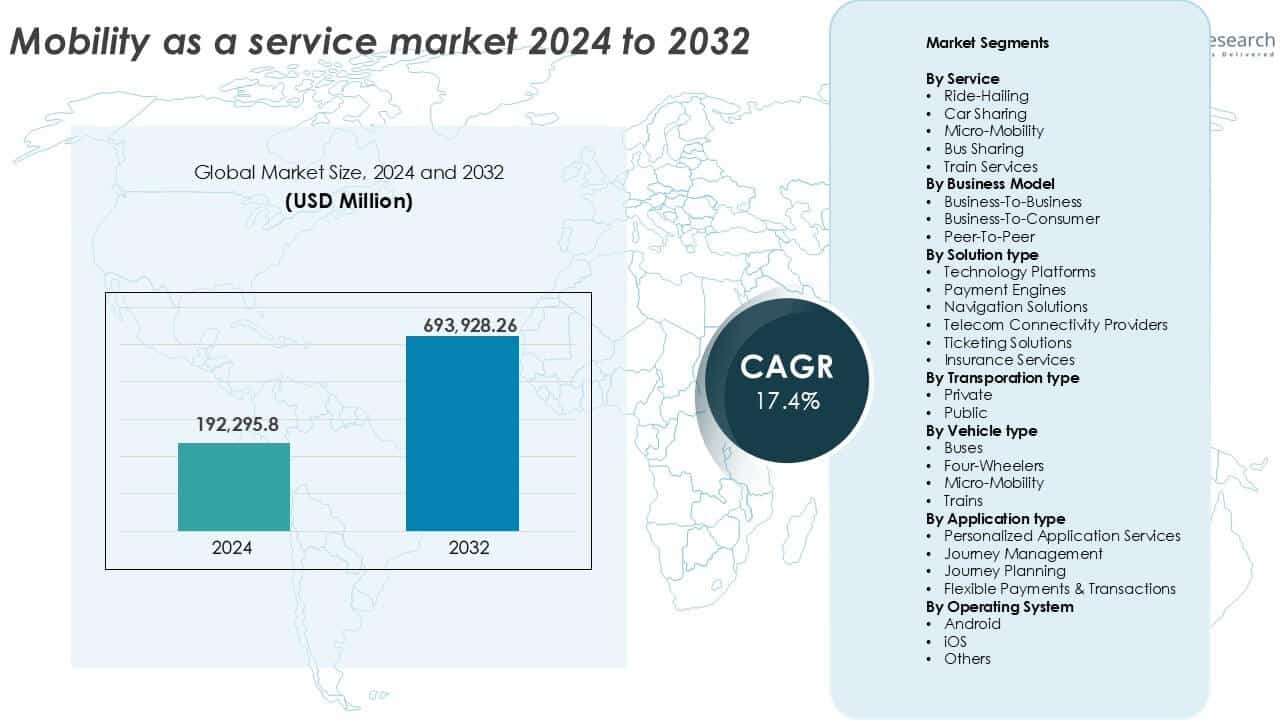
Mobility as a Service Market Insights
- The Mobility as a Service (MaaS) market was valued at USD 192,295.8 million in 2024 and is projected to reach USD 693,928.26 million by 2032, growing at a CAGR of 17.4%.
- Urban congestion, high fuel costs, and the shift away from car ownership are major drivers boosting MaaS adoption.
- Integration of electric vehicles and AI-driven personalization is shaping service innovation and user engagement.
- Uber, Lyft, Grab, and Moovit lead the market with strong digital platforms and multimodal offerings, but interoperability across providers remains a key restraint.
- Asia-Pacific holds 34% of the global share, followed by North America (30%) and Europe (28%); ride-hailing is the dominant segment by service, while business-to-consumer leads by business model.
Mobility as a Service Market Segmentation Analysis:
By Service
Ride-hailing dominates the Mobility as a Service market, accounting for the largest market share in 2024. Its leadership stems from widespread adoption across urban areas, flexible on-demand availability, and increasing smartphone penetration. Companies like Uber, Lyft, and Grab have scaled operations through pricing innovation and service reliability. The rise of hybrid and electric ride-hailing fleets further enhances sustainability goals. Micro-mobility is gaining traction in last-mile delivery and urban short-distance commuting. Car sharing and bus sharing serve niche commuter groups, while train services contribute mainly in countries with established rail networks.
- For instance, Uber operates in more than 70 countries and completes over 20 million trips per day across its platforms. Uber integrated electric vehicle options in major cities, supporting more than 180,000 active EV drivers globally.
By Business Model
The Business-to-Consumer (B2C) model leads the market, holding the highest revenue share. B2C platforms such as app-based ride-hailing and micro-mobility services cater directly to urban customers seeking convenience and real-time access. The model supports large-scale user adoption, personalized mobility options, and flexible pricing. Peer-to-Peer (P2P) sharing is growing, supported by trust-based platforms and vehicle availability. Business-to-Business (B2B) services, though smaller in share, are expanding within corporate travel and employee mobility programs, especially in cities with high enterprise density.
- For instance, Grab serves mobility users across eight Southeast Asian countries. Grab processes billions of transactions annually across ride-hailing and mobility services.
By Solution Type
Technology platforms dominate the MaaS solution landscape, contributing the largest share due to their central role in enabling seamless user experiences. These platforms integrate ride booking, payments, and scheduling into unified applications. Advanced navigation solutions enhance real-time route optimization and estimated time of arrival (ETA) tracking. Payment engines support cashless transactions, while telecom connectivity providers ensure continuous service delivery. Ticketing solutions drive multimodal integration, and insurance services build trust by covering travel-related risks. Growth across all categories reflects rising demand for integrated and secure digital mobility ecosystems.
Mobility as a Service Market Key Growth Drivers
Urban Congestion and Pollution Control Measures
Governments across the globe are promoting Mobility as a Service (MaaS) to reduce urban congestion and carbon emissions. Rising traffic levels in cities have increased fuel consumption, commute times, and air pollution, prompting authorities to invest in sustainable alternatives. MaaS integrates multiple transport options, reducing private vehicle dependency. Cities like London, Singapore, and Helsinki have adopted low-emission zones and congestion pricing, encouraging the use of ride-sharing and public transport. These measures align with national climate goals and urban sustainability plans. Public-private partnerships are also accelerating MaaS adoption by funding infrastructure and digital platforms. Consumer interest in eco-friendly transport further boosts demand. With urban populations expected to grow significantly by 2035, MaaS offers scalable solutions for cities aiming to reduce traffic, improve air quality, and modernize mobility systems.
- For instance, Transport for London operates the London congestion charge zone covering 21 square kilometers. Following its implementation in 2003, the scheme reduced weekday traffic volumes by approximately 70,000 vehicles per day.
High Smartphone Penetration and Digital Payment Adoption
Widespread smartphone usage and digital payment systems have become key enablers of the MaaS market. Mobile apps serve as the primary access point for users to plan, book, and pay for multimodal transport. Real-time GPS, integrated route planning, and payment gateways simplify the user experience. Countries such as India, China, and Brazil have seen sharp rises in mobile internet users, expanding the market base. E-wallets, UPI, and contactless cards provide secure, seamless transactions across service providers. The digital interface helps MaaS platforms gather behavioral data to personalize offerings, optimize fleets, and manage demand. Operators leverage analytics and machine learning to improve asset allocation and reduce idle time. As fintech integration strengthens, MaaS becomes more accessible and efficient, particularly in fast-growing economies undergoing digital transformation.
- For instance, National Payments Corporation of India operates the UPI platform processing more than 20 billion transactions per month. UPI connects over 684 banks through a single payment interface.
Growing Demand for Cost-Effective and Flexible Transportation
Rising fuel costs, urban living expenses, and limited parking availability are shifting consumer preference away from car ownership. MaaS platforms offer affordable and flexible transport options without long-term commitments. Subscription-based and pay-per-use models appeal to daily commuters, students, and tourists seeking low-cost alternatives. Shared services like ride-hailing, micro-mobility, and car-sharing enable users to select the best mode per trip. These services reduce the financial burden of vehicle maintenance, insurance, and depreciation. Flexible access to various transport options also enhances mobility for those underserved by traditional public transit. As users prioritize convenience, affordability, and accessibility, MaaS platforms gain popularity across both developed and emerging markets. The shift from ownership to shared access plays a central role in the long-term scalability of the MaaS ecosystem.
Mobility as a Service Market Key Trends & Opportunities
Integration of Electric Vehicles in MaaS Fleets
The shift toward electrification creates major opportunities for MaaS platforms to align with global sustainability goals. Many ride-hailing and car-sharing services are actively adding electric vehicles (EVs) to their fleets to meet emission regulations and attract eco-conscious users. Governments support this transition with incentives, EV infrastructure funding, and fleet electrification mandates. Companies like Uber and Bolt have pledged to convert large portions of their fleets to electric by 2030. Integration of EVs helps reduce total cost of ownership, particularly in urban settings where fuel efficiency and maintenance are critical. EV charging networks are also being integrated into MaaS apps for route optimization and charging alerts. The trend is expected to accelerate as battery costs decline and range performance improves, making EV-based MaaS more competitive and attractive.
- For instance, Uber reported more than 180,000 active electric vehicles on its platform globally by 2023. The company committed to operating a fully electric ride-hailing fleet in Europe and North America by 2030.
AI-Driven Personalization and Predictive Mobility Services
Artificial Intelligence (AI) is transforming the MaaS user experience by enabling predictive and personalized services. AI algorithms analyze mobility patterns, traffic data, and user behavior to deliver optimized routes, dynamic pricing, and tailored travel suggestions. Predictive scheduling allows platforms to anticipate peak demand, reducing wait times and improving fleet utilization. Platforms also deploy AI for real-time vehicle tracking, automated dispatch, and proactive maintenance alerts. This reduces downtime and enhances service reliability. AI-powered chatbots and voice assistants further simplify bookings and customer support. As personalization becomes a competitive differentiator, service providers are investing heavily in data analytics and AI development. This trend boosts user retention and improves operational efficiency, especially in high-density urban markets where real-time adaptation is critical.
Mobility as a Service Market Key Challenges
Interoperability Between Multiple Mobility Providers
One of the biggest challenges in the MaaS market is achieving seamless integration across various mobility providers. Most MaaS platforms rely on third-party services-ride-hailing, public transit, bike-sharing, parking, and more-each with separate ticketing systems, regulations, and APIs. Lack of standardization hampers end-to-end journey planning, fare transparency, and data sharing. Users often face fragmented experiences, switching between apps and payment platforms. This disjointed setup limits MaaS adoption and user satisfaction. Municipal authorities and private providers struggle to align their technology ecosystems. While open data initiatives and mobility APIs are emerging, many regions lack centralized governance. Without unified systems and frameworks, it becomes difficult to offer truly integrated, multimodal journeys across cities and regions.
Data Privacy and Security Concerns
As MaaS platforms rely heavily on user data location, payment details, travel history privacy and cybersecurity risks become major concerns. Frequent data breaches, misuse of personal data, and lack of clear user consent frameworks can erode trust in digital mobility services. Regulatory frameworks such as GDPR and CCPA impose strict data protection standards, but compliance varies across jurisdictions. MaaS providers must invest in secure infrastructure, encryption, and transparent data policies to meet user expectations and legal requirements. Cyberattacks on digital mobility systems could disrupt services, compromise sensitive information, and cause reputational damage. Ensuring data sovereignty, especially in cross-border operations, adds complexity. Addressing these risks is crucial for the long-term success and public trust in the MaaS ecosystem.
Mobility as a Service Market Regional Analysis
North America
North America holds a significant share of the global Mobility as a Service (MaaS) market, accounting for over 30% in 2024. The U.S. leads the region, driven by urban digitalization, strong ride-hailing adoption, and wide smartphone penetration. Major players like Uber and Lyft invest in electric fleets and AI-based route optimization. Smart city initiatives and integration with public transit enhance MaaS appeal. Canada supports growth through clean transportation incentives and urban tech hubs. The region’s mature digital infrastructure, strong fintech ecosystem, and favorable regulations contribute to consistent MaaS adoption across metropolitan areas and Tier 2 cities.
Europe
Europe commands nearly 28% of the global MaaS market share in 2024, backed by robust public transit systems and stringent emission norms. Countries like Germany, the UK, France, and the Netherlands lead through multi-modal integration, EV adoption, and digital mobility platforms. The European Union supports MaaS through regulatory frameworks and funding for sustainable urban mobility projects. Growth is also driven by high urban density, eco-conscious consumers, and the rise of shared mobility services. Scandinavian countries showcase high adoption due to advanced digital infrastructure and environmental policies. The region remains a global model for seamless, low-emission, and user-centric mobility.
Asia-Pacific
Asia-Pacific holds the largest share, exceeding 34% of the global MaaS market in 2024, fueled by rapid urbanization, large populations, and digital adoption. China leads with strong support for ride-hailing, public transport digitalization, and EV integration. India shows rapid growth with expanding app-based mobility and rising smartphone penetration. Southeast Asian countries such as Indonesia, Vietnam, and Thailand are emerging hubs due to traffic congestion and low vehicle ownership rates. Government-backed smart city projects, improving telecom infrastructure, and strong fintech growth support long-term MaaS expansion. The region is poised to lead future MaaS innovations across multimodal platforms and affordability-focused services.
Latin America
Latin America captures around 5% of the global MaaS market in 2024, with growth centered in Brazil, Mexico, and Colombia. Increasing urbanization, smartphone use, and traffic congestion drive demand for shared and flexible transport. Governments and city authorities are exploring smart mobility programs, though infrastructure gaps remain. Ride-hailing services dominate, with limited but rising adoption of integrated transit apps. Fintech expansion supports digital payment growth, improving access to MaaS services. While challenges persist due to regulatory fragmentation and funding limits, the region presents strong potential for MaaS scaling, especially in megacities seeking low-cost, high-efficiency urban mobility solutions.
Middle East & Africa
The Middle East & Africa region holds a smaller share, close to 3%, in the global MaaS market as of 2024 but shows growing momentum. The UAE and Saudi Arabia are leading with smart city investments and integrated transport frameworks. MaaS pilot projects in cities like Dubai and Riyadh include AI-powered buses, ride-sharing platforms, and cashless fare systems. In Africa, adoption is slower but gaining ground in nations like South Africa, Kenya, and Nigeria, where smartphone access and urban expansion create new demand. Limited public transit integration and infrastructure remain key challenges, but investments in digital mobility are steadily rising.
Mobility as a Service Market Segmentations:
By Service
- Ride-Hailing
- Car Sharing
- Micro-Mobility
- Bus Sharing
- Train Services
By Business Model
- Business-To-Business
- Business-To-Consumer
- Peer-To-Peer
By Solution type
- Technology Platforms
- Payment Engines
- Navigation Solutions
- Telecom Connectivity Providers
- Ticketing Solutions
- Insurance Services
By Transportation type
- Private
- Public
By Vehicle type
- Buses
- Four-Wheelers
- Micro-Mobility
- Trains
By Application type
- Personalized Application Services
- Journey Management
- Journey Planning
- Flexible Payments & Transactions
By Operating System
- Android
- iOS
- Others
By Propulsion Type
- ICE
- EV
- Hybrid electric
- CNG/LPG
By Payment Type
- Subscription
- Pay-as-you-go
By Commute Type
- Daily
- Last mile connectivity
- Occasional
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The Mobility as a Service (MaaS) market features a competitive landscape shaped by global technology firms, regional mobility operators, and platform integrators. Companies such as Uber Technologies, Lyft, and Grab dominate the ride-hailing space, leveraging large user bases, AI-driven route optimization, and growing electric vehicle integration. Intel Corporation, through Moovit, leads in multimodal journey planning and mobility analytics. Players like BlaBlaCar and Free Now cater to regional markets with carpooling and integrated transport solutions. Firms such as SkedGo, Moovel North America, and Fluidtime specialize in MaaS platforms that combine booking, ticketing, and payments. Cubic Transportation Systems supports public transit agencies with back-end infrastructure and fare systems. Strategic partnerships, investment in real-time data analytics, and expansion into underserved urban zones define the market’s competitive strategies. With rising demand for sustainability and flexibility, vendors continue to innovate across payment systems, fleet electrification, and customer experience to maintain a competitive edge in a fast-evolving mobility ecosystem.
Key Player Analysis
- UBER TECHNOLOGIES, INC.
- Lyft, Inc.
- INTEL CORPORATION (Moovit, Inc.)
- GRAB HOLDINGS LIMITED
- BlaBlaCar
- Free Now
- SkedGo
- Moovel North America, LLC.
- Fluidtime
- Cubic Transportation Systems, Inc.
Recent Developments
- In June 2025, Dutch startup umob raised €3.5 million to expand its unified mobility app across Europe. Following its earlier acquisition of MaaS Global and the ‘Whim’ app, the company aims to scale sustainable transport options by integrating ride-sharing, micromobility, and public transit into a seamless, all-in-one user experience.
- In September 2024, myTVS launched a pan-India Mobility-as-a-Service platform tailored for EV fleet operators. The platform integrates leasing, fleet management, charging, telematics, and insurance under one digital ecosystem. In partnership with MoEVing, this launch supports India's push toward EV adoption and quick commerce electrification.
- In May 2024, HCLTech and Cisco launched Pervasive Wireless Mobility-as-a-Service, delivering secure, low-latency wireless backhaul solutions for enterprise and industrial applications. The service enables vehicle, fleet, and mobile worker connectivity across automotive, mining, retail, and healthcare sectors, supporting digital MaaS infrastructure expansion.
- In July 2023, UBER TECHNOLOGIES, INC. partnered with RideCo Inc., an on-demand solutions provider. The partnership will help transit agencies manage cost strategies and scale operations up or down according to demand. The two companies shared technological expertise will benefit customers through personalized services and reduced waiting time.
Report Coverage
The research report offers an in-depth analysis based on Service, Business Model, Solution type, Transportation type, Vehicle type, Application type, Operating System, Propulsion Type, Payment Type, Commute Type and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- MaaS platforms will expand deeper into Tier 2 and Tier 3 cities across emerging markets.
- Integration of autonomous vehicles will redefine shared mobility service models.
- Electric vehicle adoption in MaaS fleets will accelerate due to environmental regulations.
- AI and machine learning will enhance route planning and demand forecasting.
- Subscription-based MaaS models will gain popularity among urban commuters.
- Telecom and connectivity advancements will improve real-time tracking and service reliability.
- Public transit systems will increasingly collaborate with MaaS providers for unified access.
- Data privacy regulations will shape platform development and user data handling.
- Multi-modal apps will become more dominant, combining bikes, taxis, trains, and rentals.
- Investors will focus on platforms offering seamless payment, integrated services, and sustainability.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Mobility as a Service market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Mobility as a Service market projected to grow between 2024 and 2032?
Which Mobility as a Service market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Mobility as a Service market?
Who are the leading companies in the Mobility as a Service market?
Which region commanded the largest share of the Mobility as a Service market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 192,295.8 million → 2032: USD 693,928.26 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Mobility as a Service Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Mobility as a Service Market Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Supply Chain Structure and Procurement Trends
- 5.4 Supply-Demand Gap and Bottlenecks
- 5.5 Import Dependence and Sourcing Structure
- 5.6 Regional Supply and Demand Concentration
Chapter 6 Global Mobility as a Service Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Pricing by Product and Market Segment
- 6.5 Geographic Pricing Differences
- 6.6 Key Input, Energy, Labor and Logistics Costs
- 6.7 Contract Pricing and Purchasing Models
- 6.8 Pricing Sensitivity and Competitive Positioning
- 6.9 Price, Margin and Profitability Implications
Chapter 7 Global Mobility as a Service Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Mobility as a Service Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Mobility as a Service Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Data Protection, AI and Cybersecurity Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Mobility as a Service Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Mobility as a Service Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 192,295.8 million → 2032: USD 693,928.26 million)
- 11.1.2 Historical Market Size
- 11.1.3 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 CAGR and Year-on-Year Growth
- 11.2.3 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Mobility as a Service Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Mobility as a Service Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Mobility as a Service Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Energy Efficiency and Resource Management
- 14.7 Sustainability, Recycling and Circularity
- 14.8 Technology Roadmap, 2024-2032
- 14.9 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Mobility as a Service Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Financial Performance and Investment
- 17.2.6 Market Share and Competitive Position
- 17.2.7 Technology and Innovation Capabilities
- 17.2.8 Strategic Alliances or Partnerships
- 17.2.9 Recent Developments
- 17.2.10 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

