
India Digital Signature Market Overview:
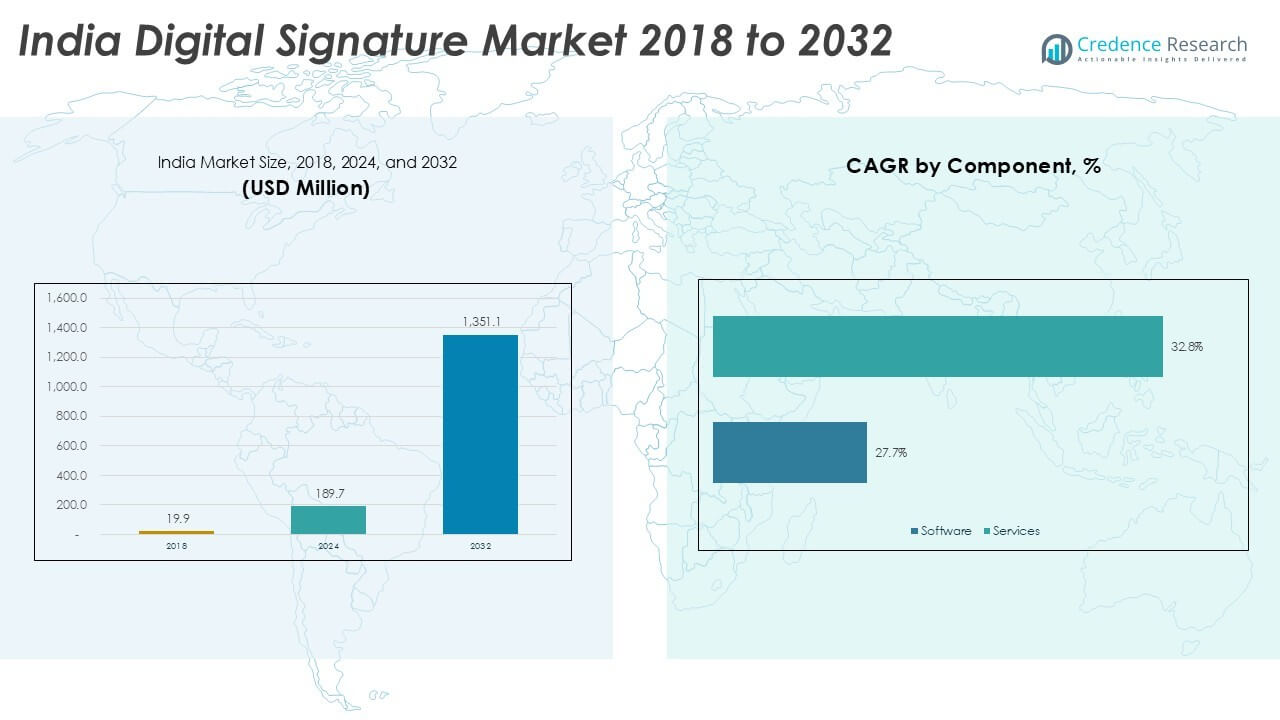
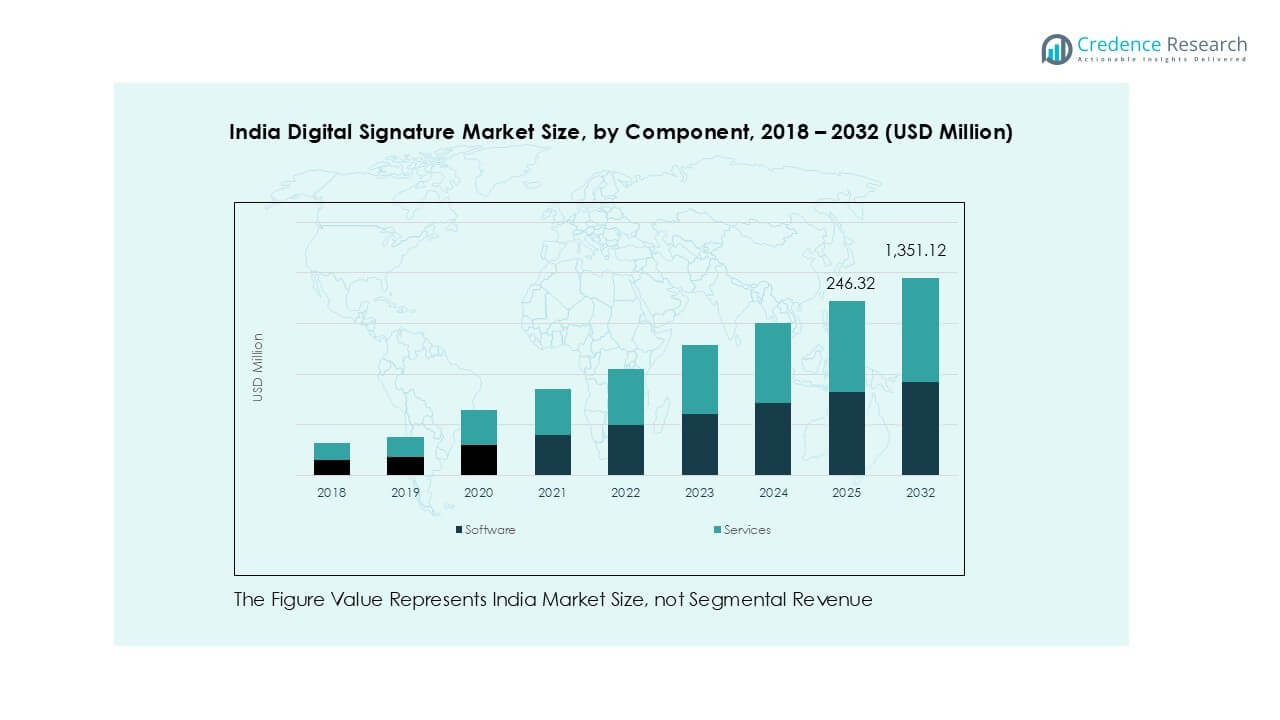
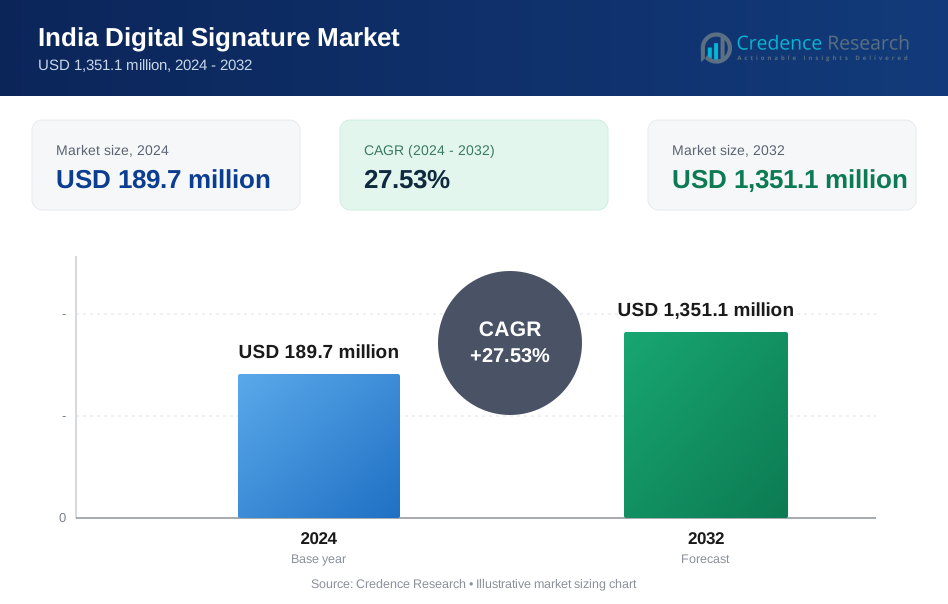
India Digital Signature market size was valued at USD 19.9 million in 2018 to USD 189.7 million in 2024 and is anticipated to reach USD 1,351.1 million by 2032, at a CAGR of 27.53% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| India Digital Signature Market Size 2024 | USD 189.7 million |
| India Digital Signature Market, CAGR | 27.53% |
| India Digital Signature Market Size 2032 | USD 1,351.1 million |
eMudhra Limited leads the India digital signature market with its advanced PKI solutions and a broad customer base across BFSI, government, and enterprise sectors. Other major players include Sify Technologies, nCode Solutions (NSDL), Capricorn Technologies, VSign Technologies, and Entrust, each offering certified digital signature services aligned with Indian regulatory frameworks. These firms compete on security features, deployment flexibility, and compliance. North India emerges as the dominant region, accounting for 31% of the total market share in 2024. The region’s leadership is driven by strong government adoption, public sector digitization, and the presence of major financial institutions and regulatory bodies.
India Digital Signature Market Insights
- The India digital signature market was valued at USD 189.7 million in 2024 and is expected to reach USD 1,351.1 million by 2032, growing at a CAGR of 27.53%.
- Rapid digitization across BFSI, government, and healthcare sectors is driving demand for secure, paperless documentation and identity authentication.
- Cloud-based solutions lead with over 68% deployment share, while software holds a 62% share by component due to easy integration and low cost.
- eMudhra Limited, Sify Technologies, and NSDL’s nCode dominate the competitive landscape through compliance-driven platforms and sector-specific digital trust services.
- North India leads regionally with 31% market share, supported by high government adoption, followed by South India at 27% due to tech-driven enterprise uptake.
India Digital Signature Market Segmentation Analysis:
By Component
In 2024, the software segment held the dominant share in the India digital signature market, accounting for over 62% of total revenue. This dominance stems from the widespread adoption of secure signing platforms integrated into enterprise workflows. Software-based digital signatures offer higher scalability, ease of integration with existing systems, and real-time verification features. Regulatory mandates and government-led digitization initiatives have accelerated software deployments across financial and public sector enterprises. Additionally, the rise in remote authentication and demand for secure document workflows continues to reinforce the preference for software over standalone service offerings.
- For instance, Zoho Sign enables workflows that complete document signing up to 80% faster than traditional methods, improving turnaround time for business contracts
By Deployment
Cloud-based deployment emerged as the leading segment in 2024, contributing nearly 68% of the market share. Its dominance is driven by the low upfront costs, faster implementation, and scalability advantages, particularly among SMEs and agile enterprises. Cloud-based digital signature platforms enable secure access across geographies and support real-time document collaboration. As more businesses transition to SaaS models, the demand for cloud-native signature platforms continues to grow. Enhanced security features, compliance with IT Act regulations, and seamless API integrations have further boosted cloud adoption in BFSI, government, and healthcare sectors.
- For instance, Adobe Acrobat Sign’s cloud service lets users send, sign, and manage digital documents from anywhere without local software installs.
By Organization Size
Large enterprises dominated the India digital signature market by organization size in 2024, capturing approximately 59% market share. These firms often manage high volumes of documentation and require streamlined authentication across departments. Enterprise-wide implementation of workflow automation tools, coupled with stringent regulatory compliance, drives large-scale adoption. However, SMEs are rapidly gaining traction due to cost-effective cloud models and government support for digital transformation. Initiatives like Digital India and MSME digitization incentives have encouraged broader usage of e-signatures among smaller businesses seeking to improve operational efficiency.
India Digital Signature Market Key Growth Drivers
Government-Led Digitization and Regulatory Mandates
The Indian government’s push for digital governance is a key catalyst for the digital signature market. Initiatives such as Digital India, e-Governance programs, and the implementation of e-signatures under the Information Technology Act, 2000 have established a solid legal framework for their use. Regulatory bodies like SEBI and RBI mandate digital signatures for specific financial and compliance processes, accelerating institutional adoption. Moreover, e-filing requirements for GST, income tax, and corporate affairs further necessitate digital signature usage. Public sector organizations, including municipal bodies and utilities, are actively shifting to paperless workflows. These initiatives significantly reduce turnaround time and improve transparency. The expanding legal recognition of electronic signatures in contracts, tenders, and audit filings continues to build confidence across sectors. As these mandates evolve, they create a sustained demand for scalable, secure, and compliant signature solutions, particularly among BFSI, government, and legal enterprises.
- For instance, the government‑run DigiLocker platform facilitated 9.4 billion document issuances and e‑sign integrations to reduce physical paperwork nationwide.
Rising Need for Secure and Efficient Authentication
With increasing instances of document forgery, identity theft, and cybercrime, enterprises are prioritizing secure and verifiable digital authentication. Digital signatures provide a tamper-evident method to verify the identity of signers, ensuring the integrity and origin of signed documents. This is especially critical for highly regulated sectors like BFSI, healthcare, and legal services. Unlike manual signatures, digital alternatives reduce the risk of fraud and eliminate physical handling delays. Enterprises are also seeking greater efficiency in signing workflows e-signatures help reduce turnaround times from days to minutes. Integration with enterprise resource planning (ERP), customer relationship management (CRM), and cloud storage systems improves overall operational agility. As remote and hybrid work models gain ground, the need for secure, end-to-end digital transactions continues to grow. This increasing demand for authentication tools that are both secure and scalable drives robust adoption across industries.
- For instance, e‑signature platforms like DocuSign support PKI‑based tamper‑evident signing with complete audit trails that track every action and timestamp
Expansion of Cloud-Based Signature Solutions Among SMEs
The availability of cloud-based digital signature solutions at flexible pricing has opened doors for mass adoption, especially among India’s large SME base. These businesses typically lack the IT infrastructure to deploy and maintain on-premises signature systems. Cloud solutions offer quick setup, low capital investment, and the ability to scale usage based on need. As MSMEs increasingly digitize invoicing, HR, legal, and procurement processes, cloud-based signatures provide a convenient and compliant tool. Vendors offer plug-and-play APIs that integrate easily with productivity tools and accounting software, enabling frictionless user experiences. Moreover, growing awareness about data security, compliance requirements, and paperless efficiencies has encouraged uptake. Government support for SME digitization through subsidies and portals like GeM and Udyam Registration further boosts this trend. As a result, SaaS-based signature platforms are becoming a strategic enabler for SME productivity and compliance in India’s evolving digital economy.
India Digital Signature Market Key Trends & Opportunities
Integration of Digital Signatures With Workflow Automation Platforms
One of the most notable trends in India’s digital signature market is the integration of e-signature tools with broader digital workflow and document management platforms. Enterprises are no longer treating digital signatures as standalone tools but as key components within automated systems for procurement, HR onboarding, contract lifecycle management, and finance approvals. This shift allows seamless signing, tracking, and archiving of documents within unified platforms. Tools like Zoho Sign, Adobe Acrobat Sign, and DocuSign offer APIs and plug-ins that integrate with Microsoft 365, Google Workspace, SAP, and Salesforce. This improves operational speed, eliminates data silos, and ensures regulatory compliance. Businesses benefit from audit trails, version control, and cloud backups-all critical for high-trust environments. The rising demand for end-to-end digital process automation, especially in sectors like IT, logistics, and real estate, presents significant opportunities for vendors to bundle digital signatures with broader digital workflow solutions.
- For instance, DocuSign’s eSignature API processes automated signatures across 1,000+ connected apps, enhancing audit trails and cloud archiving.
Growing Demand from Healthcare, Education, and Legal Sectors
While BFSI and government sectors remain the largest users of digital signatures, emerging demand from healthcare, education, and legal services is creating new market opportunities. In healthcare, hospitals and insurers use digital signatures for consent forms, e-prescriptions, and claims processing, improving security and compliance with patient data regulations. In the education sector, universities are digitizing transcripts, admission records, and exam certificates to reduce fraud and streamline administrative workflows. Legal firms and notaries adopt digital signatures for contracts, affidavits, and client agreements, reducing paperwork and enabling remote services. These sectors, previously reliant on in-person or paper-based verification, are now embracing e-signature tools as part of their digital transformation strategies. With increasing acceptance of remote interactions and compliance needs, these verticals represent untapped potential for digital signature vendors targeting mid-size to large institutions across tier 1 and tier 2 cities in India.
India Digital Signature Market Key Challenges
Limited Awareness and Adoption Among Micro Enterprises
Despite growing usage among large firms and mid-sized businesses, awareness of digital signature solutions remains limited among India’s micro and informal enterprises. Many small businesses are unfamiliar with the legal validity, ease of use, and security benefits of digital signatures. These firms often lack digital infrastructure or digital literacy to adopt such tools independently. Cost sensitivity, reliance on manual processes, and lack of localized vendor support further hinder adoption. Additionally, a perception persists that digital signatures are complex or only required for government filings. This gap in awareness slows down widespread penetration, especially in rural and semi-urban areas. Bridging this gap requires collaborative efforts between solution providers, industry associations, and government agencies to deliver education, training, and affordable solutions tailored to this segment.
Data Privacy and Cybersecurity Concerns
Data security remains a major barrier for organizations considering digital signature adoption. Enterprises are increasingly cautious about the privacy of signed documents, especially when using cloud-based platforms. Concerns around data leaks, unauthorized access, and phishing attacks can delay or limit implementation. The digital signature process involves storing sensitive documents and signer credentials, making it a target for cyber threats. Although most providers follow standards like PKI (Public Key Infrastructure) and AES encryption, not all users are confident in these protections. Compliance with India’s data protection laws, such as the Digital Personal Data Protection Act, adds complexity for vendors and users. Companies also seek transparency regarding data residency, audit trails, and certificate issuance. To overcome this challenge, vendors must prioritize transparency, regular security audits, and robust encryption while educating users on the safeguards in place to build trust.
India Digital Signature Market Regional Analysis
North India
North India accounted for the largest share of the India digital signature market in 2024, contributing nearly 31% of the total revenue. This dominance stems from the high concentration of government offices, public sector undertakings, and large enterprises in Delhi, Haryana, and Uttar Pradesh. Rapid digitization of administrative processes and widespread e-governance initiatives have driven demand. Additionally, sectors such as BFSI and legal services have seen strong adoption due to compliance mandates. The presence of multiple data centers and IT hubs further supports the deployment of cloud-based signature platforms in this region.
South India
South India held approximately 27% of the market share in 2024, driven by strong adoption across IT, telecom, and healthcare sectors. Major tech hubs like Bengaluru, Hyderabad, and Chennai have accelerated the use of integrated digital signature tools within enterprise workflows. The region benefits from advanced infrastructure, high digital literacy, and the presence of leading SaaS vendors. Government projects across Andhra Pradesh and Telangana promoting e-signatures for citizen services have further supported market growth. SMEs and startups in the region are increasingly adopting cloud-based models to streamline operations, contributing to the segment’s expansion.
West India
West India contributed around 22% of the total market share in 2024, led by demand from financial institutions and corporate enterprises in Maharashtra and Gujarat. Mumbai’s role as India’s financial capital has spurred adoption of digital signatures across banking, insurance, and legal operations. Enterprises in Pune and Ahmedabad are also driving adoption through digitized procurement and HR processes. Government e-procurement platforms and digital public services in Gujarat support growth. The region shows strong interest in secure and compliant authentication tools, especially as businesses shift toward paperless documentation to meet regulatory and ESG goals.
East India
East India captured nearly 13% of the market share in 2024, with growing usage across government agencies, educational institutions, and mid-sized businesses in states like West Bengal, Odisha, and Jharkhand. While adoption trails other regions, ongoing investments in digital infrastructure and public service digitization are expanding the market. Kolkata serves as a regional hub for BFSI and IT services, encouraging demand for secure document workflows. State-level e-governance schemes have introduced e-signatures in citizen-centric services. As awareness grows among SMEs and cooperative banks, the region is expected to witness steady growth in the forecast period.
North-East India
North-East India accounted for the smallest share, at about 7% in 2024, primarily due to limited digital infrastructure and lower enterprise density. However, the region shows gradual improvement through increased deployment of e-signature solutions in public welfare schemes, rural banking, and educational initiatives. Government-led connectivity projects and digital inclusion efforts under the Digital India program are laying the foundation for future adoption. States like Assam and Meghalaya are experimenting with cloud-based digital services, including e-documentation in administrative tasks. With targeted vendor outreach and training initiatives, North-East India presents emerging potential for market expansion in coming years.
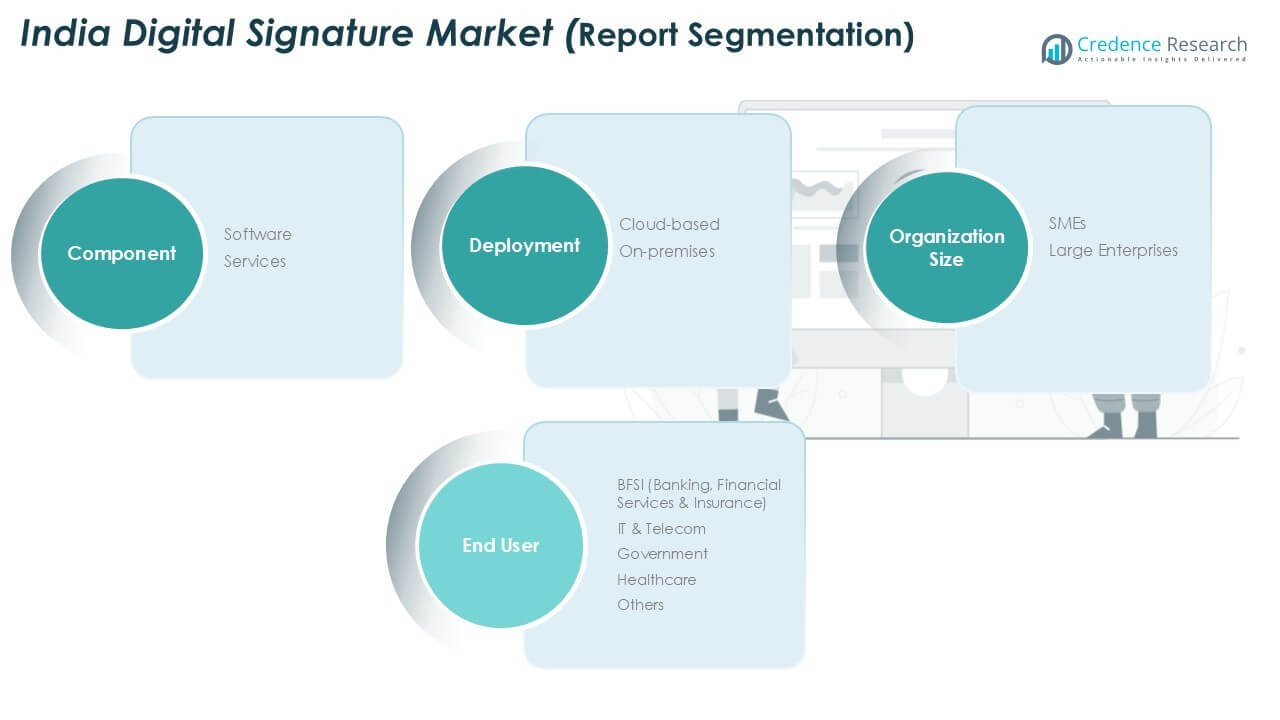
India Digital Signature Market Segmentations:
By Component
- Software
- Services
By Deployment
- Cloud-based
- On-premises
By Organization Size
- SMEs
- Large Enterprises
By End-User Industry
- BFSI (Banking, Financial Services & Insurance)
- IT & Telecom
- Government
- Healthcare
- Others
By Geography
- North India
- South India
- West India
- East India
- North-East India
Competitive Landscape
The India digital signature market features a mix of domestic certificate authorities and global cybersecurity providers competing on product reliability, compliance, and integration capabilities. eMudhra Limited leads the market with a robust client base, wide-ranging digital trust services, and strong government affiliations. Other key players such as Sify Technologies, nCode Solutions (NSDL), Capricorn Technologies, and VSign Technologies also hold significant shares due to their certified solutions and focus on legal, banking, and public sector clients. New entrants like IDSign and XtraTrust CA are expanding with cost-effective and cloud-first offerings targeting SMEs. International players such as Entrust are gaining ground by offering scalable SaaS platforms with enhanced encryption. The market is characterized by continuous innovation in identity verification, certificate lifecycle management, and workflow integration. Partnerships with IT solution providers, regulatory compliance alignment, and customer support infrastructure remain key differentiators driving competition in India’s evolving digital signature landscape.
India Digital Signature Market Key Player Analysis
- eMudhra Limited
- Sify Technologies
- nCode Solutions (NSDL)
- Capricorn Technologies
- VSign Technologies
- IDSign
- Entrust
- PantaSign
- XtraTrust CA
- Other Key Players
Recent Developments
- In February 2025, PantaSign has been actively promoting its advanced digital signature solutions, emphasizing PKI-based encryption, multi-factor authentication, and seamless cloud-based signing experiences. While there is no specific mention of a new product launch or major partnership in 2025, PantaSign continues to expand its reach by offering industry-specific solutions and robust customer support, reinforcing its role as a trusted Certifying Authority in India’s digital signature landscape.
- In February 2023, Zoho introduced significant enhancements to its Zoho Sign service, specifically targeting Independent Software Vendors (ISVs) and Original Equipment Manufacturers (OEMs). The upgraded service enables seamless integration of Zoho’s digital signature capabilities into third-party products, featuring comprehensive APIs, mobile SDKs, Single Sign-On (SSO) authentication, and customizable branding. This move is aimed at expanding the adoption of digital signatures across diverse software ecosystems and strengthening Zoho’s position in the Indian digital signature market.
- In January 2023, DocuSign entered into a strategic partnership with TechnoBind to bring its eSignature technology to the Indian market. This collaboration supports the Digital India initiative and leverages DocuSign’s suite of applications, including eSignature, contract lifecycle management, and document creation tools, to optimize agreement processes for Indian businesses. The partnership is expected to accelerate the adoption of secure digital agreements and further digital transformation across sectors in India.
Report Coverage
The research report offers an in-depth analysis based on Component, Deployment, Organization Size, End-User Industry and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The adoption of digital signatures will continue rising across government, BFSI, healthcare, and legal sectors.
- Cloud-based deployment models will dominate due to flexibility, cost-effectiveness, and ease of scaling.
- SMEs will increase adoption driven by awareness programs and digital transformation support from the government.
- Software-based signature tools will remain the preferred choice due to seamless integration with enterprise systems.
- Integration with document management and workflow automation tools will become a standard enterprise requirement.
- Cybersecurity enhancements and compliance with evolving data protection laws will drive product innovation.
- Regional adoption will deepen as digital infrastructure improves in East and North-East India.
- Vendors will expand offerings with multilingual support and mobile-first platforms to reach wider users.
- Global and domestic players will intensify competition by offering bundled cloud and e-signature solutions.
- Awareness campaigns and regulatory clarity will play a critical role in boosting adoption across micro-enterprises.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Government-Led Digitization and Regulatory Mandates
The Indian government's Digital India initiative, e-Governance programs, and regulatory mandates under the IT Act, 2000 have established a strong legal framework for digital signatures, driving widespread adoption across public and private sectors.
Rapid Digitization Across Key Sectors
Accelerated digital transformation in BFSI, government, and healthcare sectors is increasing the need for secure, paperless documentation and identity authentication, fueling demand for digital signature solutions.
Expansion of Cloud-Based Signature Solutions
Cloud-based digital signature platforms offer low upfront costs, scalability, and easy integration, making them especially attractive to SMEs and enterprises seeking flexible, compliant, and accessible solutions.
Rising Need for Secure and Efficient Authentication
Growing concerns over document forgery, identity theft, and cybercrime are prompting organizations to adopt digital signatures for tamper-evident, verifiable authentication, particularly in regulated industries.
Integration with Workflow Automation and Enterprise Platforms
The trend of embedding digital signatures into broader workflow automation and document management systems is streamlining business processes, improving compliance, and driving further market penetration.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the India Digital Signature market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the India Digital Signature market projected to grow between 2024 and 2032?
Which India Digital Signature market segment held the largest share in 2024?
What are the primary factors fueling the growth of the India Digital Signature market?
Who are the leading companies in the India Digital Signature market?
Which region commanded the largest share of the India Digital Signature market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Component
- 1.2.1 Software
- 1.2.2 Services
- 1.3 By Deployment
- 1.3.1 Cloud-based
- 1.3.2 On-premises
- 1.4 By End-User Industry
- 1.4.1 BFSI (Banking, Financial Services & Insurance)
- 1.4.2 IT & Telecom
- 1.4.3 Government
- 1.4.4 Healthcare
- 1.4.5 Others
- 1.5 By Organization Size
- 1.5.1 SMEs
- 1.5.2 Large Enterprises
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 189.7 million → 2032: USD 1,351.1 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 India Digital Signature Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 India Digital Signature Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 India Digital Signature Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 India Digital Signature Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 India Digital Signature Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 India Digital Signature Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 India Digital Signature Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 India Digital Signature Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 189.7 million → 2032: USD 1,351.1 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 India Digital Signature Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Component - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Software
- 12.3.7.2 Services
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Deployment - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Cloud-based
- 12.4.7.2 On-premises
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By End-User Industry - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 BFSI (Banking, Financial Services & Insurance)
- 12.5.7.2 IT & Telecom
- 12.5.7.3 Government
- 12.5.7.4 Healthcare
- 12.5.7.5 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Organization Size - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 SMEs
- 12.6.7.2 Large Enterprises
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 India Digital Signature End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 India Digital Signature Geographic Market Outlook, 2024-2032
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2024-2032
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 India Digital Signature Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 India Digital Signature Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 eMudhra Limited
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Sify Technologies
- 18.4 nCode Solutions (NSDL)
- 18.5 Capricorn Technologies
- 18.6 VSign Technologies
- 18.7 IDSign
- 18.8 Entrust
- 18.9 PantaSign
- 18.10 XtraTrust CA
- 18.11 Zoho
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

