
Portable Charging Units Market Overview:
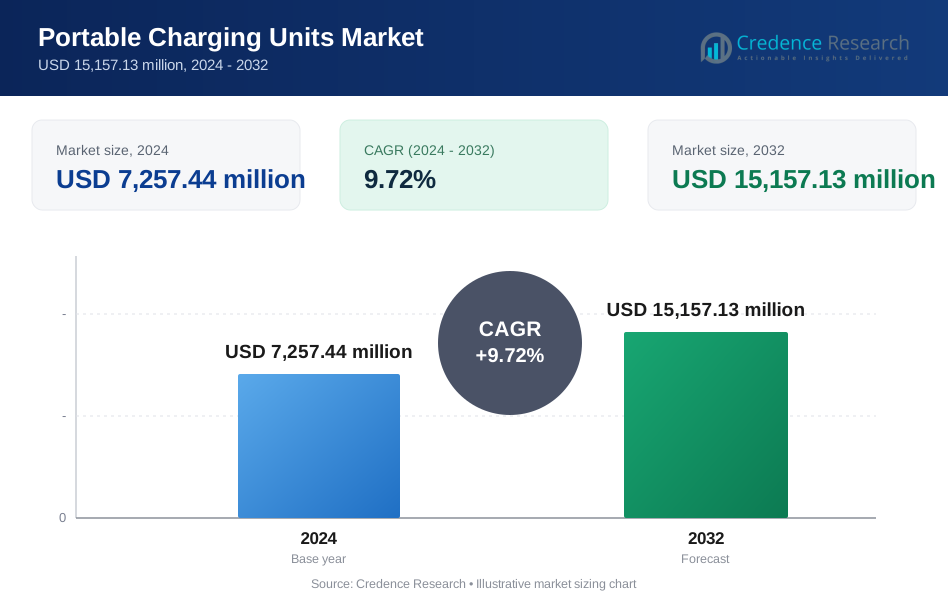
The Portable Charging Units market size was valued at USD 5,200.00 million in 2018, grew to USD 7,257.44 million in 2024, and is anticipated to reach USD 15,157.13 million by 2032, at a CAGR of 9.72% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Portable Charging Units Market Size 2024 | USD 7,257.44 million |
| Portable Charging Units Market, CAGR | 9.72% |
| Portable Charging Units Market Size 2032 | USD 15,157.13 million |
The portable charging units market is led by prominent players such as Anker Innovations, Apple Inc., AUKEY, Baseus, and Belkin, each offering advanced fast-charging technologies and wide product portfolios. Anker Innovations dominates with strong global distribution and high-capacity power banks, while Apple Inc. leverages its brand and ecosystem integration. Baseus and AUKEY cater to price-sensitive and feature-driven consumers with innovative designs and multi-port options. Regionally, Asia Pacific holds the largest market share at 33.4%, driven by high smartphone usage and manufacturing capacity. North America follows with 30.0%, supported by strong brand loyalty and premium device adoption. Europe ranks third with a 24.5% share, emphasizing product safety and sustainability.

Portable Charging Units Market Insights
- The Portable Charging Units market was valued at USD 5,200.00 million in 2018, reached USD 7,257.44 million in 2024, and is projected to hit USD 15,157.13 million by 2032, growing at a CAGR of 9.72%.
- Rising smartphone usage, increased screen time, and mobile app dependency are key drivers boosting daily charging needs.
- Wireless charging, USB-C fast charging, and compact, high-capacity models are trending among tech-savvy users.
- Market competition is intense with Anker, Apple, AUKEY, Baseus, and Belkin leading through innovation and branding.
- Asia Pacific leads with 33.4% share, followed by North America at 30.0% and Europe at 24.5%; the 6,000 mAh–10,000 mAh capacity range is the top-performing segment due to its balance of size and power.
Portable Charging Units Market Segmentation Analysis:
By Capacity Range
The 6,000 mAh–10,000 mAh segment holds the largest share in the portable charging units market. This range balances portability with high energy capacity, making it ideal for smartphones and tablets. These chargers support multiple device charges in one cycle, driving strong consumer preference. Growing use of mobile devices for streaming and gaming increases demand for mid-range capacity units. They are widely adopted by travelers and daily commuters. Power banks in this category also support fast charging, enhancing their market appeal. Compact size and reasonable price further strengthen their competitive position in the market.
- For instance, Anker sells power banks in the 10,000 mAh range that deliver up to 2.5 full charges for an iPhone 14, while supporting 20-watt fast charging through USB-C Power Delivery.
By Application
Smartphones remain the dominant application segment, accounting for the largest market share in the portable charging units industry. Increasing smartphone usage for communication, entertainment, and productivity has elevated power consumption, creating consistent demand for external power solutions. Frequent battery drain from high-screen-time activities, such as video streaming and social media, drives adoption. The growing smartphone user base in emerging economies adds to the segment's momentum. Moreover, e-learning, remote work, and mobile gaming have reinforced the need for reliable charging on the go. Compact and lightweight power banks appeal most to smartphone users.
- For instance, Samsung’s 10,000 mAh Wireless Battery Pack (EB-U3300) delivers up to 25 W wired output, supports 7.5 W wireless charging, and weighs about 234 g, enabling multiple full smartphone recharges during a single day.
By Technology
Li-Ion (Lithium-Ion) technology leads the market with the highest revenue share in the portable charging units segment. Its dominance stems from superior energy density, lightweight design, and lower cost. Li-Ion units offer faster charging cycles and longer life spans, making them ideal for everyday use. Their ability to retain charge over extended periods boosts reliability. Continuous improvements in battery safety and thermal stability support adoption across varied end-user needs. Furthermore, the rise of consumer electronics with USB-C support aligns well with Li-Ion power banks, cementing their market leadership.
Portable Charging Units Market Key Growth Drivers
Surge in Mobile Device Penetration
The rapid growth in smartphone, tablet, and wearable adoption fuels demand for portable charging units. Consumers increasingly rely on their devices for streaming, communication, navigation, and gaming, leading to higher battery usage throughout the day. Power banks have become essential tools for users seeking uninterrupted access to their devices during commutes, travel, or work. In emerging economies, rising internet penetration and affordable smartphones have significantly expanded the mobile user base. This translates to a broader customer pool for portable chargers. Furthermore, the adoption of 5G networks increases energy consumption in devices, further driving the need for external charging support. As mobile devices evolve with larger screens and more powerful processors, power backup becomes a priority, reinforcing the market's growth trajectory.
- For instance, Apple’s iPhone 15 Pro uses a 3,274 mAh battery with an A17 Pro chip, and real-world 5G video streaming drains the battery in under 10 hours, pushing users toward external power banks.
Growing Demand for On-the-Go Charging Convenience
Modern lifestyles demand mobility and convenience, which portable charging units provide effectively. Consumers value compact, lightweight power banks that offer fast and multiple device charging without reliance on fixed power outlets. The rise in outdoor activities, remote working, and business travel enhances the importance of portable chargers across diverse demographics. Young professionals, students, and frequent travelers constitute key user groups. Product innovations such as wireless charging, solar-powered units, and ultra-slim designs address the rising need for user-friendly and flexible charging solutions. Additionally, higher reliance on digital payments, online learning, and location-based apps contributes to rapid battery depletion, increasing the appeal of portable chargers. These factors position power banks as both utility and lifestyle products in global markets.
- For instance, Xiaomi’s 20,000 mAh power bank, such as the Mi Power Bank 3i , supports 18W fast charging and delivers dual or triple USB output. In real-world use, after accounting for energy conversion losses, it typically recharges a 4,500 mAh smartphone battery about three to four times, rather than over four times.
E-Commerce Expansion and Consumer Accessibility
The surge in online retail has enhanced product visibility and market access for portable charging units. E-commerce platforms enable manufacturers to reach consumers directly with competitive pricing, promotional discounts, and detailed product comparisons. This accessibility is especially valuable in remote or underserved regions where offline retail infrastructure is limited. Online reviews, influencer marketing, and product ratings further accelerate consumer decision-making. Many brands also leverage digital channels to launch feature-rich models targeted at specific audiences. The convenience of doorstep delivery, easy returns, and multiple payment options improves customer experience. This online ecosystem supports rapid product adoption and wider market penetration, especially among tech-savvy consumers and younger demographics seeking the latest power solutions.
Portable Charging Units Market Key Trends & Opportunities
Integration of Advanced Battery Technologies
The incorporation of fast-charging and high-capacity lithium polymer (Li-Polymer) and lithium-ion (Li-Ion) cells is reshaping product design and performance. These battery chemistries offer better energy density, longer cycle life, and compact form factors, making them ideal for portable use. Innovations like GaN (gallium nitride) technology allow smaller, faster-charging devices, expanding the competitive landscape. Brands are focusing on integrating USB-C PD (Power Delivery) and Quick Charge protocols to enable faster multi-device charging. These advances also enhance thermal stability and reduce charging time. The shift toward eco-friendly, recyclable materials and safety-compliant power banks reflects evolving regulatory and consumer expectations. As demand for high-performance, lightweight, and fast-charging solutions grows, battery innovation remains central to product differentiation.
- For instance, Anker’s PowerCore 737 uses a 24,000 mAh Li-Ion battery with GaNPrime technology, supports up to 140 W USB-C PD output, and recharges from 0 to full in about 52 minutes using a compatible fast charger.
Rise in Demand for Solar and Wireless Charging Solutions
Sustainability concerns and off-grid power needs have accelerated demand for solar-powered portable chargers. Consumers in outdoor, rural, or disaster-prone regions find solar charging beneficial, especially where electricity access is unreliable. Similarly, wireless charging-enabled power banks appeal to users seeking clutter-free, cableless convenience. The growing use of Qi-compatible devices including smartphones, earbuds, and smartwatches has widened the use cases for wireless units. These innovations align with the shift toward greener, smarter charging alternatives and offer brands new market differentiation points. As users prioritize convenience and sustainability, solar-integrated and wireless power banks represent significant opportunity areas for growth.

Portable Charging Units Market Key Challenges
Safety and Regulatory Compliance Issues
Battery safety remains a key challenge in the portable charging units market. Overheating, short circuits, and poor-quality cells can lead to fire hazards and device damage. Inconsistent adherence to international safety standards among low-cost or counterfeit products erodes consumer trust. Regulatory bodies increasingly mandate certifications like CE, FCC, and RoHS for battery-operated devices. Manufacturers must invest in high-quality components, thermal management systems, and rigorous testing protocols to meet these standards. Non-compliance can lead to recalls, legal action, and brand damage. This challenge is particularly pressing in regions flooded with unbranded or grey market products that bypass safety regulations.
Market Saturation and Price Competition
Intense competition among manufacturers has led to pricing pressures and reduced profit margins. Many small and mid-sized players offer similar product features at aggressive price points, making differentiation difficult. Consumer loyalty is low, and buying decisions are often price-driven. Larger brands must continuously innovate to retain market share, which requires ongoing investment in R&D, marketing, and distribution. Price wars also limit scope for premium product positioning unless clear performance or design advantages exist. In highly saturated markets like Asia-Pacific and North America, product commoditization slows growth potential and poses sustainability challenges for smaller firms.
Portable Charging Units Market Regional Analysis
North America
North America held a substantial share of the portable charging units market, accounting for approximately 30.0% in 2024. The market expanded from USD 1,583.40 million in 2018 to USD 2,177.91 million in 2024, and is projected to reach USD 4,541.10 million by 2032, registering a CAGR of 9.7%. The region's growth is driven by high smartphone penetration, strong demand for wearable devices, and consumer preference for high-capacity power banks. Presence of leading tech brands, early adoption of new charging technologies, and established e-commerce infrastructure further support regional dominance in this segment.
Europe
Europe captured nearly 24.5% of the global portable charging units market share in 2024. The market rose from USD 1,324.96 million in 2018 to USD 1,774.97 million in 2024, and is expected to reach USD 3,494.52 million by 2032, growing at a CAGR of 8.9%. Rising use of mobile devices, stringent safety regulations, and increasing preference for eco-friendly and certified power banks drive the market. Germany, the UK, and France lead adoption, supported by well-developed retail and digital ecosystems. Demand for fast-charging and compact models is strong among tech-savvy consumers.
Asia Pacific
Asia Pacific dominates the global market with the largest share of approximately 33.4% in 2024. Valued at USD 1,682.72 million in 2018, the region's market grew to USD 2,427.22 million in 2024 and is forecast to reach USD 5,470.22 million by 2032, at the highest CAGR of 10.8%. Surging smartphone adoption, expanding middle-class population, and high mobile internet usage contribute to growth. Countries like China, India, Japan, and South Korea lead in both manufacturing and consumption. E-commerce platforms play a key role in distributing low-cost and premium charging units across urban and rural areas.
Latin America
Latin America accounted for around 6.3% of the global portable charging units market in 2024. The market size increased from USD 332.80 million in 2018 to USD 460.05 million in 2024, and is projected to hit USD 892.30 million by 2032, growing at a CAGR of 8.7%. Rising smartphone usage, mobile-based services, and urban digital inclusion programs support demand. Brazil and Mexico lead regional growth due to expanding online retail and affordable device availability. However, low brand differentiation and price sensitivity remain challenges. Still, growing youth demographics and tech consumption trends fuel steady expansion.
Middle East
The Middle East held about 2.9% of the global portable charging units market in 2024. Valued at USD 161.20 million in 2018, it grew to USD 207.52 million in 2024, and is set to reach USD 380.53 million by 2032, with a CAGR of 8.0%. Increasing smartphone adoption, expanding digital infrastructure, and rising tourism influence product demand. The UAE and Saudi Arabia represent key markets due to high mobile penetration and purchasing power. Growing interest in wireless charging and smart accessories is also observed. However, market growth is moderately constrained by high import dependency.
Africa
Africa contributed nearly 2.9% to the global portable charging units market in 2024. The market expanded from USD 114.92 million in 2018 to USD 209.77 million in 2024, and is forecast to reach USD 378.46 million by 2032, with a CAGR of 7.3%. The rise in mobile phone usage, especially in rural and off-grid areas, boosts demand for affordable and solar-powered charging units. Nigeria, South Africa, and Kenya are emerging markets supported by mobile banking and e-learning growth. Although infrastructure gaps persist, ongoing telecom expansion and increasing digital access are expected to strengthen market potential.
Portable Charging Units Market Segmentations:
By Capacity Range
- 1,000 mAh–3,000 mAh
- 3,000 mAh–6,000 mAh
- 6,000 mAh–10,000 mAh
- Above 10,000 mAh
By Application
- Smartphones
- Music Players
- Tablets
- Others
By Technology
- Li-Ion
- Li-Polymer
- Others
By Number of Ports
- One
- Two
- Three
- Four
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa

Competitive Landscape
The competitive landscape of the portable charging units market is fragmented and highly dynamic, driven by innovation, branding, and distribution strength. Leading players such as Alpha Group, Anker Innovations (Fantasia Trading LLC), Apple Inc., AUKEY, and Baseus dominate the market with extensive product portfolios and global reach. These firms focus on high-capacity, fast-charging, and multi-port designs to cater to evolving consumer needs. Companies like Belkin, ZAGG Inc., and ELECOM CO., LTD. enhance their competitiveness through strategic retail partnerships and emphasis on safety-certified power banks. Emerging brands are leveraging e-commerce and regional demand for affordable charging solutions. Innovation in wireless and solar-powered units is a key differentiator among premium segments. Pricing pressure persists due to low-cost manufacturers, especially in Asia. Players are investing in R&D, brand positioning, and sustainable product development to capture market share, while mergers and distribution collaborations also shape the ongoing competitive strategy in this rapidly growing market.
Key Player Analysis
- Alpha Group
- Fantasia Trading LLC (Anker Innovations)
- Apple Inc.
- AUKEY Official
- com
- Belkin
- ELECOM CO., LTD.
- Hama GmbH & Co KG
- Inter IKEA Systems B.V.
- Intenso International GmbH
- Mazer
- ZAGG Inc.
Recent Developments
- In 2024, Xiaomi launched its new 67W Power Bank 10000 globally, offering fast-charging support for smartphones, tablets, and other portable electronics. The product combines high power output with a compact form factor and advanced safety features, strengthening Xiaomi’s portfolio in high-performance consumer charging solutions.
- In June 2022, Touchmate, a creative self-solution provider for many applications, announced a partnership with Smartify Media and Loop to provide a new electric vehicle charging kiosk named EV-FOCUS.
Report Coverage
The research report offers an in-depth analysis based on Capacity Range, Application, Technology, Number of Ports and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for fast-charging and high-capacity power banks will continue to rise globally.
- Integration of wireless and solar charging features will gain strong traction among consumers.
- Compact and lightweight designs will dominate future product development strategies.
- Brands will invest more in safety certifications and thermal management technologies.
- E-commerce channels will play a critical role in product visibility and customer reach.
- Asia Pacific will remain the leading manufacturing and consumption hub.
- Smartphone growth and mobile-first lifestyles will sustain consistent volume demand.
- Emerging markets will see increased adoption due to affordable product availability.
- Sustainable materials and recyclable components will shape new product lines.
- Strategic partnerships and regional expansions will strengthen brand positioning.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Portable Charging Units market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Portable Charging Units market projected to grow between 2024 and 2032?
Which Portable Charging Units market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Portable Charging Units market?
Who are the leading companies in the Portable Charging Units market?
Which region commanded the largest share of the Portable Charging Units market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Portable Charging Units Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Portable Charging Units Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 7,257.44 million → 2032: USD 15,157.13 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Portable Charging Units Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Portable Charging Units Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Portable Charging Units Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Portable Charging Units Market Drivers
- 3.3 Portable Charging Units Market Restraints & Challenges
- 3.4 Portable Charging Units Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Portable Charging Units Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Portable Charging Units Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Portable Charging Units category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Portable Charging Units Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Portable Charging Units Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Portable Charging Units market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Portable Charging Units Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Portable Charging Units Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Portable Charging Units Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Portable Charging Units (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Portable Charging Units Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Portable Charging Units Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Portable Charging Units Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Portable Charging Units Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Portable Charging Units Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Portable Charging Units Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Portable Charging Units Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Portable Charging Units Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Portable Charging Units Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
