
Market Overview
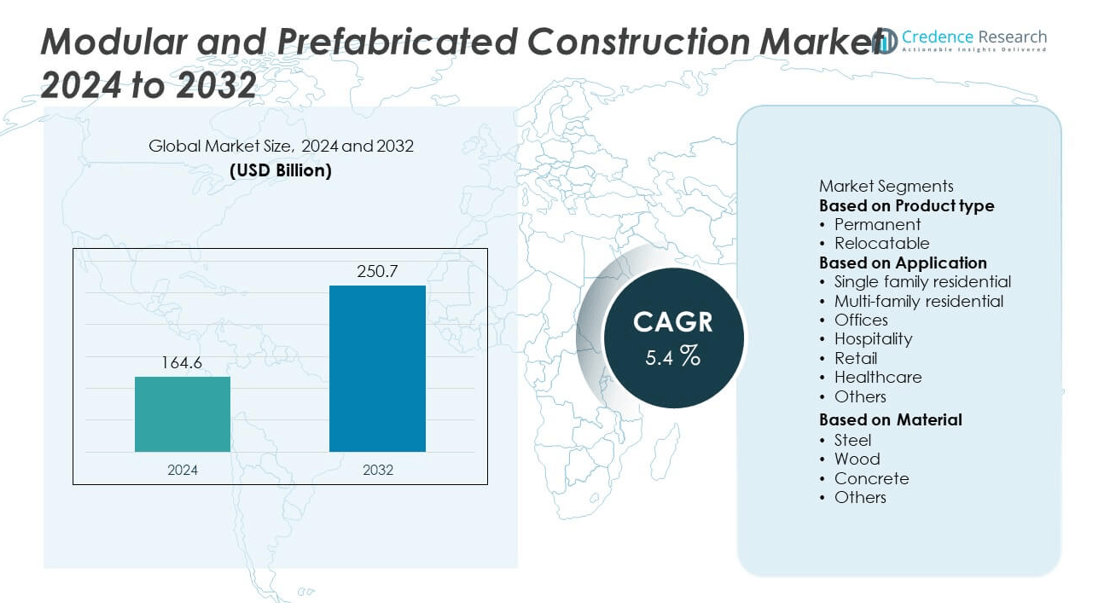
The Modular and Prefabricated Construction Market was valued at USD 164.6 billion in 2024 and is projected to reach USD 250.7 billion by 2032, expanding at a CAGR of 5.4% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Modular and Prefabricated Construction Market Size 2024 | USD 164.6 billion |
| Modular and Prefabricated Construction Market, CAGR | 5.4% |
| Modular and Prefabricated Construction Market Size 2032 | USD 250.7 billion |
The Modular and Prefabricated Construction Market grows with rising demand for cost-efficient, time-saving, and sustainable building solutions. Increasing urbanization and housing shortages drive governments and developers to adopt prefabricated methods for faster project delivery. It benefits from technological integration such as BIM, robotics, and 3D printing,
The Modular and Prefabricated Construction Market demonstrates strong growth across North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa, each region shaped by unique drivers. North America leads in adoption due to advanced infrastructure, labor shortages, and rising demand for affordable housing. Europe emphasizes sustainability and green building standards, with countries like Germany and the UK advancing large-scale prefabricated housing and commercial projects. Asia Pacific records rapid growth, supported by urbanization, government-led housing programs, and technological innovation in China, India, and Japan. Latin America and the Middle East & Africa gradually expand adoption through infrastructure projects and government-backed initiatives to address housing shortages. Key players shaping the global market include Bouygues Construction, Laing O’Rourke, ACS Group, and Algeco (Modulaire Group), all investing in automation, sustainable materials, and global expansion strategies to strengthen their positions and meet rising construction demands worldwide.
Market Insights
- The Modular and Prefabricated Construction Market was valued at USD 164.6 billion in 2024 and is expected to reach USD 250.7 billion by 2032, expanding at a CAGR of 5.4% during the forecast period.
- Rising demand for cost-efficient, time-saving, and scalable building solutions drives adoption across residential, commercial, and industrial sectors. It addresses housing shortages, urbanization challenges, and the need for faster project delivery worldwide.
- Key trends include the integration of advanced technologies such as Building Information Modeling (BIM), robotics, and 3D printing, which improve accuracy, reduce waste, and enhance efficiency in modular production.
- Competitive dynamics remain strong, with leading companies such as Bouygues Construction, Laing O’Rourke, ACS Group, and Algeco (Modulaire Group) focusing on sustainable materials, automation, and global expansion strategies.
- High initial investment costs, limited awareness in developing economies, and varying building codes across regions act as key restraints for broader adoption, particularly in cost-sensitive markets.
- Regional growth patterns highlight strong adoption in North America through affordable housing and labor-saving solutions, Europe through sustainability and green building standards, and Asia Pacific as the fastest-growing region supported by urbanization and infrastructure investments.
- Emerging opportunities exist in Latin America and the Middle East & Africa, where government-backed housing programs and infrastructure development projects encourage the gradual adoption of modular methods and strengthen the long-term market outlook.
Market Drivers
Rising Demand for Cost-Efficient and Time-Saving Construction Solutions
The Modular and Prefabricated Construction Market grows strongly due to its ability to reduce project timelines and labor costs. Prefabricated modules allow parallel production and on-site assembly, cutting overall construction time. It supports developers by lowering expenses linked to material waste and workforce management. Builders adopt prefabrication to address housing shortages in urban centers quickly. Governments and private sectors prefer modular designs to meet infrastructure needs within strict deadlines. This driver highlights how efficiency and cost reduction boost the appeal of prefabricated methods globally.
- For instance, For the Atira student tower in Melbourne, Hickory Group's HBS2 system enabled completion in 24 months, representing a 30-40% reduction in construction time compared to conventional methods. This prefabricated construction approach significantly reduced material waste and environmental disruption.
Growing Adoption of Sustainable and Green Building Practices
The Modular and Prefabricated Construction Market benefits from rising emphasis on sustainability and energy efficiency. Prefabrication minimizes material waste and supports the use of eco-friendly components. It aligns with global carbon reduction goals and environmental regulations. Companies adopt modular solutions to meet green certification standards such as LEED and BREEAM. Prefabricated buildings often include advanced insulation and energy-saving systems, improving long-term efficiency. The trend toward environmentally responsible construction strengthens demand for modular technologies.
- For instance, Laing O'Rourke's Design for Manufacture and Assembly (DfMA) approach on the Grange University Hospital project delivered 50–55% of its components as prefabricated modules. The project saw significant carbon savings, and Laing O'Rourke also developed a D-Frame system that can save up to 70% of embodied carbon compared to traditional methods. By completing a majority of the work offsite in controlled factory environments, the approach significantly cut onsite emissions, improved quality, and reduced the construction schedule.
Urbanization and Expanding Housing Needs Worldwide
The Modular and Prefabricated Construction Market expands with rapid urbanization and rising demand for affordable housing. Population growth in developing economies creates pressure for faster housing development. It provides scalable solutions that meet residential demand without compromising quality. Governments invest in prefabricated housing projects to address shortages in metropolitan areas. Private real estate developers also adopt modular solutions to meet growing middle-class housing demand. This driver reflects how urban development accelerates adoption of prefabricated methods.
Rising Investments in Infrastructure and Commercial Projects
The Modular and Prefabricated Construction Market benefits from large-scale infrastructure and commercial developments. Modular systems support schools, hospitals, and office buildings that require faster delivery. It allows customization for diverse applications, from healthcare facilities to retail spaces. Growing investments in industrial projects also increase demand for prefabricated structures. Companies seek modular solutions for their flexibility, scalability, and durability. Expanding government and private investments make prefabricated construction an essential part of global infrastructure growth.
Market Trends
Integration of Advanced Technologies in Modular Designs
The Modular and Prefabricated Construction Market shows strong adoption of digital tools and automation. Companies use BIM, robotics, and 3D printing to improve design accuracy and speed. It enables real-time collaboration across architects, engineers, and contractors. Advanced tools also reduce errors and material waste, ensuring greater efficiency. Modular producers integrate automated assembly lines to scale output. This trend highlights how technology drives precision and productivity in modern construction.
- For instance, BIM has been shown to reduce project timelines and minimize costly rework by enhancing digital integration, precision, and productivity in construction. Case studies and industry reports have documented average schedule reductions of 15% to 25%, with rework costs lowered by 40% to 50%. Such efficiencies result in significant overall cost savings for the construction industry.
Expansion of Modular Solutions in Healthcare and Education
The Modular and Prefabricated Construction Market benefits from rising adoption in public infrastructure projects. Hospitals, clinics, and schools increasingly use modular units for faster deployment. It supports governments in meeting urgent demands for healthcare and education facilities. Prefabricated structures allow rapid scaling without sacrificing safety or quality. Institutions adopt modular models to expand facilities cost-effectively. This trend reinforces the importance of modular methods in socially critical sectors.
- For instance, Laing O'Rourke utilized its modular construction techniques, including Design for Manufacture and Assembly (DfMA), during the Royal Sussex County Hospital expansion. This approach involved manufacturing over 3,000 prefabricated components off-site, including entire plant rooms, which allowed for faster on-site assembly.
Growth in Customization and Flexible Design Options
he Modular and Prefabricated Construction Market reflects a shift toward tailored solutions. Developers demand customizable modules that adapt to diverse residential, commercial, and industrial needs. It allows integration of modern aesthetics, smart technologies, and energy-efficient systems. Customers value flexibility in layout and design while maintaining structural reliability. Modular providers respond with versatile offerings to suit varying regional preferences. This trend underscores the growing role of prefabrication in meeting specific client expectations.
Rising Popularity of Hybrid Construction Approaches
The Modular and Prefabricated Construction Market records growth in hybrid models that combine on-site and off-site techniques. Builders integrate prefabricated components with traditional construction methods for enhanced efficiency. It offers flexibility while reducing project timelines and costs. Hybrid models enable use of prefabrication in projects where full modular deployment is impractical. Developers adopt these solutions for high-rise buildings and complex infrastructure. This trend reflects how hybrid approaches expand opportunities for prefabricated construction across multiple sectors.
Market Challenges Analysis
High Initial Costs and Limited Awareness in Developing Regions
The Modular and Prefabricated Construction Market faces barriers from high upfront costs and lack of awareness. Prefabricated systems often require advanced manufacturing facilities, logistics, and skilled labor, which increases initial investment. It makes adoption challenging for small developers and governments in emerging economies. Limited understanding of modular benefits also restricts demand in cost-sensitive markets. Customers still view traditional construction as more reliable, delaying the shift toward prefabrication. These factors create hesitation among stakeholders despite the long-term cost advantages of modular construction.
Regulatory Complexities and Supply Chain Constraints
The Modular and Prefabricated Construction Market encounters challenges from inconsistent regulations and fragmented supply chains. Building codes and compliance requirements vary widely across regions, making standardization difficult. It forces manufacturers to customize modules for different jurisdictions, raising costs and timelines. Supply chain disruptions also affect the timely delivery of prefabricated components. Shortages of specialized materials or transportation delays impact project execution. These challenges highlight the need for coordinated policies and resilient supply networks to support wider modular adoption.
Market Opportunities
Rising Demand for Affordable Housing and Urban Infrastructure
The Modular and Prefabricated Construction Market has strong opportunities from global housing shortages and urban expansion. Rapid urbanization creates the need for cost-efficient and quick construction methods. It enables governments and private developers to address affordable housing gaps with scalable solutions. Prefabricated designs shorten construction cycles, making them ideal for high-density cities. Demand also rises in infrastructure projects, including schools, hospitals, and transport hubs that require faster delivery. Growing emphasis on timely project execution strengthens opportunities for modular adoption worldwide.
Advancement in Sustainable and Smart Construction Practices
The Modular and Prefabricated Construction Market benefits from opportunities in sustainable and technology-driven construction. Green building standards encourage adoption of prefabricated units that reduce waste and improve energy efficiency. It supports developers in meeting carbon reduction and resource conservation goals. Integration of smart technologies, such as IoT-enabled monitoring and energy management systems, enhances building performance. Modular designs also allow integration of renewable energy solutions, making projects more attractive to eco-conscious investors. These advancements expand the role of prefabricated construction in shaping modern, sustainable urban environments.
Market Segmentation Analysis:
By Product Type
The Modular and Prefabricated Construction Market divides into permanent and relocatable structures. Permanent modular construction accounts for significant demand across residential and commercial projects, where durability and long-term value are critical. It offers design flexibility and supports large-scale applications such as offices, schools, and hospitals. Relocatable modular units hold importance in temporary infrastructure, including construction site offices, disaster relief shelters, and military housing. It provides rapid deployment and cost efficiency while meeting short-term needs. Both categories reflect how modular methods adapt to diverse project requirements with speed and scalability.
- For instance, Guerdon, LLC, constructed and delivered 27 modular homes to the Kilohana Group Housing site in Lahaina to rehouse Maui wildfire survivors. Construction for the project began in October 2024, with the first homes arriving on Maui via barge in November 2024. While the timeline for building and delivering these modular homes was rapid, the overall housing recovery effort for wildfire survivors took longer due to extensive site preparation, which involved installing infrastructure and utilities. This project shows the speed and scalability potential of modular construction once a site is ready.
By Application
The Modular and Prefabricated Construction Market shows strong adoption across residential, commercial, and industrial sectors. Residential projects dominate demand, driven by urban housing shortages and the need for affordable living spaces. It supports rapid construction of apartments and housing units without compromising quality. Commercial applications such as retail outlets, healthcare centers, and educational facilities also show strong growth due to their need for timely delivery. Industrial users adopt modular methods to build warehouses, factories, and remote-site facilities that require quick deployment. This wide application base highlights modular construction’s versatility across key end-user industries.
- For instance, Laing O’Rourke delivered 384 hospital beds at Grange University Hospital one year ahead of schedule using modular housing systems, highlighting efficiency in healthcare-linked residential facilities. Commercial applications such as retail outlets, healthcare centers, and educational facilities also show strong growth due to their need for timely delivery.
By Material
The Modular and Prefabricated Construction Market includes steel, wood, and concrete as primary materials. Steel modules lead adoption due to their strength, durability, and suitability for multi-story buildings. It enables efficient load-bearing capacity and faster assembly in large-scale projects. Wood remains important in low-rise residential construction, supported by its cost-effectiveness and sustainability. Concrete modules gain traction in projects requiring high fire resistance, stability, and long lifespan. Each material brings unique advantages, allowing developers to select options based on budget, design, and project scale. This segmentation demonstrates how material choice directly influences performance and market adoption.
Segments:
Based on Product type
- Permanent
- Relocatable
Based on Application
- Single family residential
- Multi-family residential
- Offices
- Hospitality
- Retail
- Healthcare
- Others
Based on Material
- Steel
- Wood
- Concrete
- Others
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis
North America
North America holds around 32% share of the Modular and Prefabricated Construction Market, driven by advanced construction practices and strong adoption of offsite building methods. The United States leads with high demand for modular housing projects and commercial structures, supported by ongoing urban redevelopment initiatives. It benefits from government-backed affordable housing programs and increasing preference for time-efficient construction in major cities. Canada contributes with growth in sustainable building solutions, where modular techniques align with green building standards and energy efficiency goals. Mexico also participates through industrial and commercial projects, where prefabricated units reduce costs and speed up delivery. Strong infrastructure investment and workforce shortages continue to push modular adoption in the region.
Europe
Europe accounts for nearly 27% of the Modular and Prefabricated Construction Market, reflecting its focus on sustainability, energy efficiency, and modern construction practices. Germany, the UK, and the Netherlands dominate regional demand due to rapid adoption of prefabricated housing solutions and government incentives for green buildings. It benefits from strict European Union policies that encourage low-carbon construction and resource efficiency. France and Italy also expand modular use in healthcare and education projects, highlighting the need for fast and flexible construction methods. Scandinavia remains a leader in wood-based modular solutions, reflecting the region’s strong emphasis on sustainability and renewable materials. Europe’s market strength lies in balancing innovation, environmental responsibility, and scalability.
Asia Pacific
Asia Pacific captures about 29% share of the Modular and Prefabricated Construction Market and represents the fastest-growing regional segment. China dominates with massive urbanization and large-scale housing projects supported by government initiatives. It invests heavily in modular high-rise buildings to meet housing needs in major cities. India shows growing adoption through affordable housing programs and smart city projects where modular methods reduce construction time. Japan and South Korea focus on technology-driven prefabrication, integrating robotics and automation to address labor shortages. Southeast Asian countries also expand modular use in infrastructure and hospitality projects. The region’s rapid growth stems from rising population, industrial expansion, and government-led infrastructure investments.
Latin America
Latin America holds nearly 7% share of the Modular and Prefabricated Construction Market, with Brazil and Mexico driving adoption. The region experiences rising demand for affordable housing projects in urban centers, where modular units offer cost-effective and scalable solutions. It benefits from government-backed housing programs that emphasize efficiency and resource optimization. Chile and Argentina also show steady growth in modular construction for education and healthcare facilities. Limited awareness and budget constraints remain challenges, but partnerships with international players improve adoption rates. Growing urbanization and infrastructure investment continue to expand opportunities in the region.
Middle East and Africa
The Middle East and Africa together account for about 5% share of the Modular and Prefabricated Construction Market. The United Arab Emirates and Saudi Arabia lead the region with strong demand from large-scale infrastructure and commercial projects. It supports modular adoption in mega-projects, including smart cities and industrial zones. South Africa drives growth in Africa, focusing on modular schools, healthcare centers, and mining-related infrastructure. Limited infrastructure in some countries poses challenges, but government-backed programs and foreign investment help bridge the gap. Demand for quick, durable, and cost-effective construction solutions ensures gradual growth. The region’s long-term outlook remains positive as it prioritizes modern infrastructure and sustainability goals.
Key Player Analysis
- Hickory Group
- Algeco (Modulaire Group)
- Laing O’Rourke
- Kiewit Corporation
- Berkeley Modular Limited
- Kleusberg GmbH
- Bouygues Construction
- Guerdon, LLC
- DUB0X
- ACS Group
Competitive Analysis
The competitive landscape of the Modular and Prefabricated Construction Market features leading players such as Bouygues Construction, Laing O’Rourke, ACS Group, Algeco (Modulaire Group), Hickory Group, Kiewit Corporation, Guerdon LLC, Kleusberg GmbH, DUB0X, and Berkeley Modular Limited. These companies compete by focusing on innovation, scalability, and sustainability in modular construction solutions. They emphasize automation, robotics, and Building Information Modeling (BIM) to improve efficiency and reduce project timelines. Sustainability remains central, with firms integrating eco-friendly materials, energy-efficient modules, and waste reduction practices into their projects. Many players expand their reach through acquisitions, joint ventures, and international partnerships to secure large infrastructure and housing contracts. North America and Europe see strong activity from global players, while Asia Pacific attracts investment through rapid urbanization and government-backed housing programs. Competition also includes specialization, where companies deliver tailored solutions for sectors such as healthcare, education, and commercial spaces. This dynamic market pushes leaders to balance cost, speed, and quality while addressing regional regulatory frameworks and growing customer expectations for sustainable, modern construction methods.
Recent Developments
- In August 2025, Modular Construction Industry Global demand for modular high-rise buildings expanded, with permanent modular construction projected to US$90 billion by 2030. The industry prepared to support rising vertical construction needs.
- In May 2025, Kiewit Corporation Selected to design a deep geological repository for spent nuclear fuel in Ontario by Canada’s Nuclear Waste Management Organization-its second major win in nuclear infrastructure.
- In March 2025, Hickory Group Applied its proprietary HBS2 modular system in Melbourne to construct a 43‑storey student residence. The factory-built modules reduced material waste by 30% compared to conventional methods.
- In March 2025, Berkeley Modular Limited (via auction news) purpose-built Kent facility, which had capacity to produce up to 1,000 modular units per year, was publicly valued at £30 million when put up for auction.
- In Nov 2024, Guerdon, LLC Delivered 27 modular homes to displaced Maui wildfire victims, demonstrating rapid and resilient housing response through factory-built units
Report Coverage
The research report offers an in-depth analysis based on Product type, Application, Material and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Modular and prefabricated construction will gain ground in affordable housing sectors to meet growing urban demand promptly.
- Increasing adoption of digital technologies such as BIM, AI, and robotics will enhance design precision and production efficiency.
- Hybrid construction models combining on-site and off-site techniques will become more common in complex developments.
- Sustainability requirements will drive greater use of eco-friendly materials and energy-efficient modular systems.
- Healthcare and educational facilities will favor modular approaches for rapid deployment during emergencies or expansion.
- Growth in modular high-rise projects will expand as structural engineering and urban regulations evolve.
- Prefabricated technology will support flexible infrastructure solutions in developing countries investing in smart cities.
- Demand for customizable industrial and commercial modules will rise with increasing business diversification needs.
- Modular construction will integrate renewable energy solutions like solar panels and smart controls for enhanced building performance.
- Workforce development will focus on training professionals in automation and modular assembly for future-ready operations.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Demand for Cost-Efficient and Time-Saving Construction
Modular and prefabricated construction methods significantly reduce project timelines and labor costs by enabling parallel offsite production and onsite assembly, making them attractive for developers facing tight deadlines and budget constraints.
Emphasis on Sustainability and Green Building Standards
Growing regulatory and market focus on sustainability drives adoption of modular construction, as it minimizes material waste, supports eco-friendly materials, and helps meet green certification standards such as LEED and BREEAM.
Rapid Urbanization and Housing Shortages
Accelerating urbanization in both developed and emerging economies creates urgent demand for scalable, affordable housing solutions, which modular construction can deliver quickly and efficiently to address population growth and urban housing deficits.
Technological Integration and Automation
The integration of advanced technologies like Building Information Modeling (BIM), robotics, and 3D printing enhances design accuracy, reduces errors and waste, and increases production efficiency, making modular construction more viable and attractive for large-scale projects.
Expansion of Infrastructure and Public Sector Projects
Governments and private investors are increasingly turning to modular solutions for infrastructure projects such as schools, hospitals, and transport hubs, leveraging the speed, flexibility, and scalability of prefabricated methods to meet urgent public needs.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Modular and Prefabricated Construction, and what is its projected size in 2032?
what Compound Annual Growth Rate is the Modular and Prefabricated Construction Market projected to grow between 2025 and 2032?
What are the primary factors fueling the growth of the Modular and Prefabricated Construction Market?
Who are the leading companies in the Modular and Prefabricated Construction Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Material
- 1.2.1 Steel
- 1.2.2 Wood
- 1.2.3 Concrete
- 1.2.4 Others
- 1.3 By Application
- 1.3.1 Single family residential
- 1.3.2 Multi-family residential
- 1.3.3 Offices
- 1.3.4 Hospitality
- 1.3.5 Retail
- 1.3.6 Healthcare
- 1.3.7 Others
- 1.4 By Product Type
- 1.4.1 Permanent
- 1.4.2 Relocatable
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 164.6 billion → 2032: USD 250.7 billion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Modular and Prefabricated Construction Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Modular and Prefabricated Construction Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Modular and Prefabricated Construction Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Modular and Prefabricated Construction Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Modular and Prefabricated Construction Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Modular and Prefabricated Construction Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Modular and Prefabricated Construction Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Modular and Prefabricated Construction Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 164.6 billion → 2032: USD 250.7 billion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Modular and Prefabricated Construction Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Material - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Steel
- 12.3.7.2 Wood
- 12.3.7.3 Concrete
- 12.3.7.4 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Single family residential
- 12.4.7.2 Multi-family residential
- 12.4.7.3 Offices
- 12.4.7.4 Hospitality
- 12.4.7.5 Retail
- 12.4.7.6 Healthcare
- 12.4.7.7 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Product Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Permanent
- 12.5.7.2 Relocatable
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Modular and Prefabricated Construction End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Modular and Prefabricated Construction Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Modular and Prefabricated Construction Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Modular and Prefabricated Construction Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Bouygues Construction
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Laing O’Rourke
- 18.4 ACS Group
- 18.5 Algeco (Modulaire Group)
- 18.6 Hickory Group
- 18.7 Kiewit Corporation
- 18.8 Berkeley Modular Limited
- 18.9 Kleusberg GmbH
- 18.10 Guerdon, LLC
- 18.11 DUB0X
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

