
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Next Generation Memory Market Size 2024 | USD 6,795 million |
| Next Generation Memory Market, CAGR | 28.80% |
| Next Generation Memory Market Size 2032 | USD 51,461.73 million |
Market Overview
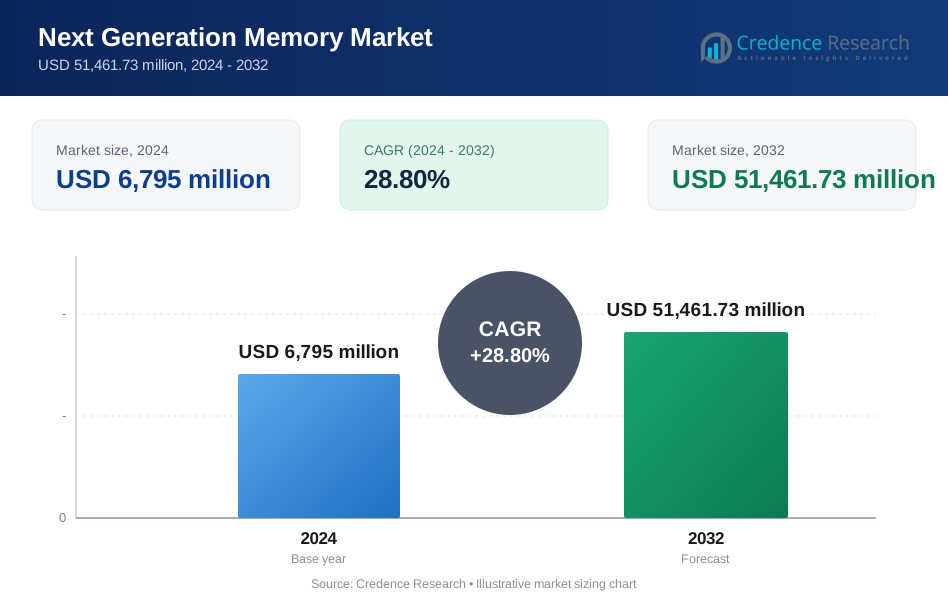
The Next Generation Memory market is projected to grow significantly, increasing from USD 6,795 million in 2024 to USD 51,461.73 million by 2032, reflecting a robust compound annual growth rate (CAGR) of 28.80%.
The Next Generation Memory market is driven by the increasing demand for high-performance computing, artificial intelligence, and data-intensive applications that require faster data processing and storage solutions. Rapid advancements in memory technologies, such as 3D NAND and MRAM, enhance performance and energy efficiency, attracting investments from major tech companies. Additionally, the growing adoption of cloud computing and IoT devices fuels the need for scalable memory solutions, while the surge in big data analytics and machine learning applications further propels market growth. These trends collectively underscore the critical role of Next Generation Memory in powering future technological innovations.Top of Form
The Next Generation Memory market is witnessing significant growth across key regions, including North America and Asia-Pacific. North America, led by the U.S., dominates the market due to its strong technological infrastructure and presence of major players like Micron Technology and Honeywell. Meanwhile, Asia-Pacific is rapidly expanding, driven by semiconductor giants such as Samsung, SK Hynix, and KIOXIA Holdings in countries like South Korea and Japan. Taiwan’s key players, including Winbond and Nanya Technology, further contribute to the region’s growth. This global expansion is supported by continuous innovation and increased demand for advanced memory solutions across industries.
Market Drivers
Increasing Data Volume and Complexity
The exponential growth of data generation, fueled by IoT devices, social media, and various digital sources, necessitates memory solutions capable of efficiently handling massive datasets. For instance, the total amount of data created, captured, copied, and consumed globally is forecast to increase rapidly, reaching 64.2 zettabytes in 2020 and projected to grow to more than 180 zettabytes by 2025. Big Data analytics relies on high-performance memory to process vast amounts of information swiftly. Additionally, artificial intelligence (AI) and machine learning require advanced memory technologies to support complex algorithms and manage large training datasets effectively, further intensifying the demand for next-generation memory solutions.
Cost Effectiveness and Emerging Applications
As data volumes continue to rise, reducing storage costs is imperative for businesses and consumers alike. Next-generation memory technologies present opportunities to lower storage costs while simultaneously enhancing performance. For instance, the amount of generated data is exponentially growing; in 2025, about 175 million terabytes will be generated, which would represent 10 times the volume produced in 2015. Emerging applications, such as autonomous vehicles and virtual/augmented reality, further drive demand for high-performance memory solutions capable of real-time data processing and immersive experiences. Technological advancements, including innovations in 3D NAND Flash and emerging memory technologies like RRAM and PCM, promise to meet these evolving needs while ensuring scalability to accommodate future demands.
Performance Requirements
Modern applications, including real-time analytics, high-performance computing, and gaming, impose stringent performance requirements on memory technologies. These applications necessitate memory with extremely low latency and high bandwidth to ensure seamless operation. Furthermore, next-generation memory technologies are engineered for endurance, capable of withstanding frequent write operations. This resilience makes them particularly well-suited for applications that involve regular data updates, enhancing their overall utility in various sectors.
Power Efficiency
As energy consumption becomes a growing concern, particularly for mobile devices and data centers, power efficiency emerges as a critical driver for next-generation memory technologies. Innovations in memory design contribute to reduced power consumption, which is essential for extending battery life in mobile devices and portable electronics. By improving energy efficiency, these advanced memory solutions not only meet the demands of modern applications but also contribute to sustainability efforts across the technology landscape.
Market Trends
Increasing Adoption of 3D NAND Flash
The market is witnessing a significant shift towards the adoption of 3D NAND Flash technology, primarily due to its numerous advantages over traditional 2D NAND. With higher density capabilities, 3D NAND allows for greater storage capacity within smaller form factors, making it particularly attractive for applications that require efficient use of space, such as mobile devices and compact data centers. For instance, a survey conducted by a leading semiconductor company revealed that 3D NAND technology has enabled a tenfold increase in areal density, surpassing 10 Gb/mm² with 176 layers. Additionally, 3D NAND boasts lower latency and higher bandwidth, making it ideal for demanding environments like high-performance computing and data analytics. As production scales, the cost of 3D NAND is projected to decrease, further enhancing its accessibility to a broader range of applications and driving its integration into various sectors, including consumer electronics and enterprise storage solutions.
Emergence of Innovative Memory Technologies
The emergence of cutting-edge memory technologies is reshaping the landscape of the memory market. Notable among these are Resistive Random Access Memory (RRAM), Phase-Change Memory (PCM), and Magnetic Random Access Memory (MRAM). RRAM is gaining attention for its high density, fast speeds, and low power consumption, positioning it well for applications in neuromorphic computing and embedded systems. PCM, known for its high endurance and rapid write speeds, is being explored for critical applications in data centers and solid-state drives (SSDs). MRAM offers unique advantages such as non-volatility, high endurance, and quick access times, making it suitable for embedded systems and automotive electronics. These emerging technologies reflect a broader trend of increasing focus on energy efficiency, with innovations aimed at minimizing power consumption while maintaining high performance. Additionally, the integration of memory with processing capabilities on the same chip and hybrid solutions combining memory and storage technologies are becoming prevalent. This integration reduces latency and enhances overall system performance, making next-generation memory crucial for expanding applications, particularly in edge computing, IoT, and artificial intelligence. The intensified competition among various players in the market fosters innovation and continuous advancements in research and development, driving the creation of new and improved memory solutions that cater to the evolving needs of modern technology landscapes.
Market Challenges Analysis
Cost and Manufacturing Challenges
The development and manufacturing of next-generation memory technologies present notable challenges, primarily due to high production costs and yield issues. Creating these advanced memory solutions requires substantial upfront investments in research, materials, and complex manufacturing processes, resulting in costs that can exceed those of traditional memory solutions. For instance, the manufacturing costs of high-density DRAM and SRAM are relatively high, and the current production costs of high-bit-density next-generation memories are also elevated. Furthermore, achieving high yields during production is often problematic; new materials and innovative techniques can introduce manufacturing defects, which can hinder efficiency and drive up costs. As manufacturers strive to refine these processes, balancing the need for high-quality output with economic viability becomes a crucial concern.
Reliability and Standardization Issues
Reliability and endurance pose significant challenges for emerging memory technologies, particularly regarding data retention and write cycle limitations. Ensuring long-term data retention is critical, especially for applications operating in harsh environments or over extended periods. Some next-generation memory solutions face inherent limitations on the number of write cycles they can withstand before experiencing performance degradation, potentially compromising their applicability in high-demand scenarios. Additionally, the landscape of next-generation memory technologies is characterized by the need for industry-wide standardization. Establishing uniform standards can be complex, as competing companies often pursue proprietary solutions that may not be compatible with existing hardware and software infrastructures. This lack of compatibility can serve as a barrier to widespread adoption, limiting the growth potential of innovative memory technologies. Moreover, power consumption and heat generation remain pressing concerns, as achieving optimal energy efficiency is critical for high-density and high-performance applications. Managing increased thermal loads from these advanced memory solutions adds another layer of complexity. Finally, the ongoing competition from traditional memory technologies, such as NAND Flash and DRAM, continues to challenge the adoption of next-generation alternatives.
Market Segmentation Analysis:
By Technology:
The Next Generation Memory market is primarily segmented by technology into non-volatile and volatile memory solutions, each addressing distinct application requirements. Non-volatile memory technologies, including Magneto-resistive Random-Access Memory (MRAM), Spin-transfer Torque MRAM (STT-MRAM), and Spin-orbit Torque MRAM (SOT-MRAM), offer significant advantages such as enhanced data retention and reduced power consumption. These technologies are increasingly favored in applications requiring durability and speed, such as data centers and embedded systems. Additionally, advanced memory solutions like Ferroelectric RAM (FRAM) and Resistive Random-Access Memory (ReRAM) are gaining traction due to their scalability and efficiency in handling large datasets. On the other hand, volatile memory technologies, such as Hybrid Memory Cube (HMC) and High-Bandwidth Memory (HBM), are vital for applications demanding high performance and low latency, particularly in gaming, AI, and high-performance computing. The market also includes emerging solutions like 3D XPoint and Nano RAM (NRAM), which promise significant improvements in speed and storage density. With innovations in memory technology, the landscape is rapidly evolving, presenting opportunities across diverse sectors.
By Wafer Size:
The wafer size segment in the Next Generation Memory market encompasses 200 mm and 300 mm wafer technologies, each playing a crucial role in production scalability and cost efficiency. The 300 mm wafer size is gaining dominance due to its ability to deliver higher yields and reduce manufacturing costs, making it increasingly attractive for advanced memory solutions. This larger wafer size allows for more die per wafer, enhancing the overall efficiency of memory production. As manufacturers seek to optimize their operations and meet the rising demand for memory technologies, 300 mm wafers are becoming the preferred choice for large-scale production. Conversely, the 200 mm wafer size remains relevant, particularly for specific applications and legacy technologies. While it offers flexibility and compatibility with existing manufacturing infrastructures, its growth potential may be limited compared to the advancements seen in the 300 mm segment.
Segments:
Based on Technology:
- Non-volatile Memory
- Magneto-resistive Random-Access Memory (MRAM)
- Spin-transfer Torque Magnetic Random-Access Memory (STT-MRAM)
- Spin-orbit Torque Magnetic Random-Access Memory (SOT-MRAM)
- Toggle Mode MRAM
- Ferroelectric RAM (FRAM)
- Resistive Random-Access Memory (ReRAM)/Conductive-Bridging RAM (CBRAM)
- 3D XPoint
- Nano RAM (NRAM)
- Others (Nanobridge, Quantum Dots, Millipede, Molecular, and Transparent/Flexible Memories)
- Volatile Memory
- Hybrid Memory Cube (HMC)
- High-Bandwidth Memory (HBM)
Based on Wafer Size:
- 200 mm
- 300 mm
Based on Application:
- Consumer Electronics
- Enterprise Storage
- Automotive & Transportation
- Military & Aerospace
- Industrial
- Telecommunications
- Energy & Power
- Healthcare
- Agricultural
- Retail
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America holds a significant share of the Next Generation Memory market, accounting for approximately 35% of the global market share. This dominance can be attributed to the region's robust technological infrastructure, presence of leading semiconductor manufacturers, and increasing investments in research and development. The United States, in particular, serves as a hub for innovation in memory technologies, with major players like Intel, Micron Technology, and Western Digital driving advancements in non-volatile and volatile memory solutions. Furthermore, the growing demand for high-performance computing, artificial intelligence, and cloud storage is propelling the adoption of next-generation memory technologies across various sectors, including consumer electronics, automotive, and enterprise storage. The region's strong focus on innovation and collaboration among tech companies enhances its competitive edge, positioning North America as a leader in the evolving memory landscape.
Asia-Pacific
The Asia-Pacific region is expected to witness rapid growth in the Next Generation Memory market, capturing approximately 30% of the global market share. Countries like China, Japan, and South Korea are at the forefront of this expansion, driven by their significant investments in semiconductor manufacturing and technology development. The region is home to major memory manufacturers, including Samsung and SK Hynix, which are continuously advancing their product offerings to meet the increasing demand for high-capacity and high-speed memory solutions. Additionally, the proliferation of IoT devices and the growing need for data storage solutions in sectors such as automotive, telecommunications, and healthcare are further propelling the market. As the Asia-Pacific region continues to embrace digital transformation and technological advancements, it is poised to play a pivotal role in shaping the future of the Next Generation Memory market globally.
Key Player Analysis
- Micron Technology, Inc. (US)
- SK Hynix Inc (South Korea)
- Fujitsu (Japan)
- Everspin Technologies (US)
- KIOXIA Holdings Corporation (Japan)
- Honeywell International, Inc. (US)
- Winbond (Taiwan)
- Nanya Technology (Taiwan)
- Microchip Technology Inc. (US)
- SAMSUNG (South Korea)
Competitive Analysis
The competitive landscape of the Next Generation Memory market is shaped by leading players such as Samsung, Micron Technology, SK Hynix, KIOXIA Holdings, Fujitsu, Honeywell International, Winbond, Microchip Technology, Nanya Technology, and Everspin Technologies. These companies are focusing on technological advancements, extensive R&D investments, and strategic partnerships to gain a competitive edge. Companies are focusing on advancing both volatile and non-volatile memory technologies to meet the growing demand in sectors such as artificial intelligence, IoT, and data centers. Key strategies include developing high-performance memory solutions with improved speed, energy efficiency, and storage capacity. Additionally, firms are investing in scaling production to reduce costs and increase market accessibility. The market is also witnessing increased collaboration between industry leaders and tech firms, fostering innovation and accelerating the adoption of next-generation memory technologies globally.
Recent Developments
- In June 2024, Micron announced the sampling of its next-generation GDDR7 graphics memory with the industry’s highest bit density, leveraging Micron’s 1β (1-beta) DRAM technology.
- In August 2024, SK Hynix showcased its next-generation technology at FMS 2024, including 12-layer HBM3E and 321-layer NAND.
- In April 2024, Everspin launched PERSYST, the new brand for its top-tier persistent memory families.
- In January 2024, KIOXIA highlighted its extensive portfolio of solid state drives (SSDs) and memory solutions at CES 2024.
Market Concentration & Characteristics
The Next Generation Memory market is characterized by a moderate to high level of market concentration, with a few dominant players leading technological advancements and production capacities. These key companies drive innovation through significant investments in research and development, focusing on the development of both volatile and non-volatile memory solutions. The market exhibits characteristics such as high barriers to entry due to the capital-intensive nature of memory manufacturing and the complex technological requirements. Additionally, competition centers around the ability to scale production efficiently while offering high-performance, cost-effective solutions to meet the growing demands in sectors like data centers, artificial intelligence, and telecommunications. Market players are also focused on strategic partnerships, mergers, and collaborations to strengthen their positions and expand their product portfolios. As the demand for faster, more efficient memory solutions rises, these characteristics are expected to intensify, further consolidating market control among leading innovators.
Report Coverage
The research report offers an in-depth analysis based on Technology, Wafer Size, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Next Generation Memory market is expected to witness significant growth driven by increasing demand for high-performance memory in AI, IoT, and data centers.
- Ongoing advancements in non-volatile memory technologies will enable faster data processing and improved storage capabilities.
- The adoption of 3D NAND, MRAM, and ReRAM is likely to expand due to their scalability and energy efficiency.
- Growing demand for energy-efficient memory solutions will fuel innovation, particularly for mobile devices and automotive applications.
- Integration of memory with processing units is expected to reduce latency and enhance system performance across various industries.
- The rise of edge computing will drive the need for faster and more reliable memory solutions at the network edge.
- Increased focus on reducing manufacturing costs will make next-generation memory more accessible to a wider range of applications.
- Emerging applications in autonomous vehicles and AR/VR technologies will boost the demand for high-end memory solutions.
- Strategic partnerships and collaborations will be key in accelerating the adoption of advanced memory technologies.
- Market players will continue to invest heavily in R&D to stay competitive and meet evolving industry requirements.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Increasing Data Volume and Complexity
The exponential growth in data generated by IoT devices, social media, and digital platforms is driving the need for advanced memory solutions capable of handling massive and complex datasets. Next generation memory technologies enable faster processing and efficient storage, which are essential for big data analytics, AI, and machine learning applications.
Cost Effectiveness and Emerging Applications
As data volumes surge, businesses seek to reduce storage costs while improving performance. Next generation memory technologies offer lower cost per bit and higher efficiency, making them attractive for emerging applications such as autonomous vehicles, AR/VR, and real-time analytics that require high-speed, scalable memory.
Performance Requirements for Modern Applications
Applications like real-time analytics, high-performance computing, and gaming demand memory with extremely low latency, high bandwidth, and endurance. Next generation memory technologies are engineered to meet these stringent requirements, enabling seamless operation and frequent data updates across various sectors.
Power Efficiency and Sustainability
With growing concerns over energy consumption in mobile devices and data centers, power-efficient memory solutions are in high demand. Innovations in next generation memory reduce power usage, extend battery life, and support sustainability initiatives, making them critical for modern electronics and infrastructure.
Advancements in Memory Technology
Rapid innovation in memory technologies such as 3D NAND, MRAM, and ReRAM is enhancing storage density, speed, and reliability. These advancements attract investment and accelerate adoption across industries, supporting the development of new applications and driving overall market growth.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Next Generation Memory market?
What factors are driving the growth of the Next Generation Memory market?
What are the key segments within the Next Generation Memory market?
What are some challenges faced by the Next Generation Memory market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Technology
- 1.2.1 Non-volatile Memory (MRAM, STT-MRAM, SOT-MRAM, Toggle Mode MRAM, FRAM, ReRAM/CBRAM, 3D XPoint, NRAM, Others)
- 1.2.2 Volatile Memory (Hybrid Memory Cube, High-Bandwidth Memory)
- 1.3 By Wafer Size
- 1.3.1 200 mm
- 1.3.2 300 mm
- 1.4 By Application
- 1.4.1 Consumer Electronics
- 1.4.2 Enterprise Storage
- 1.4.3 Automotive & Transportation
- 1.4.4 Military & Aerospace
- 1.4.5 Industrial
- 1.4.6 Telecommunications
- 1.4.7 Energy & Power
- 1.4.8 Healthcare
- 1.4.9 Agricultural
- 1.4.10 Retail
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 6,795 million → 2032: USD 51,461.73 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Next Generation Memory Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Next Generation Memory Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Next Generation Memory Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Next Generation Memory Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Next Generation Memory Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Next Generation Memory Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Data Protection, AI and Cybersecurity Compliance
- 9.8 Upcoming Policy Changes and Market Implications
Chapter 10 Global Next Generation Memory Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Next Generation Memory Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 6,795 million → 2032: USD 51,461.73 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Next Generation Memory Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Technology - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Non-volatile Memory (MRAM, STT-MRAM, SOT-MRAM, Toggle Mode MRAM, FRAM, ReRAM/CBRAM, 3D XPoint, NRAM, Others)
- 12.3.7.2 Volatile Memory (Hybrid Memory Cube, High-Bandwidth Memory)
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Wafer Size - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 200 mm
- 12.4.7.2 300 mm
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Consumer Electronics
- 12.5.7.2 Enterprise Storage
- 12.5.7.3 Automotive & Transportation
- 12.5.7.4 Military & Aerospace
- 12.5.7.5 Industrial
- 12.5.7.6 Telecommunications
- 12.5.7.7 Energy & Power
- 12.5.7.8 Healthcare
- 12.5.7.9 Agricultural
- 12.5.7.10 Retail
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Next Generation Memory End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Next Generation Memory Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Next Generation Memory Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Next Generation Memory Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Micron Technology, Inc.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 SK Hynix Inc.
- 18.4 Fujitsu
- 18.5 Everspin Technologies
- 18.6 KIOXIA Holdings Corporation
- 18.7 Honeywell International, Inc.
- 18.8 Winbond
- 18.9 Nanya Technology
- 18.10 Microchip Technology Inc.
- 18.11 SAMSUNG
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

