
Market Overview
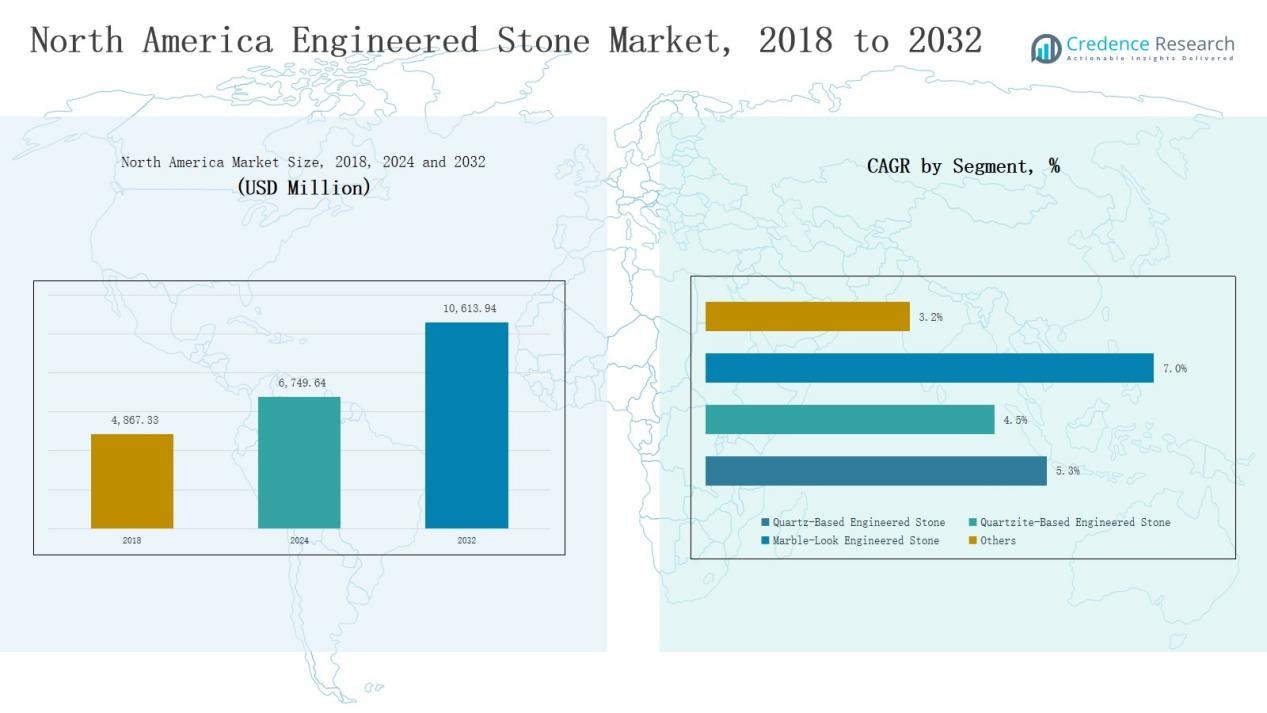
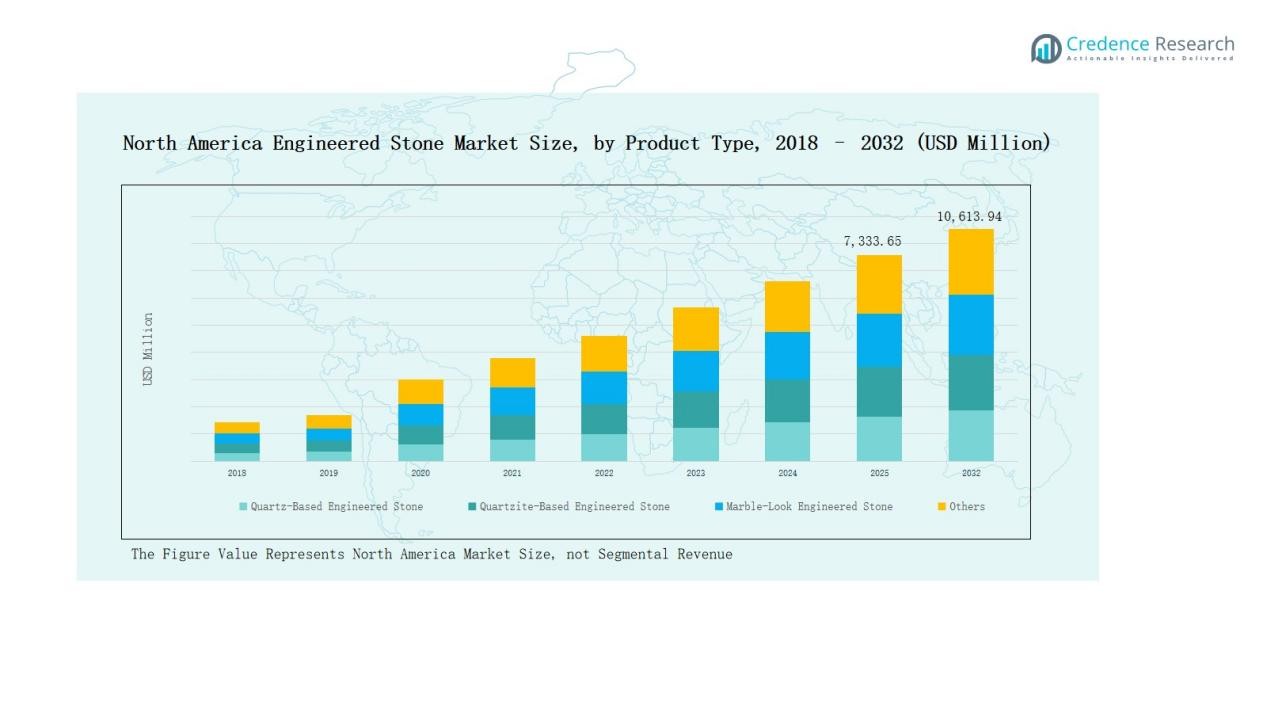
North America Engineered Stone Market size was valued at USD 4,867.33 million in 2018, reached USD 6,749.64 million in 2024, and is anticipated to reach USD 10,613.94 million by 2032, at a CAGR of 5.4% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| North America Engineered Stone Market Size 2024 | USD 6,749.64 Million |
| North America Engineered Stone Market, CAGR | 5.4% |
| North America Engineered Stone Market Size 2032 | USD 10,613.94 Million |
The North America Engineered Stone Market is shaped by prominent players including Cambria Company LLC, Caesarstone US, Daltile, MSI Surfaces, Silestone, Hanstone Quartz US, Meta Surfaces, Vadara Quartz, Stone Panels International LLC, and Absolute Marble & Granite. These companies compete through extensive product portfolios, sustainable production methods, and strong distribution networks that ensure widespread availability across residential and commercial projects. The United States emerged as the leading regional market, holding a 72% share in 2024, driven by high residential remodeling activity, commercial construction expansion, and the strong presence of major manufacturers.
Market Insights
- The North America Engineered Stone Market grew from USD 4,867.33 million in 2018 to USD 6,749.64 million in 2024 and is projected to reach USD 10,613.94 million by 2032, at a CAGR of 5.4%.
- Leading players include Cambria Company LLC, Caesarstone US, Daltile, MSI Surfaces, Silestone, Hanstone Quartz US, Meta Surfaces, Vadara Quartz, Stone Panels International LLC, and Absolute Marble & Granite, competing through strong portfolios and sustainable practices.
- Quartz-Based Engineered Stone held the dominant position with 56% share in 2024, supported by durability, stain resistance, design variety, and increasing adoption in both residential and commercial applications.
- Residential applications led with 61% share in 2024, driven by growing home renovation projects, modern kitchen and bathroom installations, and strong preference for affordable, durable, and low-maintenance surfaces.
- The United States commanded 72% share in 2024, followed by Canada with 18% and Mexico with 10%, with Mexico identified as the fastest-growing regional market.
Market Segment Insights
By Product Type
Quartz-Based Engineered Stone dominated the North America market with over 56% share in 2024. Its leadership is attributed to superior durability, stain resistance, and wide design options, making it the preferred choice for both residential and commercial projects. Growing awareness of low-maintenance surfaces and the ability to replicate natural aesthetics without high costs further strengthen demand. Sustainability initiatives promoting recycled quartz in production also support expansion, positioning quartz-based products as the most resilient segment in the region.
- For instance, MSI Surfaces added new Calacatta-inspired quartz designs, such as Calacatta Miraggio Cove, targeting demand for premium yet low-maintenance kitchen and bath applications.
By Application
Residential applications led the North America Engineered Stone Market with 61% share in 2024. Rising investments in housing projects, coupled with growing demand for modern kitchens and bathrooms, drive adoption. Homeowners prefer engineered stone for countertops, flooring, and wall cladding due to its affordability and ease of maintenance compared to natural stone. The surge in renovation activities and increasing preference for contemporary interior finishes further boost residential demand, ensuring this segment maintains a strong lead over commercial usage.
- For instance, Cambria introduced new quartz designs under its Luxury Series, emphasizing high-performance surfaces for residential kitchen and bath renovation projects.
By End-Use Industry
Construction and Infrastructure emerged as the leading end-use industry, accounting for 58% share in 2024. Large-scale urbanization, commercial complexes, and public infrastructure projects continue to fuel growth. Contractors and developers value engineered stone for its cost efficiency, durability, and compliance with sustainability codes in green building certifications. Expansion of smart cities and government investments in modern infrastructure further elevate the use of engineered stone, reinforcing construction and infrastructure as the dominant driver of market revenue in North America.
Key Growth Drivers
Rising Demand for Residential Remodeling
The surge in home renovation projects strongly supports market expansion. Homeowners increasingly prefer engineered stone for countertops, flooring, and wall cladding due to durability and low maintenance. Rising disposable incomes and growing interest in modern interiors accelerate replacement of traditional materials. The ability of engineered stone to replicate marble and granite aesthetics at lower cost further boosts adoption. Strong residential demand ensures steady revenue, making remodeling a central driver of growth across U.S., Canada, and Mexico housing markets.
- For instance, Cambria expanded its production facility in Minnesota to meet the rising residential demand for engineered quartz countertops, strengthening its supply capacity across North America.
Expansion of Commercial Infrastructure
Rapid growth in commercial real estate projects, including offices, hotels, and retail spaces, drives adoption of engineered stone. Developers favor engineered stone surfaces for their high resistance to wear, cost-effectiveness, and design flexibility in high-traffic environments. Increased foreign investment in urban projects and corporate expansions across major cities amplify demand. Sustainability certifications in commercial construction also promote engineered surfaces as eco-friendly alternatives. The combination of durability and aesthetics makes engineered stone the material of choice for commercial infrastructure.
Technological Advancements in Manufacturing
Innovation in engineered stone manufacturing significantly enhances market potential. Advancements in resin binders, surface finishes, and recycled content integration improve product strength, eco-friendliness, and design variety. Producers now offer non-silica and antimicrobial surfaces that appeal to health-conscious and environmentally aware consumers. Automation in production facilities further increases efficiency and consistency, reducing costs. These improvements not only broaden product appeal but also address sustainability concerns, enabling manufacturers to tap into premium markets and meet stringent regulatory and design standards.
- For instance, Cosentino launched its Silestone XM series, featuring hybrid mineral composite technology with 20% recycled materials, engineered to lower environmental impact while maintaining versatility in surface designs.
Key Trends & Opportunities
Growing Preference for Sustainable Surfaces
Sustainability is a rising trend shaping market demand. Consumers and builders increasingly prefer eco-friendly materials, driving adoption of engineered stone with recycled quartz content and lower environmental impact. Green building standards in North America promote sustainable products in residential and commercial projects. Manufacturers are introducing water-efficient and low-emission production methods to align with environmental regulations. This shift creates strong opportunities for companies that can offer durable, stylish, and sustainable engineered stone products aligned with eco-conscious consumer expectations.
- For instance, Cosentino introduced new Dekton collections manufactured with 100% renewable electricity and recycled water, reducing its production-related carbon footprint significantly.
Increased Customization and Design Innovation
Customization is emerging as a key opportunity for growth in the market. Consumers demand unique designs, finishes, and textures, ranging from marble-look surfaces to modern matte and bold color palettes. Advances in digital imaging and surface engineering enable manufacturers to replicate natural stone aesthetics with high precision. Architects and interior designers increasingly recommend engineered stone for personalized projects in both residential and commercial spaces. The ability to deliver customized, high-value surfaces creates new revenue streams and competitive differentiation.
- For instance, LX Hausys launched new HIMACS Solid Surfaces featuring on-demand textures and thermoformable qualities, allowing architects to create custom curved or seamless structures for commercial spaces.
Key Challenges
High Silica Content and Health Concerns
Concerns over crystalline silica exposure pose a major challenge. Engineered stone production and fabrication processes release fine silica dust, linked to respiratory diseases like silicosis. Growing regulatory scrutiny and stricter workplace safety standards in the U.S. and Canada increase compliance costs for manufacturers and fabricators. Public health campaigns further highlight risks, affecting consumer perception. Addressing silica-related concerns requires investment in safer formulations, improved worker protection, and innovative product alternatives, without which long-term market growth may face limitations.
Rising Competition from Alternative Materials
The market faces stiff competition from substitutes such as natural stone, ceramics, laminates, and solid surfaces. Many consumers still perceive natural stone as more prestigious, while ceramics offer cost advantages and versatility. Rapid advancements in alternative materials, including lightweight porcelain slabs and hybrid composites, intensify competitive pressure. Builders and designers may shift preferences toward these alternatives when cost or design specifications align. To sustain growth, engineered stone suppliers must differentiate through innovation, branding, and highlighting performance benefits.
Volatility in Raw Material Prices
Fluctuating costs of raw materials, particularly quartz, resin, and pigments, create challenges for manufacturers. Price instability disrupts production planning and profitability, especially for mid-scale players with limited procurement leverage. Global supply chain disruptions further exacerbate shortages and delays in sourcing. These fluctuations force companies to either absorb higher costs or pass them on to consumers, potentially affecting demand. Managing raw material volatility through diversified sourcing strategies and vertical integration becomes crucial for maintaining competitiveness in the market.
Regional Analysis
United States
The United States dominated the North America Engineered Stone Market with 72% share in 2024. Strong residential remodeling activity and high adoption of premium kitchen and bathroom surfaces drive growth. Consumers prefer quartz-based products for their durability, low maintenance, and ability to replicate natural stone at competitive cost. Rapid urbanization, expanding commercial construction, and investments in retail and hospitality spaces further increase demand. The country’s advanced distribution networks and presence of leading manufacturers strengthen supply capabilities. It benefits from innovation in silica-free surfaces, aligning with sustainability standards and health safety regulations.
Canada
Canada held 18% share in 2024, supported by steady demand from both residential and commercial sectors. Growth is driven by rising investments in urban housing projects and public infrastructure. Consumers increasingly favor engineered stone for modern interiors due to its resilience and wide design options. Developers adopt engineered stone in high-traffic spaces such as offices and shopping complexes. The market benefits from government initiatives encouraging sustainable construction practices. It remains an attractive destination for suppliers offering eco-friendly and customizable surface solutions.
Mexico
Mexico accounted for 10% share in 2024, with growth supported by expanding construction and infrastructure projects. Rising disposable incomes and increasing urban housing projects fuel residential adoption of engineered stone surfaces. The country sees growing use in commercial buildings, particularly hotels and retail outlets targeting international tourism. Domestic suppliers face challenges in matching the quality of imported premium brands, but demand continues to rise. Government focus on modern infrastructure development strengthens long-term opportunities. It remains the fastest-growing regional market due to rising investments and affordable housing demand.
Market Segmentations:
By Product Type
- Quartz-Based Engineered Stone
- Quartzite-Based Engineered Stone
- Marble-Look Engineered Stone
- Others
By Application
- Residential
- Commercial
By End-Use Industry
- Construction and Infrastructure
- Interior Design and Decoration
- Others
By Region
- U.S.
- Canada
- Mexico
Competitive Landscape
The competitive landscape of the North America Engineered Stone Market is characterized by the presence of established global brands and regional manufacturers competing on product quality, design variety, and distribution strength. Leading players such as Cambria Company LLC, Caesarstone US, MSI Surfaces, Silestone, and Hanstone Quartz US maintain strong positions through wide product portfolios, advanced finishes, and effective branding strategies. Companies emphasize sustainable production practices, including the use of recycled materials and reduced silica content, to address regulatory pressures and changing consumer preferences. Expansion into commercial projects, partnerships with contractors, and strong retail presence further enhance competitiveness. Emerging players like Meta Surfaces and Vadara Quartz are gaining traction with innovative designs and tailored solutions for niche customer segments. The market remains moderately concentrated, with top companies holding significant shares, but opportunities for differentiation exist in customization, eco-friendly offerings, and technological innovation.
Key Players
- Cambria Company LLC
- Caesarstone US
- Daltile
- MSI Surfaces
- Silestone
- Meta Surfaces
- Vadara Quartz
- Hanstone Quartz US
- Stone Panels International LLC
- Absolute Marble & Granite
Recent Developments
- In July 2025, Caesarstone introduced its Caesarstone ICON™, a crystalline-silica-free surface made with around 80% recycled materials.
- In July 2025, Cosentino expanded its footprint by opening new Cosentino City showrooms in Dallas, Honolulu, and Richmond.
- In April 2025, Vadara Quartz formed a distribution partnership with CRS Marble & Granite (USA) to expand its artisan quartz reach.
- In December 2024, Daltile launched new extra-large porcelain and quartz slab collections across North America.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Application, End Use Industry and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand will rise with continued growth in residential remodeling projects.
- Commercial infrastructure expansion will drive wider adoption of engineered stone.
- Sustainable and eco-friendly surfaces will gain stronger preference among buyers.
- Customization in colors, textures, and finishes will attract design-focused consumers.
- Technological innovation will improve product durability and reduce silica content.
- Distribution networks will expand through partnerships with contractors and retailers.
- Renovation trends in kitchens and bathrooms will support long-term market growth.
- Increased investments in hospitality and retail sectors will boost usage in high-traffic spaces.
- Competition from ceramics and natural stone will encourage stronger product differentiation.
- Government focus on sustainable building standards will enhance adoption across new projects.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Surge in Residential Remodeling
Homeowners across North America are increasingly investing in kitchen and bathroom renovations, favoring engineered stone for its durability, low maintenance, and ability to replicate natural stone aesthetics at a lower cost. This trend is especially strong in the U.S., driving steady demand for engineered stone surfaces.
Expansion of Commercial Infrastructure
Rapid growth in commercial real estate, including offices, hotels, and retail spaces, is boosting the adoption of engineered stone due to its cost-effectiveness, design flexibility, and high resistance to wear in high-traffic environments. Developers and contractors prefer engineered stone for meeting sustainability codes and modern design requirements.
Technological Advancements in Manufacturing
Innovations such as improved resin binders, non-silica formulations, and the integration of recycled content are enhancing product strength, eco-friendliness, and design variety. These advancements help manufacturers address health concerns, regulatory standards, and appeal to premium market segments.
Rising Preference for Sustainable and Eco-Friendly Surfaces
Growing environmental awareness among consumers and stricter green building standards are driving demand for engineered stone products with recycled materials and lower environmental impact. Manufacturers are responding with water-efficient, low-emission production methods and sustainable product lines.
Customization and Design Innovation
Increasing demand for unique colors, textures, and finishes is pushing manufacturers to offer highly customizable engineered stone surfaces. Advances in digital imaging and surface engineering allow for precise replication of natural stone and bespoke designs, attracting architects, designers, and homeowners seeking personalized solutions.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for North America Engineered Stone Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the North America Engineered Stone Market projected to grow between 2025 and 2032?
Which North America Engineered Stone Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the North America Engineered Stone Market?
Who are the leading companies in the North America Engineered Stone Market?
Which region commanded the largest share of the North America Engineered Stone Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Application
- 1.2.1 Residential
- 1.2.2 Commercial
- 1.3 By Product Type
- 1.3.1 Quartz-Based Engineered Stone
- 1.3.2 Quartzite-Based Engineered Stone
- 1.3.3 Marble-Look Engineered Stone
- 1.3.4 Others
- 1.4 By End-Use Industry
- 1.4.1 Construction and Infrastructure
- 1.4.2 Interior Design and Decoration
- 1.4.3 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 6,749.64 million → 2032: USD 10,613.94 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global North America Engineered Stone Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global North America Engineered Stone Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global North America Engineered Stone Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global North America Engineered Stone Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global North America Engineered Stone Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global North America Engineered Stone Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global North America Engineered Stone Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global North America Engineered Stone Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 6,749.64 million → 2032: USD 10,613.94 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global North America Engineered Stone Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Application - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Residential
- 12.3.7.2 Commercial
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Product Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Quartz-Based Engineered Stone
- 12.4.7.2 Quartzite-Based Engineered Stone
- 12.4.7.3 Marble-Look Engineered Stone
- 12.4.7.4 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By End-Use Industry - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Construction and Infrastructure
- 12.5.7.2 Interior Design and Decoration
- 12.5.7.3 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global North America Engineered Stone End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global North America Engineered Stone Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global North America Engineered Stone Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global North America Engineered Stone Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Cambria Company LLC
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Caesarstone US
- 18.4 Daltile
- 18.5 MSI Surfaces
- 18.6 Silestone
- 18.7 Hanstone Quartz US
- 18.8 Meta Surfaces
- 18.9 Vadara Quartz
- 18.10 Stone Panels International LLC
- 18.11 Absolute Marble & Granite
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

