
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| North America Reusable Water Bottles Market Size 2023 | USD 1,972.04 Million |
| North America Reusable Water Bottles Market, CAGR | 5.11% |
| North America Reusable Water Bottles Market Size 2032 | USD 3,108.88 Million |
Market Overview
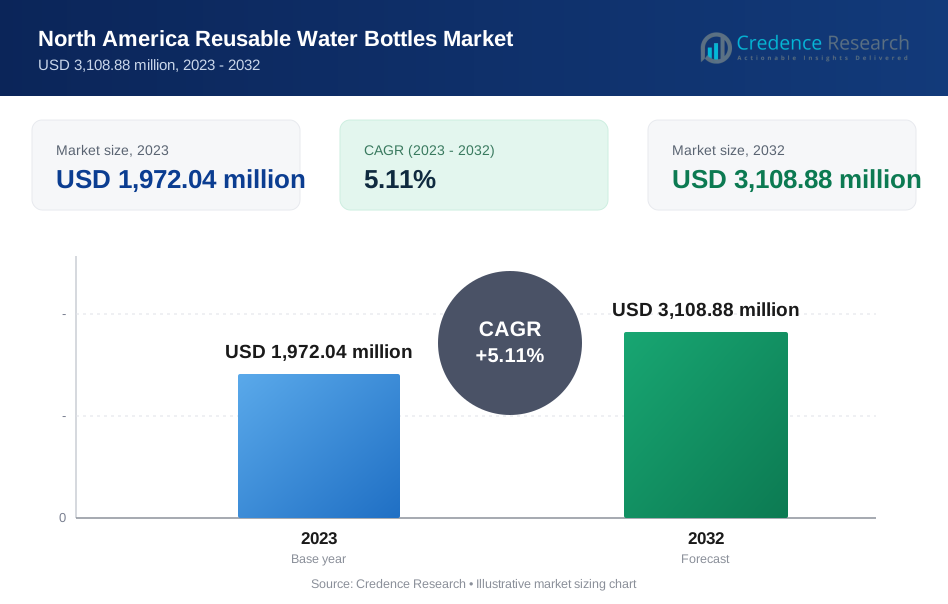
The North America Reusable Water Bottles Market is projected to grow from USD 1,972.04 million in 2023 to an estimated USD 3,108.88 million by 2032, with a compound annual growth rate (CAGR) of 5.11% from 2024 to 2032. This growth is attributed to increasing environmental awareness and the growing preference for sustainable and eco-friendly products. The market's robust expansion highlights the significant shift towards reducing single-use plastic consumption, driven by both consumer behavior and regulatory measures. As more consumers opt for reusable alternatives, manufacturers are focusing on innovative product designs and materials, further propelling market growth.
Key drivers of the North America Reusable Water Bottles Market include heightened environmental consciousness, stringent government regulations on plastic usage, and rising health awareness among consumers. The trend towards personalized and stylish water bottles is also contributing to market growth, with manufacturers offering a wide range of designs, colors, and functionalities to cater to diverse consumer preferences. Additionally, the increasing adoption of reusable water bottles in workplaces, schools, and outdoor activities is further boosting market demand. Innovations in materials, such as BPA-free plastics and stainless steel, are enhancing the durability and appeal of these products, supporting their widespread adoption.
Geographically, the United States holds the largest share of the North America Reusable Water Bottles Market, followed by Canada and Mexico. The strong market presence in the U.S. is driven by high consumer awareness, well-established retail channels, and active participation in sustainability initiatives. Major players in the market include companies like S'well, Thermos LLC, CamelBak Products LLC, Contigo, and Hydro Flask. These key players are focusing on strategic partnerships, product innovation, and expanding their distribution networks to strengthen their market position and meet the growing consumer demand for eco-friendly water bottles. The competitive landscape is characterized by continuous product development and branding efforts aimed at capturing a larger market share.
Market Drivers
Environmental Awareness and Sustainability Initiatives
The growing environmental awareness among consumers is a significant driver of the North America Reusable Water Bottles Market. As concerns about plastic pollution and its impact on ecosystems intensify, more individuals are seeking sustainable alternatives to single-use plastics. This shift is further supported by numerous sustainability initiatives led by governments, non-governmental organizations, and corporations. Campaigns aimed at reducing plastic waste have gained momentum, encouraging consumers to adopt reusable products. The increasing visibility of environmental issues, coupled with educational programs and media coverage, has heightened public consciousness about the detrimental effects of plastic waste, driving the demand for reusable water bottles. This trend is expected to continue as sustainability becomes an integral part of consumer lifestyle choices.
Health Consciousness and Hydration Awareness
Another key driver of the reusable water bottles market is the rising health consciousness and awareness of the importance of proper hydration. Consumers are increasingly mindful of their health and wellness, leading to a growing preference for products that support a healthy lifestyle. Reusable water bottles offer a convenient way to stay hydrated throughout the day, encouraging individuals to drink more water and reduce their intake of sugary beverages. Additionally, concerns about the potential health risks associated with plastic chemicals, such as BPA (bisphenol A), have prompted consumers to seek safer alternatives. Manufacturers have responded by developing BPA-free and non-toxic reusable bottles, further boosting their appeal. The emphasis on health and wellness is likely to sustain the demand for reusable water bottles as part of a broader trend towards healthier living.
Technological Innovations and Product Diversification
Technological advancements and product diversification are critical factors driving the growth of the North America Reusable Water Bottles Market. Manufacturers are continuously innovating to enhance the functionality, design, and materials of reusable water bottles. Innovations such as vacuum insulation technology, which keeps beverages at desired temperatures for extended periods, have significantly increased the utility and attractiveness of these products. Additionally, the incorporation of smart features, such as hydration tracking and integration with mobile apps, appeals to tech-savvy consumers. The market is also witnessing diversification in terms of designs, sizes, and materials, catering to a wide range of consumer preferences. From sleek stainless steel bottles to eco-friendly bamboo and glass options, the variety available in the market ensures that consumers can find products that meet their specific needs and preferences, driving market growth.
Government Regulations and Corporate Responsibility
Government regulations aimed at reducing plastic waste and promoting sustainable practices are playing a crucial role in driving the North America Reusable Water Bottles Market. Various states and municipalities have implemented bans on single-use plastics, including plastic bottles, straws, and bags, encouraging the use of reusable alternatives. These regulatory measures are often accompanied by public awareness campaigns that further promote the adoption of sustainable products. In addition to government actions, corporate responsibility initiatives are also contributing to market growth. Many companies are adopting environmentally friendly practices and promoting reusable products as part of their corporate social responsibility (CSR) efforts. Retailers and brands are increasingly offering incentives for customers to switch to reusable water bottles, such as discounts or loyalty points. These combined efforts from both the public and private sectors are creating a favorable environment for the growth of the reusable water bottles market.
Market Trends
Rise of Eco-Friendly Materials
A prominent trend in the North America Reusable Water Bottles Market is the increasing use of eco-friendly materials. Consumers are gravitating towards products made from sustainable resources such as stainless steel, glass, and bamboo. These materials are not only environmentally friendly but also offer durability and aesthetic appeal. Manufacturers are capitalizing on this trend by introducing a variety of eco-conscious options that cater to the growing demand for sustainable products. For instance, governments around the world are taking steps to discourage the use of single-use plastic water bottles and encourage the use of reusable bottles made of glass, metal, and other environmentally benign and secure materials.
Innovative Product Designs
The market is witnessing a surge in innovative product designs, focusing on functionality and user convenience. Features such as built-in filters, infusers, and compartments for storing supplements or snacks are becoming popular. Additionally, ergonomic designs that enhance portability and ease of use are in high demand. Companies are also experimenting with stylish and customizable designs, allowing consumers to personalize their bottles with colors, patterns, and accessories.
Smart Water Bottles
The advent of smart technology has reached the reusable water bottles market, leading to the development of smart water bottles. These bottles come equipped with sensors and Bluetooth connectivity, allowing users to track their water intake through mobile apps. Some smart bottles also provide reminders to drink water, helping users maintain their hydration levels. This integration of technology appeals to health-conscious consumers and tech enthusiasts, driving the adoption of smart reusable water bottles.
Corporate and Workplace Adoption
There is a growing trend of corporate and workplace adoption of reusable water bottles. Many companies are encouraging their employees to use reusable bottles as part of their sustainability initiatives. This trend is often supported by providing branded reusable bottles to employees and installing water refill stations in office premises. Such initiatives not only reduce plastic waste but also promote a culture of health and wellness within the workplace.
Educational Campaigns and Advocacy
Educational campaigns and advocacy efforts are playing a significant role in promoting the use of reusable water bottles. Organizations and influencers are leveraging social media platforms to spread awareness about the environmental impact of single-use plastics and the benefits of reusable alternatives. These campaigns often feature engaging content, such as infographics, videos, and challenges, to motivate consumers to make the switch to reusable bottles.
Expansion of Distribution Channels
The expansion of distribution channels is another notable trend in the market. Reusable water bottles are increasingly available through a variety of retail outlets, including supermarkets, specialty stores, and online platforms. E-commerce, in particular, has become a crucial channel, offering consumers a wide range of choices and the convenience of home delivery. The growth of online retail is facilitating easier access to a diverse array of reusable water bottles, contributing to market growth.
Focus on Health and Wellness
The focus on health and wellness continues to drive the market for reusable water bottles. Consumers are becoming more health-conscious and are looking for products that support their lifestyle choices. Reusable water bottles that promote hydration and offer features like BPA-free materials are in high demand. The market is responding with products that cater to this trend, emphasizing the health benefits of regular water consumption and the safety of the materials used.
Market Restraints and Challenges
High Initial Cost
One of the primary restraints in the North America Reusable Water Bottles Market is the high initial cost of reusable bottles compared to single-use plastic bottles. Although reusable bottles offer long-term savings, the upfront expense can deter cost-sensitive consumers from making the switch. High-quality materials such as stainless steel and glass, along with advanced features like insulation and smart technology, further increase the price point. This cost barrier can limit market penetration, especially among consumers who prioritize immediate affordability over long-term benefits.
Consumer Habits and Convenience
Changing consumer habits is a significant challenge for the market. Many consumers still favor the convenience of single-use plastic bottles, which are widely available and require no maintenance. Reusable bottles, on the other hand, necessitate regular cleaning and care, which some users may find cumbersome. Overcoming ingrained habits and encouraging a shift towards sustainable practices require persistent education and motivation, posing a challenge for market players.
Limited Awareness and Misconceptions
Despite growing environmental awareness, there remains a segment of the population with limited knowledge about the benefits of reusable water bottles. Misconceptions about the safety and hygiene of reusable bottles can also hinder market growth. For instance, concerns about bacterial contamination due to improper cleaning can dissuade potential users. Addressing these misconceptions and enhancing public awareness through effective communication strategies is crucial for market expansion.
Competitive Landscape and Market Saturation
The reusable water bottles market is becoming increasingly competitive, with numerous brands offering a wide range of products. This saturation makes it challenging for new entrants to establish themselves and for existing players to differentiate their products. Intense competition can lead to price wars, which might affect profit margins. Companies need to continuously innovate and invest in marketing to maintain their competitive edge, adding to operational costs.
Regulatory and Compliance Issues
Navigating regulatory and compliance issues presents another challenge for the market. Reusable water bottles must meet stringent safety and quality standards, which vary across regions and countries. Ensuring compliance with these regulations requires significant investment in testing and certification, which can be a financial burden, particularly for smaller companies. Non-compliance can lead to product recalls, legal liabilities, and reputational damage, further complicating market dynamics.
Supply Chain Disruptions
Supply chain disruptions pose a notable challenge for the market. Factors such as raw material shortages, logistical issues, and manufacturing delays can impact the timely production and delivery of reusable water bottles. The reliance on global supply chains also exposes manufacturers to risks associated with geopolitical tensions, trade policies, and global economic fluctuations. Ensuring a resilient and efficient supply chain is critical for maintaining market stability and meeting consumer demand.
Market Segmentation Analysis
By Material Type
Glass reusable water bottles are preferred for their purity and ability to preserve the taste of beverages, making them popular among health-conscious and environmentally aware consumers due to their non-toxic materials and recyclability, despite their fragility and higher cost. Stainless steel bottles, known for their durability, corrosion resistance, and temperature maintenance, appeal to a broad range of consumers seeking long-lasting and BPA-free options, contributing to their strong market presence with modern designs. Plastic bottles, especially BPA-free ones, are lightweight and affordable, offering convenience and a variety of designs, though environmental and health concerns persist, which innovations in bio-plastics and recycled plastics aim to address. Silicon bottles are favored for their flexibility, durability, and portability, appealing to travelers and outdoor enthusiasts despite higher costs and limited market availability. Other materials like aluminum, bamboo, and hybrid combinations cater to niche markets with specific preferences, offering eco-friendly and durable options that diversify the market.
By Distribution Channel
Specialty stores cater to consumers seeking high-quality and premium reusable water bottles, offering a curated selection of innovative, design-centric products that allow brands to differentiate themselves through exclusive offerings and personalized shopping experiences. Convenience stores provide easy access for on-the-go consumers with affordable and popular brands, appealing to budget-conscious and impulse buyers despite a more limited selection. Supermarkets and hypermarkets serve as key distribution channels due to their extensive reach and diverse product range, attracting a broad spectrum of consumers and benefiting from high foot traffic ideal for mass-market products and promotions. Additionally, the "Others" segment, including online retailers, department stores, and direct sales, is growing significantly, especially e-commerce, which offers vast choices, home delivery convenience, and targeted marketing strategies, enhancing brand visibility and customer engagement.
Segments
Based on Material Type
- Glass
- Stainless Steel
- Plastic
- Silicon
- Others
Based on Distribution Channel
- Specialty Stores
- Convenience Stores
- Supermarkets and Hypermarkets
- Others
Regional Analysis
United States (65%):
The United States holds the largest share of the North America Reusable Water Bottles Market, accounting for approximately 65% of the market. This dominance is driven by high consumer awareness and robust environmental initiatives aimed at reducing single-use plastic consumption. The U.S. market benefits from a well-established retail infrastructure and significant consumer demand for sustainable and health-conscious products. The presence of major market players, such as S'well, Hydro Flask, and CamelBak, further strengthens the market. These companies invest heavily in marketing, innovation, and product diversification, catering to a wide array of consumer preferences. Additionally, stringent regulations on plastic usage in several states, along with active participation in global sustainability campaigns, contribute to the market’s growth.
Canada (20%):
Canada represents around 20% of the North America Reusable Water Bottles Market. Similar to the U.S., Canada has a strong focus on environmental sustainability, supported by government regulations and public awareness campaigns. Canadian consumers are increasingly shifting towards eco-friendly products, including reusable water bottles, to reduce their environmental footprint. The market in Canada is characterized by a preference for high-quality, durable products, often made from stainless steel and glass. Retailers and e-commerce platforms play a crucial role in making these products accessible to a broad consumer base. Canadian companies and international brands alike are capitalizing on the growing demand by offering a diverse range of products tailored to local tastes and preferences.
Key players
- Smith Corporation
- Newell Brands, Inc.
- Vista Outdoor, Inc. (CamelBak Products LLC)
- Groupe SEB
- Tupperware Brands Company
- SIGG Switzerland Bottles AG (Zhejiang Haers Vacuum Containers Co., Ltd.)
- Klean Kanteen
- Hydaway LLC
- Bulletin Bottle
Competitive Analysis
The North America Reusable Water Bottles Market is highly competitive, with key players leveraging innovation, brand reputation, and strategic marketing to capture market share. A. O. Smith Corporation and Newell Brands, Inc. stand out due to their extensive product portfolios and strong distribution networks. Vista Outdoor, Inc., through its CamelBak Products LLC, maintains a significant market presence with its high-performance, adventure-oriented designs. Groupe SEB and Tupperware Brands Company capitalize on their established consumer bases and global reach. SIGG Switzerland Bottles AG, now under Zhejiang Haers Vacuum Containers Co., Ltd., is renowned for its premium quality and design aesthetics. Klean Kanteen focuses on sustainability and eco-friendly materials, appealing to environmentally conscious consumers. Hydaway LLC and Bulletin Bottle differentiate themselves with unique, innovative products that cater to niche markets. The competitive landscape is marked by continuous innovation, brand loyalty, and a strong emphasis on sustainability.
Recent Developments
In April 2023, Nalgene announced its shift to producing reusable bottles using Eastman’s Tritan Renew, a material certified as 50% recycled through the mass balance method. This transition began in 2020 and concluded in January 2023. Throughout the conversion, Nalgene successfully repurposed over 2.35 million pounds of plastic waste. This strategic move aligns with Nalgene’s commitment to sustainability, enhancing its product offerings with environmentally friendly materials while maintaining the quality and durability that consumers expect from the brand.
In February 2023, SIGG Switzerland AG participated in the ABN AMRO Open tennis tournament, held at Rotterdam Ahoy in Rotterdam, Netherlands. During the event, SIGG provided all players with reusable drinking bottles made from Tritan Renew, a highly impact- and scratch-resistant material. The Tritan used in these bottles is certified by the International Sustainability and Carbon Certification (ISCC), reflecting SIGG's dedication to sustainability and high-quality standards. This initiative underscores SIGG’s role in promoting eco-friendly practices in sports events.
In December 2022, Klean Kanteen, along with MiiR, Stanley, and YETI, established the Drinkware CoLab. This alliance aims to reduce carbon emissions across their supply chains, supporting the Outdoor Industry Association’s (OIA) objective of becoming the first climate-positive industry by 2030. These four brands, as members of OIA’s Climate Action Corps, are committed to generating a net-positive environmental impact, surpassing the goal of net-zero emissions. This collaboration exemplifies the industry’s collective effort towards sustainable and climate-conscious business practices.
In August 2022, S’well introduced its Elements Collection, featuring three high-gloss bottles named ‘Blue Marble’, ‘Charcoal Granite’, and ‘Opal Marble’. These bottles showcase earthy shades and tones, offering both aesthetic appeal and functionality. Made with double-walled stainless steel insulation, they keep beverages cold for 24 hours and hot for 12 hours, and their design prevents condensation. The wide-mouth opening allows for easy ice addition, and the drip-free sipping feature enhances user convenience, making them a practical choice for consumers.
In June 2022, Klean Kanteen unveiled its Rise drinkware collection, available for retail in January 2023. The collection includes five sizes and shapes of BPA-free drinkware, crafted from certified 90% post-consumer recycled 18/8 stainless steel. Featuring double-walled construction and Klean Kanteen's Climate Lock vacuum insulation, these products ensure optimal temperature retention. Additionally, the impact-resistant base cap enhances durability and stability, reflecting Klean Kanteen's commitment to sustainability and quality.
In June 2022, Tupperware Brands Corporation teamed up with Vera Bradley, a U.S.-based fashion company, to launch a limited edition collection of reusable ECO+ water bottles, snack sets, and sandwich keepers. This exclusive line features three distinct patterns: Daisy Smile, Falling Daisies, and Sunflower collections. The collaboration merges Tupperware’s expertise in reusable products with Vera Bradley’s signature design aesthetics, offering consumers stylish and eco-friendly options for their daily needs.
Market Concentration and Characteristics
The North America Reusable Water Bottles Market is characterized by moderate to high market concentration, with a few key players such as A. O. Smith Corporation, Newell Brands, Inc., and Vista Outdoor, Inc. (CamelBak Products LLC) holding significant market shares. These companies, along with other prominent brands like Klean Kanteen and SIGG Switzerland AG, drive innovation and set industry standards through their extensive product portfolios and strong distribution networks. The market is marked by a strong focus on sustainability, health-consciousness, and technological advancements, with products ranging from eco-friendly materials to smart water bottles. The competitive landscape encourages continuous innovation and strategic collaborations, ensuring a dynamic and evolving market.
Report Coverage
The research report offers an in-depth analysis based on Material Type and Distribution Channel. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The North America Reusable Water Bottles Market is expected to maintain steady growth, driven by increasing environmental awareness and consumer demand for sustainable products.
- Future advancements in technology will lead to the development of smart water bottles with enhanced features such as hydration tracking and integration with mobile apps.
- The market will see a rise in the use of eco-friendly materials like biodegradable plastics and recycled metals, catering to environmentally conscious consumers.
- Manufacturers will continue to innovate, offering diverse and customizable designs to meet varied consumer preferences and enhance user experience.
- More corporations will adopt sustainability initiatives, encouraging the use of reusable water bottles among employees and integrating eco-friendly practices into their operations.
- Stricter government regulations on single-use plastics will further boost the demand for reusable water bottles, fostering a favorable regulatory environment for market growth.
- Rising health consciousness among consumers will drive the demand for BPA-free and non-toxic water bottles, emphasizing the health benefits of regular hydration.
- The expansion of e-commerce platforms will enhance market accessibility, offering consumers a wider range of products and the convenience of online shopping.
- Key market players will engage in strategic collaborations and partnerships to expand their product offerings, improve distribution channels, and enhance brand visibility.
- Increased educational campaigns by environmental organizations and influencers will raise awareness about the benefits of reusable water bottles, promoting widespread adoption.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the North America Reusable Water Bottles Market?
What are the key drivers of the market's growth?
Which materials are popular in the reusable water bottles market?
How are companies promoting the adoption of reusable water bottles?
Which distribution channels are most effective for reusable water bottles?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 1,972.04 million → 2032: USD 3,108.88 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 North America Reusable Water Bottles Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 North America Reusable Water Bottles Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 North America Reusable Water Bottles Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 North America Reusable Water Bottles Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 North America Reusable Water Bottles Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 North America Reusable Water Bottles Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 North America Reusable Water Bottles Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 North America Reusable Water Bottles Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 1,972.04 million → 2032: USD 3,108.88 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 North America Reusable Water Bottles Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 North America Reusable Water Bottles Geographic Market Outlook, 2023-2032
- 13.1 Regional Market Size and Country-Level Shares, 2023
- 13.2 Country Market Size Comparison, 2023
- 13.3 Country Market Forecasts, 2023-2032
- 13.4 Subregional Industrial and Demand Clusters
- 13.5 Intra-Regional Pricing and Cost Differences
- 13.6 Cross-Border Trade and Supply Networks
- 13.7 Regional Supply and Demand Balances
- 13.8 Country Opportunity Comparison and Prioritization
Note: Every listed country is covered on the structure shown under the first country.
Chapter 14 North America Reusable Water Bottles Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2023-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 North America Reusable Water Bottles Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2023
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2023-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.
