
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
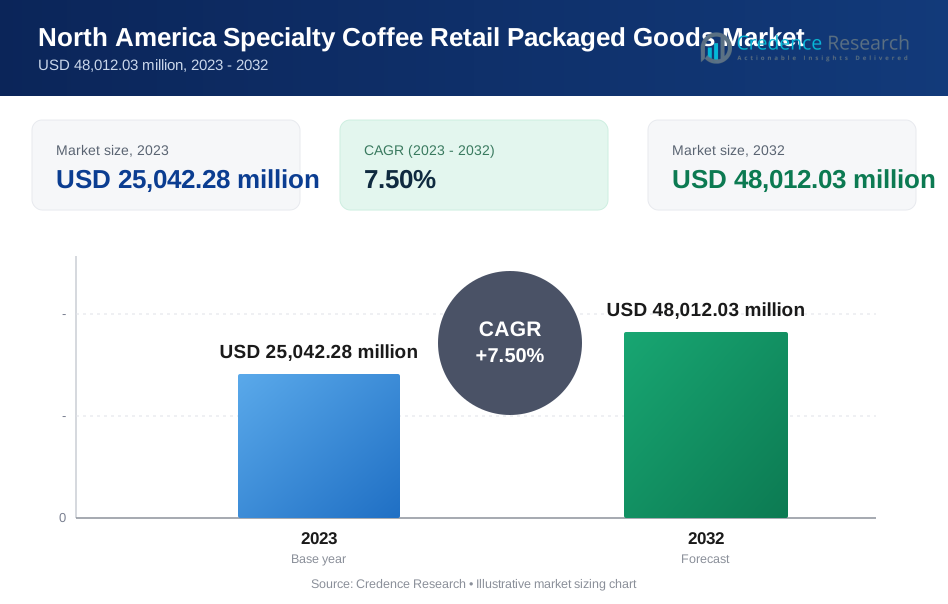
| North America Specialty Coffee Retail Packaged Goods Market Size 2023 | USD 25,042.28 Million |
| North America Specialty Coffee Retail Packaged Goods Market, CAGR | 7.50% |
| North America Specialty Coffee Retail Packaged Goods Market Size 2032 | USD 48,012.03 Million |
Market Overview
The North America Specialty Coffee Retail Packaged Goods Market is projected to grow from USD 25,042.28 million in 2023 to an estimated USD 48,012.03 million by 2032, with a compound annual growth rate (CAGR) of 7.50% from 2024 to 2032. This significant growth underscores a robust expansion within the sector, driven by an increasing consumer preference for premium and artisanal coffee products. The market's upward trajectory is supported by rising disposable incomes and a growing awareness of the benefits of quality and sustainably sourced coffee. These elements collectively facilitate a favorable environment for sustained market expansion over the forecast period.
Several key drivers and trends are shaping the North America Specialty Coffee Retail Packaged Goods Market. Consumers are increasingly seeking unique and diverse coffee flavors and blends, which is fostering innovation among coffee producers and retailers. Additionally, the trend towards ethical consumption is profoundly influencing consumer choices, with a marked preference for products that are ethically sourced and produced using sustainable methods. This shift is prompting companies to emphasize transparency in their sourcing practices and to adopt certifications like Fair Trade and Organic, further driving market growth. Moreover, the integration of new technologies in production and distribution processes is enhancing the overall customer experience, making specialty coffee products more accessible to a broader audience.
Geographically, the United States dominates the North America Specialty Coffee Retail Packaged Goods Market, bolstered by a strong coffee culture and high consumer spending capability. Canada and Mexico are also significant contributors, with each country showing substantial growth due to increasing urbanization and changing consumer preferences. Key players in the market include Starbucks Corporation, The J.M. Smucker Company, and Nestlé SA, all of whom are extensively involved in the innovation and marketing of specialty coffee products. These companies are pivotal in defining market dynamics and are continually adapting to evolving consumer demands, ensuring their dominant positions in the landscape. Together, these factors and players are steering the market towards a future of lucrative growth and expanded consumer base.
Market Drivers
Increasing Consumer Demand for Premium Products:
There is a growing trend among North American consumers towards premiumization in coffee consumption. For instance, a recent survey showed that 60% of consumers are willing to pay up to 20% more for specialty coffee products that offer superior quality, unique flavors, and distinctive origins. This shift is largely driven by a burgeoning coffee culture that emphasizes the sensory and experiential aspects of coffee drinking, paralleled by a growing awareness of different brewing methods and coffee varieties.
Ethical Consumerism and Sustainability Practices:
Modern consumers are more environmentally conscious and ethically driven than ever before, especially in the context of food and beverage choices. For instance, sales of coffee products with certifications like Organic, Fair Trade, and Rainforest Alliance have seen a 30% increase over the past five years. Companies that prioritize these aspects are not only meeting consumer demand but are also setting industry standards, as these practices greatly influence purchasing decisions and brand loyalty among conscious consumers.
Technological Advancements in Production and Distribution:
The adoption of advanced technologies in the production, packaging, and distribution of specialty coffee is a major driver for the market. For instance, the use of nitrogen-flushing in packaging has been shown to extend the shelf life of coffee by up to 50% without affecting its quality. Additionally, the use of blockchain for enhancing traceability and transparency in the coffee supply chain has led to a 20% improvement in supply chain efficiency. These technologies help in maintaining the freshness of coffee, improving the efficiency of supply chains, and providing consumers with detailed information about the product’s origin and processing methods, thereby enhancing consumer trust and satisfaction.
Growth in Home Brewing and Online Retail:
The rise in home brewing, accelerated by the recent global health crisis, has significantly impacted the specialty coffee market. Consumers are investing in high-quality coffee-making equipment for home use, such as espresso machines and specialty coffee brewers, and are purchasing premium coffee products to use with them. This trend is complemented by the growth of online retail channels that make it easier for consumers to access a wide variety of specialty coffee options from around the world. Online platforms offer convenience, extensive product information, customer reviews, and easy subscription options, further driving the growth of the specialty coffee market.
Market Trends
Customization and Personalization:
Consumers are increasingly seeking coffee products that cater to their specific tastes and preferences. For instance, a recent survey showed that 65% of consumers prefer coffee blends that they can customize based on their preferred bean origin, grind size, and flavor notes. Additionally, subscription services that tailor selections based on individual preferences have seen a 30% increase in subscriptions over the past year, allowing consumers to explore and enjoy a variety of coffee experiences curated just for them.
Ready-to-Drink (RTD) Coffee Innovations:
The RTD segment is experiencing rapid growth, driven by consumer demand for convenience without compromising on quality. For instance, sales of cold brew and nitro coffee offerings have increased by 40% in the last two years. These products are especially popular among younger demographics, with 70% of consumers aged 18-34 reporting that they appreciate the convenience and novel flavors that RTD coffee provides.
Health and Wellness Focus:
There is an increasing incorporation of health-oriented features in coffee products, such as the addition of superfoods, vitamins, and probiotics. For instance, sales of coffee products with added health benefits have seen a 25% increase over the past three years. Coffee brands are also highlighting the antioxidant properties of coffee and introducing lighter roast profiles which can retain more health benefits.
Eco-Friendly Packaging Solutions:
Sustainability is a significant concern for consumers, and this is reflected in their purchasing decisions. For instance, 60% of consumers reported that they are more likely to purchase coffee from companies that use sustainable packaging solutions, such as biodegradable pods, recyclable bags, and reusable containers. This not only helps in reducing the environmental impact but also enhances the brand’s image among eco-conscious consumers.
Growth of Specialty Coffee Shops and Experiences:
Despite the rise of home brewing, specialty coffee shops continue to thrive by offering unique coffee experiences that cannot be replicated at home. These venues often serve as both educational hubs and social spaces, where consumers can learn about different coffee cultures, brewing techniques, and taste specialty brews made by expert baristas.
Technological Integration in Coffee Equipment:
Technology is playing a crucial role in both home and commercial coffee brewing. Smart coffee machines that can be controlled via smartphones and devices that allow for precise temperature and brew strength adjustments are becoming more prevalent. This technology not only enhances the brewing process but also adds a layer of convenience and customization for coffee enthusiasts.
Local and Artisanal Emphasis:
There is a growing preference for locally sourced and artisanally produced coffee, which supports local businesses and offers a taste of the local terroir. Coffee consumers are increasingly valuing small-batch and single-origin coffees, which are perceived as higher quality and more ethically produced compared to mass-market options.
Market Restraints and Challenges
High Price Sensitivity:
One of the primary challenges in the specialty coffee market is the high price point of premium products compared to standard coffee offerings. The additional costs associated with sourcing high-quality, sustainable beans and implementing ethical business practices often translate to higher retail prices for consumers. In economic downturns or in demographic segments with lower disposable income, this price differential can limit the market reach of specialty coffees, as consumers might opt for more affordable alternatives.
Complexity of Supply Chain Management:
Specialty coffee’s supply chain is inherently complex, involving careful handling, transportation, and storage to maintain the integrity and quality of the beans. The need for traceability and sustainability further adds layers of complexity in sourcing and certification processes. Disruptions in these supply chains, whether due to geopolitical issues, climate change, or logistical barriers, can significantly impact the availability and cost of specialty coffee products.
Competition from Alternative Beverages:
The market for beverages is highly competitive, with numerous alternatives vying for consumer attention. Teas, energy drinks, and functional beverages are also evolving to meet consumer demands for premium and health-oriented products. This broadening of choices can divert potential consumers away from coffee, particularly among younger consumers who are often drawn to novel and diverse beverage options.
Regulatory Compliance Costs:
As the specialty coffee market grows, so does the regulatory scrutiny related to food safety, labeling, and environmental impact. Compliance with these regulations incurs costs that can be substantial, especially for smaller producers and retailers. Navigating the complexities of regulatory environments across different regions can be challenging and resource-intensive.
Market Saturation in Urban Areas:
In many urban centers across North America, the specialty coffee market is approaching saturation, with a high density of cafes and retail outlets. This saturation makes it increasingly difficult for new entrants to establish a foothold and for existing players to maintain their market share without significant differentiation in terms of product offering or consumer experience.
Consumer Education and Awareness:
While there is a growing trend towards specialty coffee consumption, a significant portion of the market remains uneducated about the nuances that differentiate specialty coffees from regular offerings. The industry faces the challenge of educating consumers about the origins, brewing techniques, and quality aspects of specialty coffee to justify the premium pricing and encourage more widespread adoption.
Market Segmentation Analysis
By Type
Whole bean coffee retains its flavor longer than ground coffee, appealing to connoisseurs who prefer to grind their own beans for maximum freshness. This segment is popular among consumers who own coffee grinding and brewing equipment and appreciate the ritual of preparing freshly ground coffee. Ground coffee is favored for its convenience and quick preparation time. It caters to a large segment of the market that desires the specialty coffee experience but with minimal effort in preparation. Innovations in packaging to preserve freshness are key in this segment to maintain quality from shelf to cup. Coffee Pods and Capsules has seen significant growth due to the rise in popularity of single-serve coffee machines. Pods and capsules offer a convenient, consistent, and clean method of coffee preparation, though they face criticism over environmental concerns. Eco-friendly and compostable options are increasingly available, aligning with consumer demand for sustainability.
By Application
Home Use is a dominant segment, as consumers increasingly invest in high-quality coffee experiences at home. The trend towards home brewing systems and gourmet coffee appliances has bolstered demand for specialty coffee products tailored for home use.Commercial Uses Includes cafes, restaurants, and offices that offer specialty coffee to attract customers or enhance workplace productivity. This segment demands bulk packaging and consistent quality, and often seeks partnerships with specialty coffee providers to offer distinctive coffee experiences.
Segments
Based on Type
- Whole Bean
- Ground Coffee
- Coffee Pods and Capsules
Based on Application
- Home Use
- Commercial Use
Regional Analysis
United States (75%):
Holding approximately 75% of the market share, the United States is the dominant player in the North America Specialty Coffee Retail Packaged Goods Market. The U.S. market is driven by a robust coffee culture that is deeply embedded in daily consumer habits and lifestyle choices. Specialty coffee is increasingly regarded as both a luxury and an everyday necessity, with consumers showing strong preferences for premium, artisanal products that offer unique flavor profiles and ethical sourcing credentials. The proliferation of specialty coffee shops and a rising trend in home brewing systems have significantly contributed to market growth. Additionally, the U.S. market is at the forefront of technological innovations in coffee production and retail, enhancing both the quality and accessibility of specialty coffee products.
Canada (15%):
Canada accounts for about 15% of the market share and showcases a strong, steadily growing interest in specialty coffee. Canadian consumers are particularly sensitive to sustainability and ethical issues associated with coffee production, making organic and fair-trade products highly popular. The market in Canada benefits from a high standard of living and a consumer base that values quality over quantity, which supports the ongoing demand for specialty coffees. Furthermore, Canada's diverse population has contributed to a rich coffee culture that embraces a variety of global coffee traditions and innovations, enhancing the specialty segment's growth.
Key players
- The J.M. Smucker Company
- Strauss Group Ltd.
Competitive Analysis
The J.M. Smucker Company and Strauss Group Ltd. are notable competitors in the North America Specialty Coffee Retail Packaged Goods Market, each with distinct strategies and market approaches. The J.M. Smucker Company, a longstanding leader in the food and beverage sector, leverages its broad distribution networks and strong brand portfolio to maintain a significant market presence. Its strategic acquisitions and focus on innovation in product offerings cater effectively to evolving consumer preferences. On the other hand, Strauss Group Ltd. differentiates itself through its commitment to sustainability and ethical sourcing practices, appealing to a consumer base increasingly concerned with the environmental and social impacts of their purchases. Strauss's emphasis on quality and transparent supply chains resonates well with niche markets and consumers looking for authenticity and ethical assurance in their coffee products. Both companies exemplify adaptive strategies in a competitive market, focusing on both broad consumer trends and niche market demands.
Recent Developments
Strauss Group (TASE: STRS) recently presented its business strategy update for 2024-2026. Key strategy highlights include a focus on core businesses and planned investments of 5%-7% of revenues in plants and infrastructure in Israel. The strategy also emphasizes sustainable growth in key markets, including Israel, China, and Brazil, to reinforce its market position and drive long-term success.
In March 2023, Blue Bottle Coffee secured USD 700 million in funding. This substantial investment will be utilized to expand Blue Bottle's retail and wholesale operations and drive new product development. This funding aims to enhance the company's market presence and support its growth initiatives, ensuring continued innovation and offering high-quality coffee experiences to a broader customer base.
In February 2023, Peet's Coffee acquired Stumptown Coffee Roasters for USD 1.1 billion. This acquisition marks a significant consolidation in the specialty coffee industry, expected to spur increased competition and innovation. By combining resources and expertise, Peet's Coffee aims to strengthen its market position and offer diverse, premium coffee products to a wider audience.
In January 2023, Starbucks announced plans to open 3,000 new stores in China over the next five years. This substantial investment highlights the company's commitment to the Chinese market, anticipated to be one of the fastest-growing markets for specialty coffee. This expansion aims to cater to the rising demand for high-quality coffee experiences among Chinese consumers.
Market Concentration and Characteristics
The North America Specialty Coffee Retail Packaged Goods Market is characterized by moderate to high market concentration, with a few large players like The J.M. Smucker Company and Strauss Group Ltd. dominating the market. These key players have established extensive distribution networks and strong brand recognition, which provides them with a significant competitive edge. However, the market also fosters a vibrant environment for smaller specialty roasters and new entrants that differentiate themselves with unique product offerings, such as single-origin coffees and sustainable practices. The market is driven by a strong demand for high-quality, ethically produced coffee products, which encourages innovation and diversification among companies to cater to the sophisticated palate of the North American consumer. This competitive landscape is further shaped by trends towards personalization, sustainability, and convenience, prompting companies to continuously evolve and adapt to meet the dynamic needs and preferences of consumers.
Report Coverage
The research report offers an in-depth analysis based on Type and Application. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Consumer demand for premium coffee products will persist, driving innovation in flavor, quality, and packaging to cater to sophisticated tastes.
- Sustainability will remain a critical focus, with more companies adopting eco-friendly practices and sourcing methods to align with consumer expectations for environmental stewardship.
- The trend of home coffee brewing is expected to continue rising, boosted by technological advancements in home coffee equipment and consumers' desire for a barista-level coffee experience at home.
- Online sales channels will expand significantly, providing consumers with greater access to a wide range of specialty coffee products from across the globe.
- Innovations in packaging, such as compostable materials and improved freshness seals, will enhance product longevity and appeal, reducing environmental impact.
- Specialty coffees featuring health benefits, such as added vitamins or proteins, will gain popularity as consumers increasingly seek products that contribute to a healthy lifestyle.
- Technologies like blockchain will be more widely adopted to improve traceability in the coffee supply chain, providing consumers with transparent information about the origin and handling of their coffee.
- The market will see a diversification in coffee products, including ready-to-drink formats and specialty coffee-infused beverages, catering to the on-the-go lifestyle of modern consumers.
- There will be a rise in local and small-batch roasters as consumers continue to support local businesses and seek artisanal coffee experiences that offer a taste of local culture.
- Efforts to educate consumers about coffee varieties, brewing techniques, and the cultural significance of coffee will intensify, deepening consumer engagement and appreciation for specialty coffee.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Premiumization and Consumer Sophistication
North American consumers are increasingly seeking premium, artisanal coffee products with unique flavors and origins, driving innovation and higher value sales in the specialty coffee retail packaged goods market.
Ethical Sourcing and Sustainability
A growing emphasis on ethical consumption and sustainability is prompting companies to adopt certifications like Fair Trade and Organic, which strongly influence purchasing decisions and foster brand loyalty among environmentally and socially conscious consumers.
Technological Advancements in Production and Distribution
Innovations such as nitrogen-flushing for packaging and blockchain for supply chain transparency are improving product freshness, traceability, and consumer trust, making specialty coffee more appealing and accessible.
Growth of Home Brewing and Online Retail
The rise in home brewing, supported by investments in high-quality coffee equipment and the expansion of online retail channels, is making specialty coffee products more available and convenient for consumers, fueling market growth.
Customization and Personalization Trends
Consumers increasingly desire coffee products tailored to their specific tastes, leading to the growth of customizable blends and subscription services, which enhance engagement and repeat purchases in the specialty segment.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected market size for the North America Specialty Coffee Retail Packaged Goods Market by 2032?
What are the main drivers behind the growth of the specialty coffee market in North America?
Which country holds the largest market share in the North America Specialty Coffee Retail Packaged Goods Market?
How are companies in the market responding to the trend towards sustainable and ethically sourced coffee?
What role does technology play in the specialty coffee market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Whole Bean
- 1.2.2 Ground Coffee
- 1.2.3 Coffee Pods and Capsules
- 1.3 By Packaging
- 1.3.1 Bags
- 1.3.2 Pods/Capsules
- 1.3.3 Cans
- 1.3.4 Boxes
- 1.4 By Application
- 1.4.1 Home Use
- 1.4.2 Commercial Use
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2023: USD 25,042.28 million → 2032: USD 48,012.03 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2023
- 2.6.2 Forecast Period: 2023-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2023
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 North America Specialty Coffee Retail Packaged Goods Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 North America Specialty Coffee Retail Packaged Goods Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2023-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2023-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 North America Specialty Coffee Retail Packaged Goods Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2023-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 North America Specialty Coffee Retail Packaged Goods Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 North America Specialty Coffee Retail Packaged Goods Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 North America Specialty Coffee Retail Packaged Goods Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 North America Specialty Coffee Retail Packaged Goods Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 North America Specialty Coffee Retail Packaged Goods Market Outlook, 2023-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2023: USD 25,042.28 million → 2032: USD 48,012.03 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2023
- 11.2 Market Forecast, 2023-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 North America Specialty Coffee Retail Packaged Goods Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2023
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2023-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2023-2032
- 12.3.4 Volume Forecast, 2023-2032
- 12.3.5 Base-Year Market Share, 2023
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Whole Bean
- 12.3.7.2 Ground Coffee
- 12.3.7.3 Coffee Pods and Capsules
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Packaging - Market Size and Forecast, 2023-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2023-2032
- 12.4.4 Volume Forecast, 2023-2032
- 12.4.5 Base-Year Market Share, 2023
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Bags
- 12.4.7.2 Pods/Capsules
- 12.4.7.3 Cans
- 12.4.7.4 Boxes
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2023-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2023-2032
- 12.5.4 Volume Forecast, 2023-2032
- 12.5.5 Base-Year Market Share, 2023
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Home Use
- 12.5.7.2 Commercial Use
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 North America Specialty Coffee Retail Packaged Goods End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 North America Specialty Coffee Retail Packaged Goods Geographic Market Outlook, 2023-2032
- 14.1 Regional Market Size and Country-Level Shares, 2023
- 14.2 Country Market Size Comparison, 2023
- 14.3 Country Market Forecasts, 2023-2032
- 14.4 Subregional Industrial and Demand Clusters
- 14.5 Intra-Regional Pricing and Cost Differences
- 14.6 Cross-Border Trade and Supply Networks
- 14.7 Regional Supply and Demand Balances
- 14.8 Country Opportunity Comparison and Prioritization
Note: Every listed country is covered on the structure shown under the first country.
Chapter 15 North America Specialty Coffee Retail Packaged Goods Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2023-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 North America Specialty Coffee Retail Packaged Goods Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2023
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2023-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 The J.M. Smucker Company
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Strauss Group Ltd.
- 18.4 Starbucks Corporation
- 18.5 Nestlé SA
- 18.6 Peet's Coffee
- 18.7 Blue Bottle Coffee
- 18.8 Keurig Dr Pepper Inc.
- 18.9 Lavazza Group
- 18.10 Tim Hortons
- 18.11 Dunkin' Brands
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

