
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
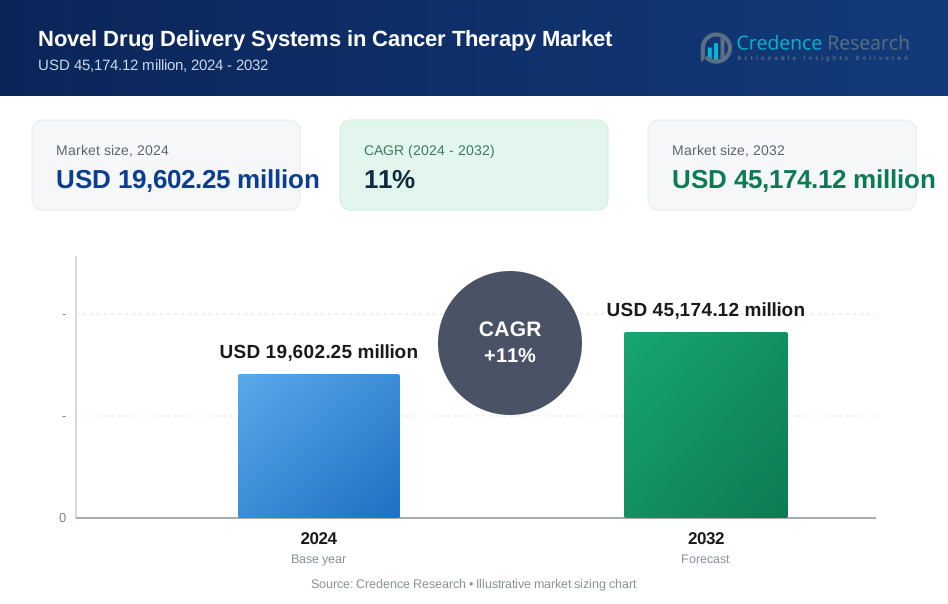
| Novel Drug Delivery Systems in Cancer Therapy Market Size 2024 | USD 19,602.25 Million |
| Novel Drug Delivery Systems in Cancer Therapy Market, CAGR | 11% |
| Novel Drug Delivery Systems in Cancer Therapy Market Size 2032 | USD 45,174.12 Million |
Market Overview
The global market for novel drug delivery systems in cancer therapy is projected to grow from USD 19,602.25 million in 2024 to USD 45,174.12 million by 2032, with a compound annual growth rate (CAGR) of 11%.
The novel drug delivery systems (NDDS) in cancer therapy are driven by the growing need for targeted treatments that improve drug efficacy and minimize side effects. Advances in nanotechnology, biotechnology, and biomaterials are enhancing the precision of drug delivery, boosting market growth. Additionally, the rise in cancer incidence and demand for personalized medicine is propelling the adoption of NDDS. Key trends include the development of nanocarriers, liposomes, and microspheres to optimize drug release, along with increasing investments in research and collaboration between pharmaceutical companies and academic institutions to innovate and improve therapeutic outcomes.
The geographical analysis of novel drug delivery systems (NDDS) in cancer therapy highlights significant growth across regions, driven by advancements in healthcare infrastructure and increasing cancer prevalence. North America leads in innovation due to robust research and development activities and regulatory support, while the Asia Pacific is emerging as a key growth region owing to a large patient pool and rising healthcare investments. Key players driving the market include Johnson & Johnson Services, Inc., Teva Pharmaceutical Industries Ltd, Bristol-Myers Squibb Company (Celgene Corporation), Shire (Takeda Pharmaceutical Company Limited), Galen Limited, Merrimack Pharmaceuticals, Samyang Holdings Corporation, and Spectrum Pharmaceuticals, Inc.
Market Drivers
Increasing Cancer Prevalence
The rising incidence of various cancer types worldwide is a major factor driving the demand for effective and targeted therapies. As cancer rates continue to climb, there is a growing need for treatment options that minimize side effects while maximizing efficacy. For instance, the World Health Organization (WHO) reports that cancer is a leading cause of death worldwide, with nearly 10 million deaths in 2020. Novel drug delivery systems (NDDS) offer a promising solution by delivering therapeutic agents directly to cancer cells, thereby reducing the impact on healthy tissue and enhancing the precision of treatment. This shift toward targeted therapies is fueling market growth.
Limitations of Conventional Therapies
Traditional chemotherapy and other conventional cancer treatments often involve severe side effects due to the non-selective action of drugs on both healthy and cancerous cells. These treatments can significantly compromise patient quality of life. NDDS address these limitations by ensuring drugs are delivered more precisely to tumor sites, improving therapeutic outcomes while reducing systemic toxicity. For instance, a review in the Journal of Population Therapeutics and Clinical Pharmacology highlights that NDDS can significantly reduce adverse effects by targeting drugs directly to cancer cells. As a result, patients experience fewer adverse effects, which is a critical factor in the increasing adoption of NDDS.
Personalized Medicine
The shift toward personalized medicine is driving the development of targeted NDDS. Tailoring cancer treatments to an individual’s genetic profile allows for more effective therapies with fewer side effects. For instance, the American Cancer Society explains that personalized medicine involves using genetic, immunological, and proteomic profiling to provide tailored therapeutic options. NDDS can be designed to deliver drugs specifically to cancer cells that express unique molecular markers, optimizing treatment outcomes. This trend towards personalized, precision therapies is pushing the demand for advanced drug delivery systems that meet the specific needs of patients.
Technological Advancements
Ongoing advancements in nanotechnology, biotechnology, and materials science are catalyzing the development of innovative drug delivery systems. Research in these fields is leading to the creation of novel carriers, such as liposomes, nanocarriers, and microspheres, which improve the efficiency and precision of drug delivery. These technologies enable the design of NDDS with enhanced ability to target tumors, thereby reducing toxicity and improving the therapeutic index, making cancer treatments more effective and safe.
Market Trends
Advancements in Targeted Therapy and Nanotechnology
The development of targeted therapies and precision medicine is transforming the landscape of cancer treatment. Novel drug delivery systems (NDDS) are increasingly being designed to target specific cancer cells, thereby minimizing side effects and maximizing treatment efficacy. Personalized treatment approaches, where therapies are tailored to an individual's genetic profile, are on the rise. Additionally, combining NDDS with other therapies such as immunotherapy is emerging as a promising strategy to enhance overall treatment outcomes. Nanotechnology plays a critical role in these innovations, with nanoparticles enabling direct delivery of drugs to tumor cells, significantly improving bioavailability and reducing systemic toxicity. For instance, a review in Nano Convergence discusses how nanomaterials provide versatility and functionality in engineering targeted cancer medicine, enhancing early detection and treatment efficacy. Liposomes, lipid-based vesicles that protect drugs from degradation, further enhance drug delivery by improving stability and targeting precision, which contributes to reduced side effects and enhanced therapeutic effects.
Biodegradable Materials, Drug-Conjugate Systems, and Implantable Solutions
Biodegradable and biocompatible materials are essential for the next generation of drug delivery systems. Polymer-based systems, designed to degrade slowly over time, allow for sustained drug release, reducing the frequency of administration and improving patient compliance. Natural polymers, such as chitosan and hyaluronic acid, are gaining popularity due to their biocompatibility and low toxicity, making them ideal candidates for safe, effective drug delivery. Drug-conjugate systems, such as antibody-drug conjugates (ADCs) and peptide-drug conjugates (PDCs), combine targeted molecules with cytotoxic drugs to precisely target cancer cells while minimizing damage to healthy tissue. These systems are particularly effective in targeting tumors with high specificity. Furthermore, implantable drug delivery systems, including polymer-based implants and microneedle patches, offer innovative solutions for controlled drug release over extended periods. Polymer implants deliver drugs steadily, reducing the need for frequent injections, while microneedle patches allow for painless, direct drug delivery through the skin, bypassing systemic circulation and enhancing delivery efficiency. This technological evolution is further supported by a favorable regulatory landscape, with accelerated approvals and international collaborations driving the commercialization and development of NDDS on a global scale.
Market Challenges Analysis
Technical and Manufacturing Challenges
One of the primary challenges in the development of novel drug delivery systems (NDDS) is formulation complexity. Designing stable and efficient formulations requires precise control over various factors such as particle size, surface charge, and drug loading capacity. For instance, a review in the Asian Journal of Pharmaceutical Research and Development highlights that achieving optimal particle size and surface charge is critical for the stability and efficacy of NDDS. Achieving targeted drug delivery is another significant hurdle; while NDDS hold the potential for precision in targeting cancer cells, ensuring that drugs reach only the tumor sites while minimizing off-target effects remains a challenge. Additionally, biocompatibility and toxicity are crucial considerations, as the safety and effectiveness of NDDS depend on their ability to function without causing harm to healthy tissue. On the manufacturing front, scaling up production and maintaining cost-effectiveness are vital for bringing these innovative systems to market. The need for efficient, reproducible, and affordable manufacturing processes is essential for the widespread commercialization of NDDS.
Regulatory, Economic, and Patient-Related Challenges
NDDS face numerous regulatory hurdles, as the approval process for novel therapies is often stringent, time-consuming, and expensive. Regulatory agencies require comprehensive data to demonstrate the safety and efficacy of these systems, particularly for complex formulations, making clinical trial design a challenging and resource-intensive task. For instance, the Central Drugs Standard Control Organization (CDSCO) outlines the extensive data requirements and rigorous evaluation processes for new drug approvals in India. From an economic perspective, the development of NDDS involves substantial upfront costs, including research, clinical trials, and manufacturing, which can strain resources, especially for smaller companies. Protecting intellectual property rights also becomes complex in a rapidly evolving field, raising concerns over patenting and competition. Furthermore, securing market access and reimbursement in cost-sensitive healthcare systems remains difficult, potentially limiting the availability of NDDS to patients. Patient-related challenges, such as ensuring adherence to complex treatment regimens and educating patients about the benefits and risks of NDDS, are also significant. For these systems to achieve widespread adoption, patients must fully understand their potential and be motivated to follow prescribed treatments.
Market Segmentation Analysis:
By Product:
The novel drug delivery systems (NDDS) in cancer therapy are categorized into two primary segments: nanoparticles and embolization particles. Each product type offers unique benefits in enhancing the precision and effectiveness of cancer treatments. Nanoparticles are one of the most widely used drug delivery platforms in oncology. These tiny particles, typically ranging from 1 to 100 nanometers, can encapsulate chemotherapy drugs and target specific tumor cells with high precision. Their small size allows them to penetrate tumors more effectively, improving drug bioavailability and reducing systemic toxicity. Nanoparticles can be engineered with various surface modifications, such as targeting ligands or coatings, to enhance their ability to target specific cancer cells or tissues. This targeted approach helps minimize damage to healthy cells and reduces side effects, making nanoparticles an attractive option for personalized cancer therapy. Embolization particles are another important segment in cancer treatment. These particles are primarily used in interventional therapies like transarterial chemoembolization (TACE), where they are injected into the blood vessels supplying the tumor. The embolization particles block the blood supply to the tumor, depriving it of nutrients and oxygen while simultaneously delivering chemotherapy drugs. This method enhances the therapeutic efficacy by delivering concentrated doses directly to the tumor site, reducing the risk of systemic side effects. Embolization particles are particularly useful in treating liver cancer and other solid tumors, where localized treatment is critical for effectiveness.
Segments:
Based on Product:
- Nanoparticles
- Embolization Particles
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America holds the largest market share in the novel drug delivery systems (NDDS) in cancer therapy, accounting for approximately 40% of the global market. The region benefits from advanced healthcare infrastructure, high research and development investments, and the presence of leading pharmaceutical companies driving innovation in drug delivery technologies. The increasing prevalence of cancer, particularly in the United States, along with a growing focus on personalized medicine and precision oncology, further fuels market growth. The U.S. FDA’s expedited approval processes for innovative therapies and increasing funding for cancer research have enabled the rapid development and commercialization of novel drug delivery systems. Additionally, strong demand for targeted therapies that minimize side effects has resulted in increased adoption of NDDS among clinicians and patients. With ongoing advancements in nanotechnology and biotechnology, North America is poised to maintain its dominance in the NDDS market throughout the forecast period.
Asia Pacific
The Asia Pacific region accounting for approximately 20% of the global market, the region is rapidly emerging as a key player in the field. Factors such as a large and growing patient population, increasing cancer rates, and improving healthcare infrastructure are contributing to the surge in demand for advanced cancer therapies. Countries like China, India, and Japan are investing significantly in healthcare innovation, driving the adoption of novel drug delivery systems. Furthermore, the expanding number of clinical trials and collaborations between local biotech firms and international pharmaceutical companies are accelerating the development of targeted therapies and drug delivery platforms. The government’s focus on affordable healthcare solutions, along with increasing awareness about personalized medicine, will likely bolster market growth in this region in the coming years.
Key Player Analysis
- Johnson & Johnson Services, Inc.
- Teva Pharmaceutical Industries Ltd
- Bristol-Myers Squibb Company (Celgene Corporation)
- Shire (Takeda Pharmaceutical Company Limited)
- Samyang Holdings Corporation
- Galen Limited
- Merrimack Pharmaceuticals
- Spectrum Pharmaceuticals, Inc.
Competitive Analysis
The competitive landscape of novel drug delivery systems (NDDS) in cancer therapy is marked by innovation and strategic advancements by leading players such as Johnson & Johnson Services, Inc., Teva Pharmaceutical Industries Ltd, Bristol-Myers Squibb Company (Celgene Corporation), Shire (Takeda Pharmaceutical Company Limited), Galen Limited, Merrimack Pharmaceuticals, Samyang Holdings Corporation, and Spectrum Pharmaceuticals, Inc. These companies are investing significantly in research and development to enhance targeted delivery methods, leveraging technologies like nanoparticles, liposomes, and polymer-based systems. Collaborations, acquisitions, and partnerships are common strategies to expand their market presence and accelerate product development. Additionally, the focus on personalized medicine and improved patient outcomes drives innovation in drug formulations and delivery platforms. The competitive intensity is further heightened by the need to address regulatory challenges and achieve cost-effective manufacturing solutions, positioning these players as key contributors to the growth and evolution of NDDS in cancer therapy.
Recent Developments
- In May 2024, Teva Pharmaceutical Industries Ltd., along with Alvotech, introduced SIMLANDI Injection in the United States. This product launch bolstered the position of the firm in the country.
- In May 2024, Johnson & Johnson Services, Inc. acquired Shockwave Medical. The move helped the organization expand presence in the global landscape.
- In June 2024, Bristol-Myers Squibb Company received FDA accelerated approval for KRAZATI (adagrasib) in combination with cetuximab, a targeted treatment for KRASG12C-mutated CRC patients who had undergone prior chemotherapy, based on ORR and DOR results.
- In January 2024, Johnson & Johnson acquired Ambrx Biopharma, a clinical-stage biopharmaceutical company, in a cash merger deal valued at approximately USD 2.0 billion, with estimated cash on hand deducted.
Market Concentration & Characteristics
The market for novel drug delivery systems (NDDS) in cancer therapy is characterized by moderate to high concentration, with several established pharmaceutical companies and emerging biotech firms driving innovation. The presence of key players such as Johnson & Johnson Services, Inc., Teva Pharmaceutical Industries Ltd, and Bristol-Myers Squibb Company ensures consistent advancements in targeted therapies and drug delivery technologies. These firms leverage extensive R&D capabilities and strategic collaborations to maintain a competitive edge. The market also displays dynamic characteristics, with a growing focus on personalized medicine, nanotechnology-based delivery platforms, and biocompatible materials. Regulatory support and increasing healthcare investments further encourage innovation in this space. However, the market faces challenges like high development costs and stringent regulatory requirements, which can limit the entry of smaller firms. Overall, the NDDS market exhibits robust growth potential, driven by the continuous demand for more effective and patient-friendly cancer treatment solutions.
Report Coverage
The research report offers an in-depth analysis based on Product and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The adoption of personalized medicine will drive innovation in targeted drug delivery systems for cancer therapy.
- Advancements in nanotechnology will enhance the precision and effectiveness of novel drug delivery systems.
- Increased focus on biocompatible and biodegradable materials will improve patient safety and treatment outcomes.
- Growing investments in research and development will accelerate the introduction of innovative drug delivery platforms.
- Collaboration between pharmaceutical companies and academic institutions will lead to groundbreaking therapies.
- Regulatory agencies will continue to streamline approval processes for novel and efficient cancer therapies.
- Expanding healthcare infrastructure in developing regions will create new opportunities for market growth.
- Integration of AI and data analytics will optimize the design and testing of drug delivery systems.
- Rising awareness among patients and healthcare providers will boost the adoption of advanced therapies.
- The combination of drug delivery systems with immunotherapy will redefine cancer treatment approaches.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Increasing Cancer Prevalence
The global rise in cancer incidence is creating a greater need for effective and targeted therapies, driving demand for novel drug delivery systems that can improve treatment outcomes and reduce side effects.
Limitations of Conventional Therapies
Traditional chemotherapy and radiation often cause significant side effects due to non-selective action; NDDS offer targeted delivery, minimizing toxicity and improving patient quality of life, thus accelerating market adoption.
Advancements in Nanotechnology and Biotechnology
Innovations in nanocarriers, liposomes, and biomaterials are enabling more precise and efficient drug delivery, enhancing the therapeutic index and fueling the development and commercialization of advanced NDDS.
Shift Toward Personalized Medicine
The trend toward tailoring cancer therapies to individual genetic profiles is increasing demand for NDDS that can deliver drugs specifically to tumors with unique molecular markers, optimizing efficacy and minimizing adverse effects.
Growing Investments and Collaborations
Rising R&D investments and partnerships between pharmaceutical companies and academic institutions are accelerating the development of innovative drug delivery platforms, expanding the market's technological capabilities and reach.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Novel Drug Delivery Systems in Cancer Therapy market?
What factors are driving the growth of the Novel Drug Delivery Systems in Cancer Therapy market?
What are the key segments within the Novel Drug Delivery Systems in Cancer Therapy market?
What are some challenges faced by the Novel Drug Delivery Systems in Cancer Therapy market?
Who are the major players in the Novel Drug Delivery Systems in Cancer Therapy market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product
- 1.2.1 Nanoparticles
- 1.2.2 Embolization Particles
- 1.3 By Technology
- 1.3.1 Liposomes
- 1.3.2 Polymer-based Systems
- 1.3.3 Microspheres
- 1.3.4 Drug-Conjugate Systems
- 1.3.5 Implantable Drug Delivery
- 1.4 By Application
- 1.4.1 Breast Cancer
- 1.4.2 Lung Cancer
- 1.4.3 Liver Cancer
- 1.4.4 Colorectal Cancer
- 1.4.5 Other Solid Tumors
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 19,602.25 million → 2032: USD 45,174.12 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Novel Drug Delivery Systems in Cancer Therapy Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Novel Drug Delivery Systems in Cancer Therapy Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Novel Drug Delivery Systems in Cancer Therapy Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Novel Drug Delivery Systems in Cancer Therapy Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Novel Drug Delivery Systems in Cancer Therapy Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Novel Drug Delivery Systems in Cancer Therapy Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Novel Drug Delivery Systems in Cancer Therapy Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Novel Drug Delivery Systems in Cancer Therapy Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 19,602.25 million → 2032: USD 45,174.12 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Novel Drug Delivery Systems in Cancer Therapy Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Nanoparticles
- 12.3.7.2 Embolization Particles
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Technology - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Liposomes
- 12.4.7.2 Polymer-based Systems
- 12.4.7.3 Microspheres
- 12.4.7.4 Drug-Conjugate Systems
- 12.4.7.5 Implantable Drug Delivery
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Application - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Breast Cancer
- 12.5.7.2 Lung Cancer
- 12.5.7.3 Liver Cancer
- 12.5.7.4 Colorectal Cancer
- 12.5.7.5 Other Solid Tumors
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Novel Drug Delivery Systems in Cancer Therapy End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Novel Drug Delivery Systems in Cancer Therapy Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Novel Drug Delivery Systems in Cancer Therapy Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Novel Drug Delivery Systems in Cancer Therapy Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Johnson & Johnson Services, Inc.
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Teva Pharmaceutical Industries Ltd
- 18.4 Bristol-Myers Squibb Company (Celgene Corporation)
- 18.5 Shire (Takeda Pharmaceutical Company Limited)
- 18.6 Galen Limited
- 18.7 Merrimack Pharmaceuticals
- 18.8 Samyang Holdings Corporation
- 18.9 Spectrum Pharmaceuticals, Inc.
- 18.10 Pfizer Inc.
- 18.11 AstraZeneca plc
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

