
Market Overview:
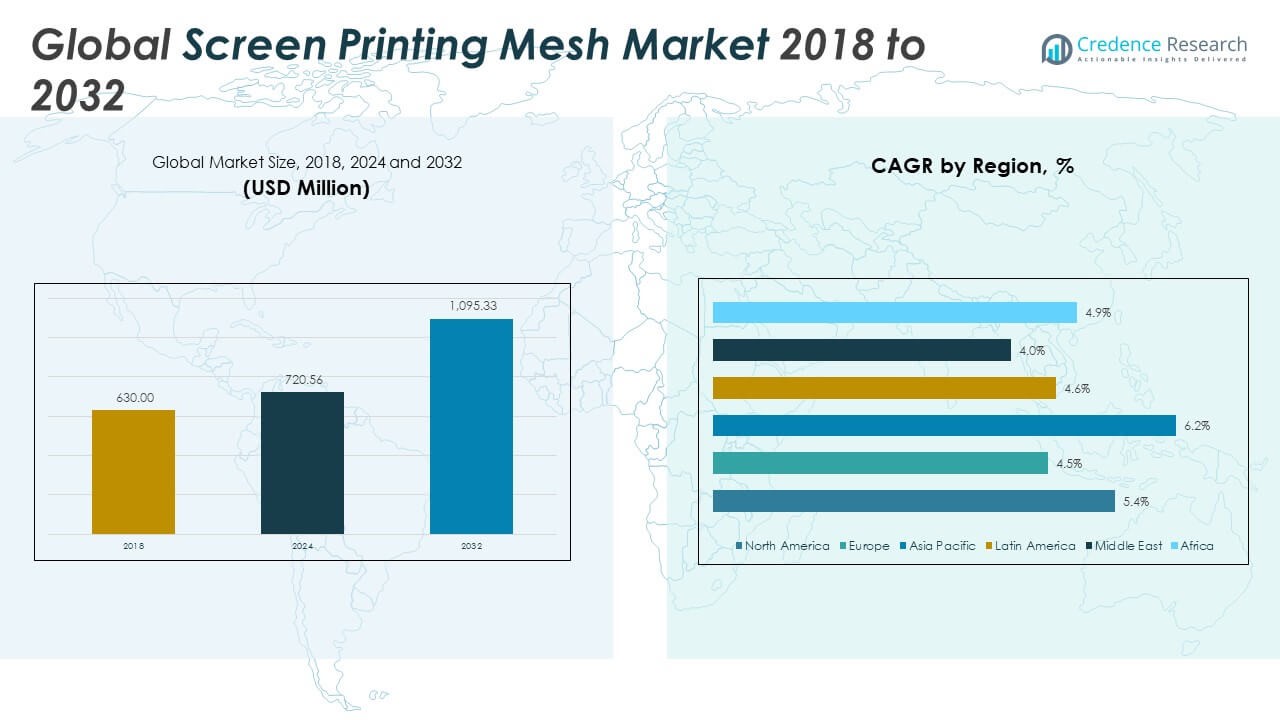
The Screen Printing Mesh Market size was valued at USD 630.00 million in 2018 to USD 720.56 million in 2024 and is anticipated to reach USD 1,095.33 million by 2032, at a CAGR of 5.44% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Screen Printing Mesh Market Size 2024 | USD 720.56 million |
| Screen Printing Mesh Market , CAGR | 5.44% |
| Screen Printing Mesh Market Size 2032 | USD 1,095.33 million |
The screen printing mesh market is experiencing sustained growth driven by increasing demand across textiles, electronics, and packaging industries. Manufacturers are shifting towards high-performance mesh materials like polyester and stainless steel to improve print quality, speed, and durability. Advancements in printing technology, coupled with rising demand for customized and high-resolution prints, are accelerating market adoption. Additionally, the growth of advertising and branding activities, especially in retail and promotional sectors, is further fueling the need for efficient and durable screen printing solutions worldwide.
Regionally, Asia Pacific dominates the screen printing mesh market due to its strong textile manufacturing base and rapid industrialization in countries like China, India, and Vietnam. North America and Europe maintain steady growth supported by technological advancements and the presence of established printing solution providers. Meanwhile, Latin America and the Middle East & Africa are emerging markets, benefiting from expanding manufacturing sectors and increasing investments in infrastructure and advertising. These regions are gradually adopting modern screen printing techniques to meet growing consumer and commercial demands.
Market Insights:
- The Screen Printing Mesh Market was valued at USD 630.00 million in 2018 and reached USD 720.56 million in 2024; it is projected to hit USD 1,095.33 million by 2032 at a CAGR of 5.44%.
- Increasing demand from the textile industry and growing adoption in electronics and packaging sectors are driving consistent market growth.
- Advancements in high-performance mesh materials like polyester and stainless steel improve durability and print quality.
- Fluctuating raw material prices and rising competition from digital printing technologies present key restraints to market expansion.
- Asia Pacific leads the global market due to its strong textile manufacturing base and rapid industrialization in China, India, and Vietnam.
- North America and Europe maintain stable demand, supported by high-end applications and a focus on sustainable printing technologies.
- Emerging economies in Latin America, the Middle East, and Africa show growing potential through expanding manufacturing and promotional industries.
Market Drivers:
Growing Demand from Textile and Apparel Printing Sector Drives Market Expansion
The textile and apparel industry is a significant growth engine for the Screen Printing Mesh Market. It relies heavily on screen printing for mass production of printed fabrics. Brands in fashion and sportswear continue to seek high-resolution, durable prints on various materials. This demand encourages textile manufacturers to invest in advanced mesh products to maintain quality and consistency. Polyester mesh remains a popular choice due to its versatility and cost-effectiveness. High mesh count variants are preferred for detailed and multicolor prints. Screen printing also supports large production runs at lower operational costs. This cost efficiency supports its continued use across small to mid-sized textile enterprises globally.
- For example, NBC Meshtec’s Alpha Seriesuses proprietary L-Screen technology, which improves thread strength by 16% and reduces elongation, enabling mesh counts from 10T to 165T (25–420 mesh/inch) for precise, multicolor designs-critical for brands demanding fine details on diverse fabrics.
Electronics Sector Demand Increases Usage of High-Precision Mesh Materials
The growing need for precision printing in electronics manufacturing supports the growth of the Screen Printing Mesh Market. Printed circuit boards (PCBs), membrane switches, and display panels require fine-line printing that screen printing mesh facilitates. It delivers controlled ink deposition, critical for applications with tight tolerances. Mesh materials such as stainless steel are preferred in electronics due to their dimensional stability. Consumer electronics companies invest in precision printing technologies to meet evolving performance standards. This increases the demand for fine mesh screens. It plays a key role in enhancing accuracy and reducing defects in high-end electronics production. The market benefits from these requirements for technical accuracy.
- For example, PFM Screen’s stainless steel meshoffers less than 1% elongation, essential for applications requiring line widths below 50µm and pattern tolerances under 3µm.
Rising Packaging and Labeling Applications Boost Product Usage
The packaging industry increasingly adopts screen printing mesh for product labeling and brand presentation. Screen printing provides vibrant colors and strong ink adhesion on diverse surfaces like plastic, glass, and metal. This makes it ideal for packaging applications that require durability and visual appeal. Beverage bottles, cosmetic containers, and industrial goods frequently use screen-printed labels. Companies aim to differentiate products through attractive packaging, which increases demand for premium mesh materials. Screen printing also works well for small batch runs and variable designs. It offers flexibility and cost control in niche packaging applications. The Screen Printing Mesh Market gains traction through its compatibility with evolving packaging needs.
Industrial and Promotional Printing Sectors Continue to Drive Market Growth
Industrial graphics and promotional printing represent expanding verticals for the Screen Printing Mesh Market. Advertising banners, signage, decals, and POP displays require durable and weather-resistant printing methods. Screen printing delivers these qualities while supporting various substrate types. Commercial printing houses prefer mesh screens for high-volume jobs due to their reliability and speed. The market benefits from rising demand for branded visuals in retail and public environments. Mesh suppliers continue to innovate in coatings and finishes to extend screen life and improve ink transfer. This supports higher print quality and reduced downtime. These operational advantages reinforce screen printing's relevance in industrial and commercial segments.
Market Trends
Technological Advancements in Mesh Coatings and Treatment Techniques
The Screen Printing Mesh Market experiences a shift driven by improvements in mesh coating technologies. Advanced emulsion treatments help optimize ink release and reduce blockages during printing. Surface-treated meshes deliver better image resolution and sharper edges. Suppliers develop anti-static and hydrophilic coatings to enhance print consistency and cleaning efficiency. These innovations increase screen durability and reduce downtime in high-speed operations. It allows manufacturers to meet tighter production deadlines. Performance enhancements also support sustainability by reducing waste and energy usage. Buyers in high-end applications actively seek these next-generation mesh variants for competitive advantage.
- For example, Haver & Boecker's high-precision metal meshes provide outstanding register accuracies by weaving ultra-fine wires with diameter tolerances under 10µm. This results in optimized ink flow, color gradients, and ink film thicknesses, which are essential for high-resolution electronics and solar cell applications demanding screen tensions exceeding 25N/cm and dimensional stability under thermal loads.
Shift Toward Customization and Short-Run Print Jobs Across Industries
Consumer preference for personalized products influences demand trends in the Screen Printing Mesh Market. Brands in fashion, home décor, and promotional products increasingly seek short-run, customized designs. Screen printing offers the flexibility to support these varied print needs at a controlled cost. It allows for quick changeovers between print jobs with minimal disruption. Mesh suppliers respond by offering screens optimized for frequent reuse and easy setup. This shift increases demand for mid-range mesh counts with balanced performance. It supports businesses aiming to offer creative and tailored solutions. The trend favors equipment upgrades that complement agile production models.
- For example, EXILE Technologies' Hornet D2M exemplifies recent innovation in supporting short-run, customized production. This direct-to-mesh (DTM) system uses a proprietary injectable emulsion technology, applying stencils directly to the screen adjacent to the press.
Sustainable Production Practices Influence Material Choices and Adoption
Sustainability emerges as a central trend affecting material selection in the Screen Printing Mesh Market. Companies evaluate mesh materials for recyclability, energy efficiency, and chemical resistance. Polyester meshes dominate due to their lower environmental impact compared to traditional materials. Reusable mesh frames and eco-friendly emulsions gain popularity among printing facilities. Print houses aim to minimize solvent use and waste during screen preparation and cleaning. Manufacturers adapt by producing long-life meshes that reduce the need for frequent replacements. These practices align with regulatory pressure and corporate sustainability goals. The trend influences procurement standards and long-term supplier strategies.
Automation and Integration with Digital Workflow Shape Market Dynamics
The rise of automation in printing workflows impacts screen preparation and mesh handling. Printing units increasingly integrate pre-press automation for screen tensioning and coating. Mesh products compatible with such systems gain traction in the Screen Printing Mesh Market. It improves production consistency and reduces operator dependency. Integration with digital prepress systems streamlines artwork alignment and screen imaging. This allows seamless switching between screen and digital print processes. Automated reclamation systems further enhance operational efficiency. Print shops value these developments for reducing labor costs and improving process control. These workflow shifts define the future competitiveness of screen printing solutions.
Market Challenges Analysis
Fluctuating Raw Material Costs and Supply Chain Disruptions Impact Profit Margins
The Screen Printing Mesh Market faces ongoing pressure from volatile raw material prices, especially polyester and stainless steel. These materials account for a significant share of overall manufacturing costs. Fluctuations in crude oil prices affect polyester supply chains, while global steel trade policies influence metal availability. Suppliers struggle to maintain stable pricing structures under such uncertainty. Lead time variability also affects production scheduling for mesh manufacturers. Disruptions during transportation or material shortages delay delivery commitments and strain customer relationships. The market finds it challenging to pass rising costs to end-users in competitive segments like textiles. This limits investment in innovation and expansion initiatives.
Growing Competition from Digital Printing Technologies Creates Market Uncertainty
Digital printing technology continues to evolve, offering faster setup, higher resolution, and greater design flexibility. It appeals to industries that value quick turnaround and minimal setup requirements. The Screen Printing Mesh Market feels competitive pressure in segments where digital can substitute for analog methods. Print service providers assess ROI between investing in mesh systems or digital presses. Smaller businesses opt for digital due to lower skill requirements and better suitability for personalized orders. It becomes difficult for traditional screen printing to compete on cost efficiency for low-volume jobs. This trend requires mesh manufacturers to reposition offerings and highlight unique value in durability and specialty applications.
Market Opportunities
Rising Adoption in Emerging Markets with Growing Printing Demand
The Screen Printing Mesh Market finds substantial opportunity in emerging markets experiencing rapid industrial growth. Countries in Southeast Asia, Africa, and Latin America expand their printing infrastructure to serve domestic and export needs. Textile production hubs and packaging manufacturers seek reliable screen printing solutions for mass production. It gains traction as a cost-effective technology suited for diverse substrates. Mesh suppliers enter these markets with localized distribution and training support. The demand for mid-range mesh products with consistent performance creates entry-level growth segments. These regions offer long-term potential as industrial activities diversify.
Expanding Scope in High-Precision Applications and Niche Industries
High-precision applications in medical devices, solar panels, and flexible electronics present new frontiers for the Screen Printing Mesh Market. These sectors demand controlled ink deposition and exacting print quality. It caters to these needs with stainless steel and hybrid mesh materials. Manufacturers partner with device makers to co-develop customized screens. Success in these segments requires technical expertise and quality assurance systems. The market captures value by supporting R&D and small-batch prototyping. These opportunities allow differentiation from digital competitors and support premium pricing strategies.
Market Segmentation Analysis:
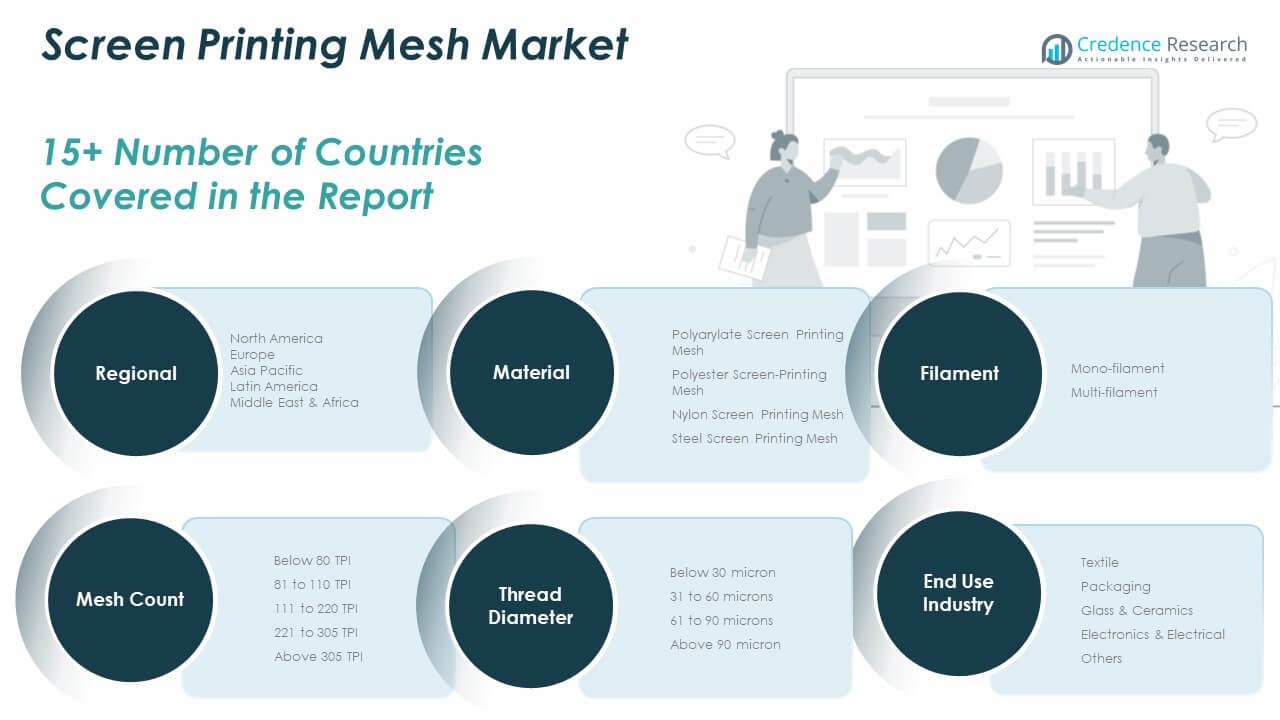
The Screen Printing Mesh Market is segmented by material, filament type, mesh count, thread diameter, and end-use industry, each playing a critical role in defining performance and application scope.
By material, polyester screen printing mesh holds the largest share due to its durability, affordability, and compatibility with a wide range of substrates. Polyarylate and nylon meshes offer flexibility and higher elasticity, suitable for specific textile and curved surface applications, while steel mesh dominates in electronics and precision printing due to its rigidity and dimensional stability.
By filament, mono-filament screens are widely used for high-definition and precision printing applications, particularly in electronics and glass. Multi-filament meshes find usage in broader surface applications, offering better ink retention and distribution.
By mesh count segment reveals strong demand for 111 to 220 TPI, balancing resolution and ink flow, while counts above 305 TPI are favored in high-precision industries.
By Thread diameter segmentation shows 31 to 60 microns as the preferred range due to its compatibility with diverse applications.
- For example, NBC Meshtec’s HLE seriesfeatures thread diameters of 34–50µm, as confirmed in their technical datasheets, making it a standard choice for general-purpose screen printing on textiles, plastics, and posters.
By End-use industry analysis identifies textiles as the leading sector, followed by packaging and electronics, with growing interest from glass, ceramics, and specialty printing industries. The Screen Printing Mesh Market adapts across segments to meet specific performance, cost, and production demands.
- For example, SAATI’s 180T mesh, paired with ceramic inks, is applied in toughened glass and ceramic tile decorationfor automotive and architectural applications.
Segmentation:
By Material:
- Polyarylate Screen Printing Mesh
- Polyester Screen Printing Mesh
- Nylon Screen Printing Mesh
- Steel Screen Printing Mesh
By Filament:
- Mono-filament
- Multi-filament
By Mesh Count (TPI - Threads Per Inch):
- Below 80 TPI
- 81 to 110 TPI
- 111 to 220 TPI
- 221 to 305 TPI
- Above 305 TPI
By Thread Diameter:
- Below 30 microns
- 31 to 60 microns
- 61 to 90 microns
- Above 90 microns
By End-use Industry:
- Textile
- Packaging
- Glass & Ceramics
- Electronics & Electrical
- Others
By Region:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
The North America Screen Printing Mesh Market size was valued at USD 178.61 million in 2018 to USD 201.11 million in 2024 and is anticipated to reach USD 304.38 million by 2032, at a CAGR of 5.4% during the forecast period. North America holds a 27.91% share of the global market in 2024. The region benefits from a mature textile and industrial printing ecosystem, with consistent demand from sectors like electronics, automotive, and packaging. Leading manufacturers focus on high-quality mesh solutions tailored for technical and precision printing applications. It benefits from advanced infrastructure, strong R&D capabilities, and widespread adoption of automation in printing processes. The U.S. remains the dominant market due to its established commercial printing and advertising industries. Demand for sustainable printing solutions also fuels innovation in mesh coatings and materials. Canada contributes with niche segments like medical printing and specialty textiles.
Europe
The Europe Screen Printing Mesh Market size was valued at USD 134.19 million in 2018 to USD 146.11 million in 2024 and is anticipated to reach USD 206.75 million by 2032, at a CAGR of 4.5% during the forecast period. Europe accounts for 20.27% of the global market in 2024. The region emphasizes precision printing in industries such as electronics, automotive components, and glass decoration. Germany, France, and Italy lead the market with high adoption of screen printing for industrial and commercial use. It benefits from a strong focus on quality, sustainability, and regulatory compliance in manufacturing practices. European manufacturers invest in advanced mesh products with long lifecycle and low environmental impact. Custom printing applications for luxury packaging and fashion also contribute to regional demand. Growth remains steady, supported by innovation and product differentiation. The region maintains strong trade relations, boosting cross-border distribution.
Asia Pacific
The Asia Pacific Screen Printing Mesh Market size was valued at USD 232.60 million in 2018 to USD 273.85 million in 2024 and is anticipated to reach USD 442.64 million by 2032, at a CAGR of 6.2% during the forecast period. Asia Pacific holds the largest share of 38.00% in 2024. The region dominates due to its robust textile production base and expanding electronics manufacturing sector. China, India, Japan, and South Korea drive significant demand for screen printing mesh in both consumer and industrial applications. It gains further momentum from increasing domestic consumption and growing export activity. Government initiatives supporting local manufacturing enhance adoption in packaging and apparel sectors. Regional suppliers expand capacity and distribution to meet rising demand. Competitive pricing and labor availability strengthen Asia Pacific’s position in global mesh production and export. Adoption of digital-screen hybrid workflows also grows steadily.
Latin America
The Latin America Screen Printing Mesh Market size was valued at USD 46.12 million in 2018 to USD 52.31 million in 2024 and is anticipated to reach USD 74.56 million by 2032, at a CAGR of 4.6% during the forecast period. Latin America represents 7.26% of the global market in 2024. Brazil and Mexico serve as the key contributors with active textile, automotive, and food packaging sectors. It supports demand for mesh products suited to medium-volume, cost-efficient printing processes. Screen printing remains a preferred technique for promotional goods, signage, and labeling. Regional manufacturers gradually invest in higher-quality mesh variants to improve print output. Infrastructure development and urbanization fuel demand for decorative and construction-related applications. Imports from Asia-Pacific and North America supplement local supply chains. The region offers growth potential with rising awareness of brand differentiation through quality printing.
Middle East
The Middle East Screen Printing Mesh Market size was valued at USD 22.55 million in 2018 to USD 24.06 million in 2024 and is anticipated to reach USD 32.76 million by 2032, at a CAGR of 4.0% during the forecast period. The region accounts for 3.34% of the global market in 2024. Growth is driven by increasing demand in signage, advertising, and industrial labeling across the Gulf Cooperation Council countries. It supports niche applications in packaging, particularly for food, cosmetics, and retail goods. The UAE and Saudi Arabia lead regional adoption due to expanding construction and tourism sectors. Local businesses invest in screen printing solutions to improve product branding and visibility. Demand for decorative printing in interior design and architecture also grows. Market development is supported by rising awareness of print quality and modern production technologies. Suppliers focus on durability and weather resistance in mesh products.
Africa
The Africa Screen Printing Mesh Market size was valued at USD 15.94 million in 2018 to USD 23.13 million in 2024 and is anticipated to reach USD 34.24 million by 2032, at a CAGR of 4.9% during the forecast period. Africa represents 3.21% of the global market in 2024. The market is emerging, with growing demand from local textile producers and advertising agencies. South Africa and Nigeria lead adoption with screen printing used widely for apparel, signage, and promotional products. It faces infrastructure and skills limitations but sees gradual investment in modern printing technologies. Regional growth is supported by entrepreneurship and small-scale production across urban centers. Educational campaigns and affordable mesh products expand awareness of screen printing benefits. International players explore partnerships to improve access to quality materials. Africa presents long-term growth opportunities driven by demographic expansion and economic diversification.
Key Player Analysis:
- NBC Meshtec
- Asada Mesh
- Nippon Tokushu Fabric
- HEBEI Anping Printing Screen Co., Ltd
- Qingdao Greatwall Industry Co., Ltd
- Shanghai Gold-Up Screen-Printing Facilities Co. Ltd
- Sefar AG
- Saati S.p.A
- HAVER & BOECKER OHG
- Weisse & Eschrich GmbH & Co. KG
Competitive Analysis:
The Screen Printing Mesh Market features a mix of global manufacturers and regional specialists competing on quality, technology, and service. Top players invest in research to improve mesh tension, coating durability, and precision printing performance. It offers a diverse product range-from polyester to stainless steel options-tailored to various end-use industries like textiles, electronics, and packaging. Suppliers focus on forging strong relationships with printing equipment makers and distributors, enhancing their market access and application support. Competitive pricing and local production capabilities give regional vendors an advantage in cost-sensitive markets. It faces emerging competition from digital printing convergence, but firms differentiate through mesh longevity and high-volume efficiency. Partnerships with OEMs, turnkey service offerings, and timely delivery strengthen supplier positions. Market leaders also emphasize technical training and customer service to retain loyalty. It holds steady, driven by continuous innovation and strategic alliances.
Recent Developments:
- In March 2025, M&R Printing Equipment, Inc. expanded its exclusive partnership with Nazdar SourceOne, granting Nazdar exclusive distribution rights for M&R’s equipment in Arkansas, Louisiana, Oklahoma, and Texas. The extended collaboration includes co-developed ink systems, such as the POLARIS™ Industrial DTG Platform, enhancing quality and speed in direct-to-garment printing
Market Concentration & Characteristics:
The Screen Printing Mesh Market operates within a moderately concentrated structure where a handful of global entities lead innovation and quality standards. It combines large-scale producers with regional niche providers that address local needs and price preferences. Value chain integration remains a key characteristic, as manufacturers collaborate with screen printers, film suppliers, and equipment OEMs to ensure product compatibility. It features recurring demand due to mesh replacement cycles, promoting stable revenue streams. Quality certifications and compliance with environmental standards serve as market entry barriers. It enables firms with sustainable practices to gain advantage. The market showcases differentiation through material types, mesh count precision, and coating technologies. It supports both high-volume industrial uses and customized applications through flexible production setups.
Report Coverage:
The research report offers an in-depth analysis based on material, filament type, mesh count, thread diameter, and end-use industry. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- Rising demand for high-resolution, customized printing will expand mesh usage across textiles and specialty graphics.
- Technological advancements in mesh coating and treatment will enhance performance, durability, and print accuracy.
- Expansion of the electronics sector will drive adoption of precision meshes in applications like circuit printing.
- Growth in packaging and labeling needs will create consistent demand for mesh across FMCG and cosmetic industries.
- Increasing preference for sustainable printing processes will influence material innovation and eco-friendly mesh options.
- Emerging markets in Africa, Latin America, and Southeast Asia will open new revenue streams through local manufacturing.
- Strategic partnerships between mesh producers and printing equipment OEMs will strengthen market positioning.
- Investments in automation and workflow integration will improve production efficiency and mesh handling processes.
- Demand for hybrid printing solutions will lead to continued relevance of screen printing in combination with digital systems.
- Expansion of online retail and branding activities will increase demand for vibrant and durable printed packaging.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Screen Printing Mesh Market?
What factors are driving the growth of the Screen Printing Mesh Market?
What are the key segments within the Screen Printing Mesh Market?
What are some challenges faced by the Screen Printing Mesh Market?
Who are the major players in the Screen Printing Mesh Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Screen Printing Mesh Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Screen Printing Mesh Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 720.56 million → 2032: USD 1,095.33 million)
- 2.1.2 Volume & Revenue – Global Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Screen Printing Mesh Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Screen Printing Mesh Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Screen Printing Mesh Market Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Screen Printing Mesh Market Drivers
- 3.3 Screen Printing Mesh Market Restraints & Challenges
- 3.4 Screen Printing Mesh Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Screen Printing Mesh Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Screen Printing Mesh Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Screen Printing Mesh category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Screen Printing Mesh Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Region – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Priority market opportunity scorecards reflect the geographic scope and strategic relevance of the study. Listed markets are indicative and may be adapted to the industry.
Chapter 5. Screen Printing Mesh Cross-Border Trade & Market Access Analysis
- 5.1 International Trade & Cross-Border Activity Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024) (Volume Where Applicable)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter applies where cross-border trade or delivery is relevant to Screen Printing Mesh. Goods, services, and digital offerings are assessed using applicable classifications and transaction measures. Import-export volumes, trade balances, and route analyses are included only where meaningful to the market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Screen Printing Mesh Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – the historical period vs. 2024
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Screen Printing Mesh Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company (Volume Where Applicable)
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution (the historical period vs. 2024)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Global Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Screen Printing Mesh Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Screen Printing Mesh (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Screen Printing Mesh
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Screen Printing Mesh Market – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share (Volume Where Applicable)
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region (Volume Where Applicable)
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. North America Screen Printing Mesh Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Screen Printing Mesh Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Screen Printing Mesh Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Screen Printing Mesh Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Screen Printing Mesh Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Screen Printing Mesh Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Screen Printing Mesh Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
