
Market Overview
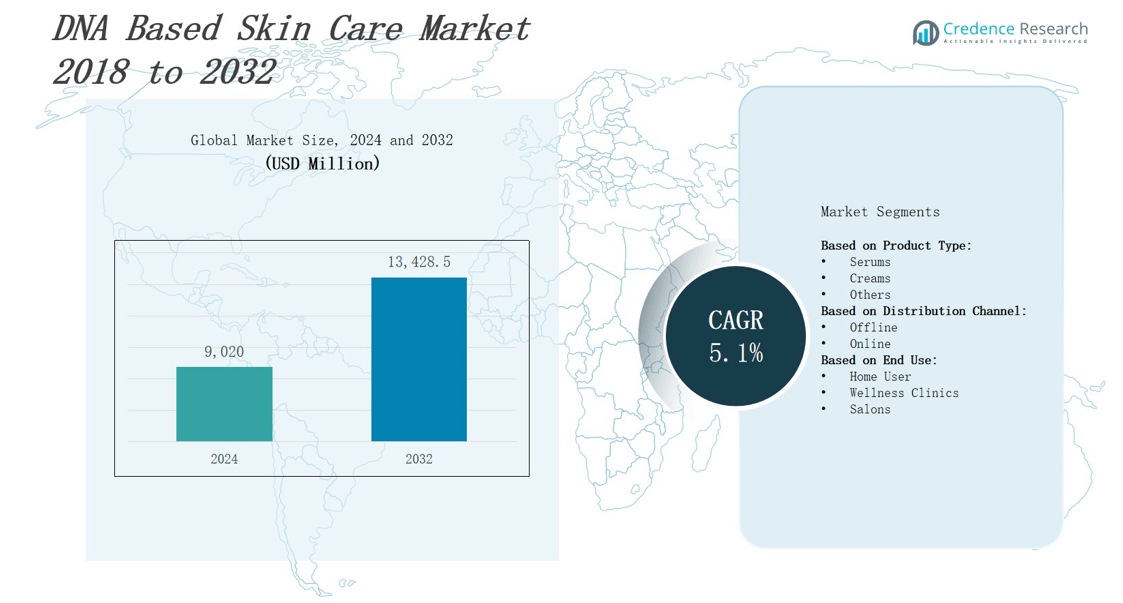
In 2024, the dna based skin care market was valued at USD 9,020 million and is projected to grow to USD 13,428.5 million by 2032 at a CAGR of 5.1%.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| DNA-Based Skin Care Market Size 2024 | USD 9,020 million |
| DNA-Based Skin Care Market, CAGR | 5.1% |
| DNA-Based Skin Care Market Size 2032 | USD 13,428.5 million |
Rising consumer demand for personalization drives the dna based skin care market, as brands leverage genomic insights to tailor formulations. Technological advances in DNA sequencing and analytics empower companies to deliver targeted treatments and improve efficacy. Growing awareness of skin health and preventive care motivates adoption of genetically informed products. Partnerships between biotech firms and cosmetic manufacturers accelerate innovation and expand product portfolios. At-home genetic testing kits and AI-powered platforms enhance customer engagement, streamline customization processes. Sustainability concerns prompt development of novel clean ingredients. Market players invest in robust research collaborations and digital platforms to differentiate offerings and seize opportunities.
North America dominates with 35% share, driven by advanced healthcare infrastructure and high consumer demand. Europe follows at 25% thanks to robust R&D and established cosmetic brands. Asia Pacific holds 20% fueled by rising incomes and digital adoption. Latin America and Middle East & Africa each account for 10%, supported by growing wellness awareness. The dna based skin care market features key players such as SkinGenie Pvt Ltd, DNA Skin Institute, ALLÉL, Anake, Targeted DNA, Jinomz, dnaskin, SKINSHIFT, LifeNome Inc., SkinDNA, Genetic Beauty, and Evergreen Health Solutions Ltd.
Market Insights
- DNA based skin care market reached USD 9,020 million in 2024 and will hit USD 13,428.5 million by 2032 at 5.1 % CAGR.
- Genomic personalization drives the dna based skin care market by delivering targeted treatments for aging, sensitivity, and pigmentation.
- Faster DNA sequencing and AI analytics enable precise formulations via matching genetic variants with optimal active‑ingredient concentrations.
- Biotech‑cosmetic partnerships co‑develop serums and masks, backed by clinical trials that validate product claims and efficacy.
- At‑home genetic kits and AI‑powered platforms streamline customization, boost engagement, and expand direct‑to‑consumer channels.
- Focus on sustainability pushes brands to use botanical extracts, biodegradable carriers, and eco‑friendly packaging in formulations.
- North America leads with 35 % share, Europe follows at 25 %, Asia Pacific holds 20 %, Latin America and MEA each secure 10 %; key players include SkinGenie, DNA Skin Institute, ALLÉL.
Market Drivers
Genomic Personalization Drives Consumer Engagement
Brands in the dna based skin care market leverage genetic analysis to tailor products to individual skin profiles. It empowers researchers to identify unique biomarkers and select active compounds with precision. Consumers gain confidence when products respond specifically to their DNA data. It supports targeted treatments for concerns like aging, sensitivity, and pigmentation. Companies highlight personalized benefits through scientific validation. This approach drives higher satisfaction and repeat purchases across demographics.
- For instance, Anake tests more than 15 genetic markers through a DNA kit and combines this data with advanced skin imaging technology to create customized skincare routines.
Technological Innovation Enhances Precision Formulations
Advances in sequencing speed and cost reduction accelerate progress in the dna based skin care market. It enables rapid interpretation of complex genetic data by AI platforms. Firms develop software that matches genetic variants with optimal ingredient concentrations. It reduces development cycles and optimizes efficacy. Bioinformatics tools analyze millions of data points to predict skin responses. This integration of technology and science fosters robust solution pipelines. Researchers refine outcomes continually.
- For instance, L’Oréal uses integrated omics data analysis-combining genomic, epigenetic, proteomic, and metabolomic information-to predict skincare treatment efficacy and tailor formulations to individual responses, improving outcomes.
Industry Collaborations Accelerate Product Development
Biotech firms partner with cosmetic companies to innovate within the dna based skin care market. Joint ventures combine genomic expertise and formulation capabilities. It supports co development of novel serums and masks. Academic institutions supply validation through clinical trials that strengthen product claims. Investors fund strategic alliances to drive rapid commercialization. It fosters shared risk and resource allocation. Collaborative platforms unite cross functional teams to streamline regulatory approval process.
Consumer Awareness Fuels Market Adoption
Consumer interest in preventive health drives demand within the dna based skin care market. Educated buyers research genetic reports before purchasing. It promotes transparency when brands publish testing methods and clinical data. Social media channels showcase personalized success stories and reviews. It elevates trust and broadens reach. Health influencers collaborate with companies to highlight targeted regimens. This momentum spurs mainstream retailers to stock DNA premium informed products alongside traditional lines.
Market Trends
Data-Driven Consumer Insights Shape Demand
Brands collect consumer genetics data to tailor skin care. The dna based skin care market responds to demand for personalized regimens. It uses insights from DNA tests to match active compounds to individual concerns. Companies maintain transparent reporting on methodology and outcomes. It fosters trust through published clinical results. Influencer feedback and social proof increase peer awareness. This trend promotes adoption in premium and mainstream segments.
- For instance, Anake uses an end-to-end DNA testing kit analyzing over 15 genetic markers combined with advanced skin imaging technology to formulate bespoke skincare routines, providing transparency through expert consultations and clinical validation.
AI-Powered Analysis Optimizes Formulations
Genetic algorithms process complex variant data to guide ingredient selection. The dna based skin care market benefits from machine learning platforms that validate efficacy predictions. It employs software to integrate genomic markers with dermatological research. Firms shorten development timelines and reduce trial costs. It ensures precise concentration of antioxidants and peptides in formulations. Regulatory bodies review validation protocols to maintain safety. This trend drives robust product pipelines.
- For instance, L'Oréal uses integrated omics data-including genomic, epigenetic, proteomic, and metabolomic markers-to predict treatment efficacy, enabling tailored product development that improves outcomes by identifying biomarkers related to success or failure of treatments.
At‑Home Testing Kits Expand Accessibility
Home DNA kits provide user friendly sample collection and rapid results. The dna based skin care market relies on direct‑to‑consumer channels to broaden reach. It connects customers with tailored treatment plans through digital portals. Dermatologists offer hybrid consultations that merge genetic reports with skin imaging. It reduces barriers that once limited personalized care. Retail partnerships integrate testing services into beauty stores. This approach boosts market penetration globally.
Sustainability Focus Influences Product Design
Biodegradable carriers and eco‑safe ingredients gain preference in the dna based skin care market. It encourages brands to swap synthetic polymers for botanical extracts and bio resin. Companies invest in renewable supply chains and transparent sourcing policies. It supports carbon neutrality goals and improves brand reputation. Consumer surveys emphasize clean‑label claims and minimal packaging waste. It drives competitive differentiation among premium offerings. This trend aligns product design with environmental values.
Market Challenges Analysis
Stringent Regulatory Requirements and Data Privacy Concerns
Brands in the dna based skin care market face stringent regulatory requirements that vary across regions. It demands robust compliance frameworks and lengthy approval cycles. Companies must secure consumer consent for genetic data collection and follow strict privacy laws. Regulators review test accuracy and product claims before granting market access. It increases development costs and delays product launches. Firms invest in legal teams to navigate evolving policies. Consumers expect transparency in data handling and secure storage practices. It forces organizations to implement advanced encryption systems, conduct regular audits under costly schedules, and enforce vendor oversight to secure third‑party data and maintain stakeholder confidence. Cross‑border genetic data transfers encounter additional restrictions that inhibit global research collaborations.
High Development Costs and Consumer Skepticism
High development costs challenge broader adoption in the dna based skin care market. It requires investment in sequencing equipment and bioinformatics infrastructure. Personalized formulations involve expensive clinical validation and specialized ingredients. Companies negotiate pricing strategies to balance affordability and profit margins. It forces brands to deliver clear value propositions to justify premium pricing. Consumers often doubt genetic tests’ accuracy and real benefits. Firms launch education campaigns to build trust and clarify scientific basis. It demands partnerships with specialized testing labs and ongoing method validation to maintain quality. Companies experiment with scalable manufacturing processes to reduce per‑unit costs. Investors monitor ROI and push for streamlined workflows to improve margin potential.
Market Opportunities
Bioinformatic Platform Integration Fuels Customized Solutions
Companies integrate bioinformatics platforms to enhance product precision. It allows real‑time analysis of genetic markers and skin phenotype. Firms in the dna based skin care market partner with biotech and AI startups. They develop targeted serums and treatment protocols. Subscription models deliver customized product deliveries. Investors fund R&D collaborations that leverage genomic databases. Brands differentiate through diagnostic apps that recommend regimens. It supports multi‑omics data integration to refine personalization further. Teams explore partnerships with academic consortia to access broader genotype‑phenotype correlations.
Emerging Markets and Hybrid Wellness Models Expand Reach
Firms in the dna based skin care market expand into Asia and Latin America to access new consumer segments. It aligns with rising health consciousness and digital adoption. Teledermatology services embed genetic profiling in virtual consultations. Brands offer hybrid wellness programs that merge DNA insights with lifestyle coaching. Retailers deploy in‑store kiosks for on‑the‑spot genetic testing. They broaden distribution channels beyond online direct sales. Partnerships with healthcare providers strengthen credibility and reach. It supports mobile sampling units that improve community engagement and collect diverse genomic data to tailor products for underserved populations.
Market Segmentation Analysis:
By Product Type
Serums capture significant revenue in the dna based skin care market due to their high potency and rapid absorption. It targets cellular repair through concentrated active compounds. Creams maintain hydration and deliver DNA‑specific peptides to support barrier function. Others include masks and gels that complement core formulations and address niche concerns. Brands allocate R&D budgets to refine serum textures and optimize cream stability. It drives differentiation through unique delivery mechanisms.
- For example, EpigenCare’s SKINTELLI test offers a direct-to-consumer DNA test that measures gene activity related to skin aging, moisture, pigmentation, and repair through epigenetic mechanisms.
By Distribution Channel
Offline retail channels maintain strong influence in the dna based skin care market through hands‑on consultations and sample testing. It supports brand engagement via in‑store staff training and educational displays. Online platforms gain traction when they offer personalized quizzes and direct‑to‑consumer genetic kits. E‑commerce sites integrate secure data portals to share results and recommend products. Brands expand partnerships with select retailers and digital marketplaces. It enhances user convenience and broadens geographic reach.
- For instance, SkinDNA offers in-clinic genetic testing for skin concerns such as UV damage and sensitivity, supported by trained staff who guide product selection, driving significant offline sales.
By End Use
Home users drive demand in the dna based skin care market through purchase of genetic test kits and tailored regimens for daily care. It allows individuals to address concerns such as sensitivity and premature aging. Wellness clinics adopt professional‑grade DNA analysis tools to guide advanced treatments. Salons incorporate genetic reports to customize facials and skin therapies. Brands develop training programs for clinicians to apply test insights. It elevates treatment precision and client satisfaction.
Segments:
Based on Product Type:
- Serums
- Creams
- Others
Based on Distribution Channel:
- Offline
- Online
Based on End Use:
- Home User
- Wellness Clinics
- Salons
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America secures the largest share at 35% in the dna based skin care market. It leverages advanced healthcare networks and high consumer awareness. It fosters partnerships with clinics and technology providers. Europe holds 25%, Asia Pacific 20%, Latin America 10%, Middle East & Africa 10%. It drives innovation through regulatory support and dedicated funding. It supports direct‑to‑consumer models alongside offline consultations. It commits to clinical validation to strengthen consumer trust.
Europe
Europe claims a 25% share in the dna based skin care market due to robust R&D investments. It emphasizes genomic research centers and academic collaborations. It enforces strict data privacy and regulatory guidelines that shape product development. North America holds 35%, Asia Pacific 20%, Latin America 10%, Middle East & Africa 10%. It features leading cosmetic brands that integrate genetic insights. It adapts formulations to local skin types through clinical trials. It expands distribution via specialist retailers and digital platforms.
Asia Pacific
Asia Pacific accounts for 20% share in the dna based skin care market driven by income growth and digital adoption. It benefits from mobile genetic test services and expanding teledermatology. It offers hybrid wellness packages that merge DNA reports with lifestyle advice. North America holds 35%, Europe 25%, Latin America 10%, Middle East & Africa 10%. It attracts foreign investment in personalized beauty ventures. It supports local startups developing cost‑effective sequencing solutions. It anticipates further growth through e‑commerce expansion and regional partnerships.
Key Player Analysis
- SkinGenie Pvt Ltd. (India)
- DNA Skin Institute (USA)
- ALLÉL (Sweden)
- Anake (Singapore)
- Targeted DNA (USA)
- Jinomz (Turkey)
- dnaskin (USA)
- SKINSHIFT (USA)
- LifeNome Inc. (USA)
- SkinDNA (Australia)
- Genetic Beauty (USA)
- Evergreen Health Solutions Ltd. (UK)
Competitive Analysis
Leading firms differentiate through proprietary genomic platforms that analyze individual DNA profiles to recommend precise skin treatments. It emphasizes partnerships with clinical dermatologists and research institutions to validate efficacy. Companies such as SkinGenie Pvt Ltd. and DNA Skin Institute secure exclusive variant databases to protect intellectual property and enhance product pipelines. Firms invest in AI tools that integrate genetic data with skin assessments to propose tailored serums and creams. They expand distribution through direct‑to‑consumer portals and premium offline kiosks. Brands publish clinical trial results and secure regulatory clearances to strengthen credibility. They adopt subscription models to ensure repeat engagement and gather longitudinal data. It pressures new entrants to demonstrate clear scientific value and rapid innovation to compete effectively.
Recent Developments
- In April 2023, MapMyGenome introduced BeautyMap™, India’s first DNA‑based test that delivers tailored skin and hair care recommendations alongside genetic counseling.
- In September 2024, Beiersdorf unveiled the Eucerin Hyaluron‑Filler Epigenetic Serum with its proprietary “Age Clock” technology to assess and target biological skin aging.
- In October 2024, SkinBB launched a skincare metaverse that leverages AI and virtual consultations to offer personalized regimen guidance in an interactive digital space.
- In March 2025, L’Oréal Groupe partnered with TruDiagnostic to study epigenomic markers and beauty indicators for longevity‑focused DNA‑based skincare solutions.
Market Concentration & Characteristics
The dna based skin care market shows a moderate concentration with a handful of specialized biotech and beauty companies controlling major genomic platforms and distribution channels. It features leading firms that hold proprietary DNA databases and advanced bioinformatic tools, securing high entry barriers. Mid‑tier brands collaborate through licensing agreements and white‑label offerings to access genetic insights. It supports strategic partnerships with research institutions to refine product pipelines and validate efficacy. Distribution channels split between direct‑to‑consumer digital portals and selective offline kiosks. Clinical dermatologists endorse high‑end formulations while home testing kits drive consumer engagement. It demands rigorous regulatory compliance and data privacy standards, which create cost hurdles for newcomers. Investors target established players with proven accuracy and strong brand recognition. It encourages niche startups to innovate around sustainable ingredients and specialized clinical services. This structure balances innovation with barriers, shaping a dynamic yet controlled market environment.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Distribution Channel, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Brands will collaborate with biotech firms to integrate advanced genomic profiling into personalized skincare solutions.
- Teledermatology providers will embed genetic reports in virtual consultations and deliver targeted skincare recommendations.
- Direct-to-consumer platforms will introduce subscription services deliver customized treatment regimens based on individual DNA profiles.
- Retailers will install in‑store kiosks enabling consumers to access genetic tests for personalized skincare solutions.
- AI platforms refine ingredient selection by correlating genomic markers with efficacy data to optimize formulations.
- Wearable sensors integrate skin metrics with DNA insights to provide real‑time guidance for skincare routines.
- Wellness clinics will adopt integrated genetic profiling tools to customize treatments and enhance clinical outcomes.
- Sustainability will drive brands to adopt ingredients and recyclable packaging for DNA‑based skin care products.
- Regulatory agencies will define protocols for genetic accuracy and data privacy to ensure consumer protection.
- Emerging markets will adopt genetic testing services and virtual consultations to deliver personalized skincare guidance.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the dna based skin care market?
What are the key segments within the dna based skin care market?
What are some challenges faced by the dna based skin care market?
Who are the major players in the dna based skin care market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 DNA-Based Skin Care Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2032; forecast to the forecast period)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global DNA-Based Skin Care Market Snapshot
- 2.1.1 Market Size – Historical (2032) & Forecast (the forecast period) (2032: USD 13,428.5 million → forecast year: —)
- 2.1.2 Volume & Revenue – Global Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 DNA-Based Skin Care Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2032 vs. the forecast year
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2032
- 2.3.2 Top 10 Players by Volume Share – 2032 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. DNA-Based Skin Care Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 DNA-Based Skin Care Market Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 DNA-Based Skin Care Market Drivers
- 3.3 DNA-Based Skin Care Market Restraints & Challenges
- 3.4 DNA-Based Skin Care Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 DNA-Based Skin Care Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 DNA-Based Skin Care Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, DNA-Based Skin Care category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 DNA-Based Skin Care Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute Revenue Growth Through the forecast period
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Region – Incremental Demand Through the forecast period
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Priority market opportunity scorecards reflect the geographic scope and strategic relevance of the study. Listed markets are indicative and may be adapted to the industry.
Chapter 5. DNA-Based Skin Care Cross-Border Trade & Market Access Analysis
- 5.1 International Trade & Cross-Border Activity Overview
- 5.1.1 Global Export Value by Country (2032)
- 5.1.2 Global Export Volume by Country (2032) (Volume Where Applicable)
- 5.1.3 Global Import Value by Country (2032)
- 5.1.4 Global Import Volume by Country (2032) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2032)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2032)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter applies where cross-border trade or delivery is relevant to DNA-Based Skin Care. Goods, services, and digital offerings are assessed using applicable classifications and transaction measures. Import-export volumes, trade balances, and route analyses are included only where meaningful to the market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 DNA-Based Skin Care Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – the historical period vs. 2032
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 DNA-Based Skin Care Market Share Analysis – 2032
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company (Volume Where Applicable)
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution (the historical period vs. 2032)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Global Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 DNA-Based Skin Care Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in DNA-Based Skin Care (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in DNA-Based Skin Care
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global DNA-Based Skin Care Market – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2032 & the forecast year) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (the forecast period)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share (Volume Where Applicable)
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region (Volume Where Applicable)
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through the forecast period
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. North America DNA-Based Skin Care Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe DNA-Based Skin Care Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific DNA-Based Skin Care Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America DNA-Based Skin Care Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East DNA-Based Skin Care Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa DNA-Based Skin Care Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. DNA-Based Skin Care Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
