
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Ostomy Care Accessories Market Size 2023 | USD 3715 Million |
| Ostomy Care Accessories Market, CAGR | 6.8% |
| Ostomy Care Accessories Market Size 2032 | USD 6287.38 Million |
Market Overview:
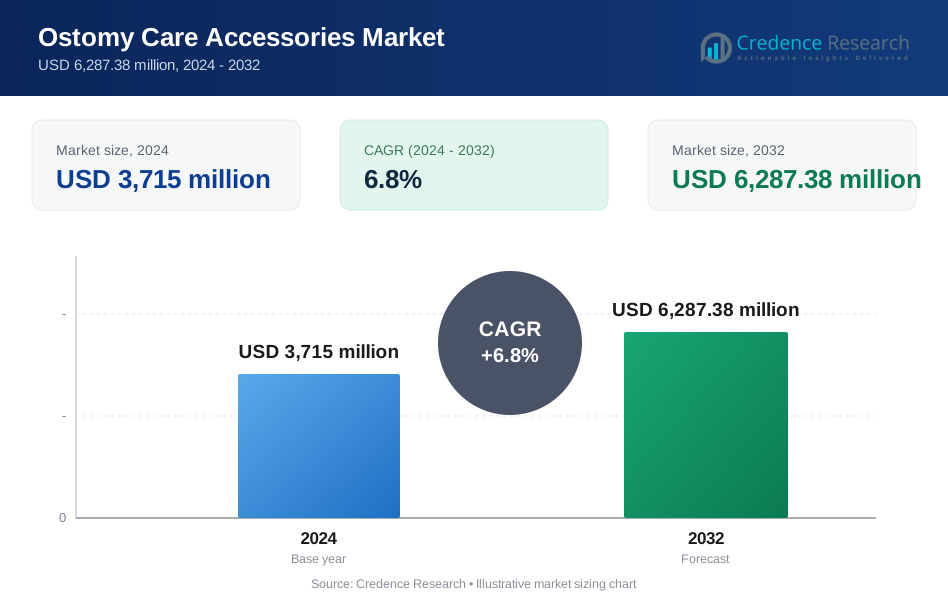
The Ostomy Care Accessories Market is projected to grow from USD 3715 million in 2024 to an estimated USD 6287.38 million by 2032, with a compound annual growth rate (CAGR) of 6.8% from 2024 to 2032.
Several factors are contributing to the growth of the ostomy care accessories market. One of the primary drivers is the growing prevalence of ostomy procedures due to conditions such as colorectal cancer, bladder cancer, and Crohn’s disease. As the number of ostomy patients rises, the demand for accessories like skin barriers, belts, and seals has increased to improve patient comfort and reduce complications. Additionally, advancements in medical technology have led to the development of more efficient and user-friendly accessories, encouraging patient compliance. Furthermore, rising awareness campaigns about ostomy care and improving reimbursement policies in various regions are boosting the adoption of ostomy accessories, enhancing patient quality of life.
Regionally, Europe dominates the ostomy care accessories market, accounting for the largest share due to a well-established healthcare infrastructure and a high incidence of colorectal cancer. The region also benefits from favorable reimbursement policies and strong awareness about ostomy care. North America follows, driven by advanced healthcare systems and increasing ostomy procedures. The Asia Pacific region is expected to witness the highest growth during the forecast period, fueled by a growing aging population, increasing healthcare expenditure, and greater awareness about ostomy care in countries like China, India, and Japan. Additionally, emerging markets in Latin America and the Middle East & Africa are expected to provide growth opportunities due to improving healthcare services and rising demand for ostomy care products.
Market Drivers:
Increasing Prevalence of Colorectal Cancer and Inflammatory Bowel Diseases:
One of the major drivers of the ostomy care accessories market is the growing incidence of colorectal cancer and inflammatory bowel diseases (IBD) such as Crohn’s disease and ulcerative colitis. These conditions often require surgical intervention, resulting in ostomy procedures. For instance, according to the World Health Organization, in 2020, more than 1.9 million new cases of colorectal cancer and over 930,000 deaths due to colorectal cancer were estimated worldwide. Additionally, patients with IBD have a significantly increased risk of colorectal cancer, with a study showing a 7% risk after 30 years of disease. As the global burden of these diseases continues to rise, particularly in aging populations, the demand for ostomy care accessories increases correspondingly. The need for accessories such as pouch covers, skin barriers, and odor control products has become essential to improving the quality of life for ostomy patients by preventing infections, minimizing discomfort, and ensuring hygiene. This growing patient population is fueling market demand for advanced ostomy care solutions.
Advancements in Ostomy Care Technology:
Advances in medical technology have significantly impacted the ostomy care accessories market by enhancing product innovation and functionality. Manufacturers are developing accessories that offer better skin protection, ease of use, and longer wear times, leading to increased patient comfort and reduced complications. For instance, skin barriers with improved adhesion and moisture control features help prevent skin irritation and infection around the stoma. Additionally, the development of more discreet and aesthetically pleasing accessories has improved patient compliance and confidence in using ostomy care products. The integration of ergonomic designs and materials that adapt to the patient’s body further boosts the adoption of these products, driving market growth.
Rising Awareness and Support for Ostomy Care:
Awareness campaigns and patient support programs aimed at improving the understanding and management of ostomy care are also key drivers of the market. Organizations and healthcare providers are increasingly focused on educating patients about the use of ostomy care accessories to enhance their overall health and comfort post-surgery. For example, the United Ostomy Associations of America (UOAA) organizes Ostomy Awareness Day annually, with activities such as the Run for Resilience Ostomy 5k and virtual art expression classes to support and educate ostomy patients. Support groups, online platforms, and medical professionals are playing a vital role in promoting ostomy care products, addressing patient concerns, and normalizing the use of accessories. This growing awareness has led to increased acceptance and use of ostomy care accessories, particularly in developed regions, where patients have better access to healthcare resources.
Favorable Reimbursement Policies and Improved Healthcare Infrastructure:”
Favorable reimbursement policies for ostomy care products, particularly in regions like Europe and North America, are positively impacting the market. Patients in these regions benefit from government and insurance coverage for a range of ostomy accessories, making them more accessible and affordable. This financial support encourages patients to invest in quality ostomy care products that improve their daily lives. Furthermore, the expansion of healthcare infrastructure, particularly in emerging economies like India and China, is increasing access to ostomy care products. As healthcare systems continue to evolve and improve, more patients are able to benefit from advanced ostomy care solutions, further driving the growth of the global ostomy care accessories market.
Market Trends:
Growing Demand for Customized and Patient-Centric Ostomy Accessories:
A significant trend in the ostomy care accessories market is the increasing demand for personalized, patient-centric solutions. Patients with ostomies often have unique needs based on their anatomy, activity level, and preferences. As a result, manufacturers are focusing on developing products that cater to individual requirements. Custom-fit skin barriers, adjustable belts, and odor-control solutions are being designed to provide maximum comfort and convenience. This shift toward customization is enhancing patient satisfaction and compliance, as more personalized products are helping patients maintain a higher quality of life. The emphasis on tailoring products to individual needs is expected to continue shaping the market's future.
Technological Advancements and Smart Ostomy Care Solutions:
The ostomy care accessories market is also witnessing the integration of advanced technology in product development. Smart ostomy devices and accessories that can monitor output, detect leakage, and alert patients or caregivers in real-time are becoming more prevalent. These innovations help reduce the risk of complications, such as skin irritation and infections, by providing timely notifications and enabling early intervention. Additionally, new materials and adhesive technologies are being introduced to enhance the durability and comfort of ostomy accessories. These advancements are not only improving patient care but also attracting more healthcare providers to recommend technologically advanced products, further driving market growth.
Shift Toward Discreet and Aesthetic Designs:
As patient awareness and comfort around ostomy care increase, there is a growing demand for more discreet and aesthetically pleasing ostomy accessories. Patients are seeking products that are less noticeable, more ergonomic, and better suited for daily wear without disrupting their lifestyle. This trend has led to the development of thinner, lighter, and more visually appealing pouch covers, skin barriers, and belts by companies like SIIL Ostomy and Byram Healthcare. For instance, SIIL Ostomy has developed over 30 different designs of pouch covers. Additionally, manufacturers are focusing on creating products that allow greater freedom of movement, catering to active lifestyles. As patients become more empowered in managing their ostomies, the preference for subtle and comfortable accessories is expected to drive innovation in the market. The details of this study can be found in the British Journal of Nursing
Expansion of Home Healthcare and Telemedicine:
The growing trend of home healthcare and telemedicine is influencing the ostomy care accessories market. As more patients prefer to manage their ostomy care at home, there is an increasing demand for user-friendly, easy-to-apply products. This shift is supported by the rise of telemedicine, which allows patients to receive virtual consultations and support from healthcare providers without visiting clinics or hospitals. For instance, services like the UOAA Virtual Ostomy Clinic provided by The Wound Company offer personalized support via telehealth The Wound Company has reported that they have conducted over 5,000 virtual consultations. The ability to access remote care services has made it easier for patients to manage their ostomies effectively and independently. As home healthcare becomes more widespread, the demand for convenient and efficient ostomy care accessories is likely to grow, further shaping the future of the market. The details of this study can be found in the AAH Ostomy White Paper
Market Restraints and Challenges:
High Costs of Ostomy Care Accessories:
One of the primary restraints in the ostomy care accessories market is the high cost of products, which can be prohibitive for many patients, particularly in developing regions. Ostomy accessories, such as skin barriers, adhesive tapes, and pouching systems, often need to be replaced regularly, adding to the long-term financial burden on patients. For those without comprehensive insurance coverage or access to reimbursement programs, the high costs can limit their ability to afford and consistently use high-quality ostomy accessories. This financial barrier can negatively impact patient care, leading to potential complications such as skin irritation or infection due to the use of suboptimal products.
Limited Awareness and Accessibility in Developing Regions:
Despite advancements in ostomy care products, awareness about their availability and use remains limited in many developing regions. Lack of education among patients and healthcare providers about the benefits of ostomy accessories can hinder adoption. Additionally, limited healthcare infrastructure in these regions poses challenges in accessing essential ostomy care products. In rural or underserved areas, distribution networks may not be well-established, making it difficult for patients to obtain the necessary accessories. This restricted accessibility not only limits market growth but also affects patient outcomes, as proper ostomy care becomes difficult to maintain.
Psychosocial and Stigma-Related Challenges:
The psychosocial challenges associated with living with an ostomy can also act as a restraint to market growth. Patients often face emotional and psychological distress due to the stigma surrounding ostomy use, which can prevent them from actively seeking out accessories that could improve their quality of life. The lack of social acceptance and the personal discomfort some patients feel about using ostomy accessories may discourage them from fully adopting the available solutions. Overcoming this barrier requires broader education and support programs to reduce stigma and encourage patients to embrace the benefits of ostomy care accessories.
Market Segmentation Analysis:
By Product, the market is categorized into belts, tapes, adhesives, convex inserts, irrigation sets & sleeves, skin protection and skin barriers, and stoma caps. Skin protection and skin barriers are widely used as they enhance patient comfort by preventing skin irritation. Belts, tapes, and adhesives are crucial for ensuring secure stoma appliance placement, while stoma caps and convex inserts provide added convenience and protection.
By Application, the market is segmented into drainage, sealing, lubrication, and cleansing. Drainage applications are the largest segment due to the need for continuous output management in ostomy patients. Sealing products help minimize leakage, while lubrication and cleansing products improve overall ostomy care.
By End User, hospitals, home care, and specialty clinics are key segments. Hospitals account for a major share of the market as they handle most initial ostomy surgeries. However, the home care segment is growing rapidly due to increasing demand for patient-centered care, enabling individuals to manage their ostomies independently with the help of user-friendly accessories. Specialty clinics also play a vital role in providing personalized ostomy care and support.
Segmentation:
By Product
- Belts, Tapes, Adhesives
- Convex Inserts
- Irrigation Sets & Sleeves
- Skin Protection and Skin Barriers
- Stoma Caps
By Application
- Drainage
- Sealing
- Lubrication
- Cleansing
By End User
- Hospitals
- Home Care
- Specialty Clinics
- North America
- US
- Canada
- Latin America
- Brazil
- Argentina
- Mexico
- Rest of Latin America
- Europe
- Germany
- UK
- Spain
- France
- Italy
- Russia
- Rest of Europe
- Asia Pacific
- China
- India
- Japan
- Australia
- South Korea
- ASEAN
- Rest of Asia Pacific
- Middle East
- GCC
- Israel
- Rest of Middle East
- Africa
- South Africa
- North Africa
- Central Africa
Regional Analysis:
North America
North America holds a significant share of the global ostomy care accessories market, accounting for approximately 35% of the market in 2023. The region’s dominance is attributed to the high prevalence of colorectal cancer and inflammatory bowel diseases, such as Crohn’s disease and ulcerative colitis, which often result in ostomy procedures. The U.S. leads the market due to its advanced healthcare infrastructure, favorable reimbursement policies, and growing awareness about ostomy care. Additionally, the presence of key players like Coloplast and ConvaTec further strengthens the market in this region. The increasing adoption of home healthcare services and the growing elderly population, who are more prone to ostomy surgeries, also contribute to the market's growth.
Europe
Europe is the second-largest region in the ostomy care accessories market, holding around 30% of the market share. The region benefits from a well-established healthcare system and a high incidence of colorectal cancer, particularly in countries like Germany, the UK, and France. Favorable reimbursement policies for ostomy products in many European countries enhance access to quality care for ostomy patients. Additionally, strong awareness campaigns and support networks across the region are helping to normalize the use of ostomy accessories, driving patient compliance and market growth. The growing trend toward personalized healthcare and patient-centric solutions also contributes to Europe's leadership in the market.
Asia Pacific
The Asia Pacific region is expected to witness the highest growth during the forecast period, with a projected compound annual growth rate (CAGR) of over 7%. Currently accounting for around 20% of the global market, this region's expansion is driven by factors such as an aging population, increasing healthcare expenditure, and improving access to medical products in countries like China, Japan, and India. Rising awareness about ostomy care and an increase in the prevalence of diseases that require ostomy procedures are also contributing to market growth. Government initiatives to expand healthcare access in rural and underserved areas are expected to further fuel demand for ostomy care accessories.
Latin America and Middle East & Africa
Latin America and the Middle East & Africa (MEA) together account for about 15% of the global ostomy care accessories market. In Latin America, Brazil and Mexico are key markets due to improving healthcare systems and rising demand for ostomy products. In MEA, countries such as Saudi Arabia, South Africa, and the UAE are witnessing increasing adoption of ostomy care accessories as healthcare infrastructure develops and awareness about ostomy management improves. However, challenges such as limited access to advanced medical products and lower awareness levels in certain areas may slow market growth in these regions, though efforts to improve healthcare delivery are expected to drive future expansion.
Key Player Analysis:
- 3M Company
- Braun Melsungen
- Coloplast Group
- ConvaTec, Inc.
- Cymed Ostomy Co.
- FNC Medical
- Hollister Incorporated
- Marlen Development and Manufacture
- Nu-Hope Laboratories, Inc.
- Salts Healthcare Ltd.
- Scapa Healthcare
- Smith & Nephew
- Torbot Group Inc.
Competitive Analysis:
The ostomy care accessories market is competitive, with a few key players holding substantial market shares. Leading companies such as Coloplast, ConvaTec, and Hollister Incorporated dominate the market through their comprehensive product offerings, innovation, and global distribution networks. These companies focus on developing advanced accessories such as skin barriers, adhesives, and belts that improve patient comfort and convenience. Their continuous investment in research and development allows them to introduce new, patient-centric solutions that cater to specific needs. Smaller companies and regional players also contribute to the market, offering niche products or targeting underserved markets. These companies often focus on cost-effective solutions to compete with larger brands. Additionally, the competitive landscape is shaped by technological advancements, such as the development of smart ostomy care products, which enable real-time monitoring and enhance patient outcomes. As competition intensifies, companies are also increasingly focusing on improving user experience and expanding their global reach.
Recent Developments:
- On May 2024, Coloplast, multinational company that develops, manufactures and markets medical devices and services related to ostomy, urology, continence, and wound care bolsters its ostomy care portfolio with three significant product launches: Heylo, the world's first digital leakage notification system, has received reimbursement approval in the UK. Additionally, the SenSura Mio ostomy range has been expanded with two new products.
- In January 2023, OstomyCure, Medical Technology company announced achieving a significant milestone by fully recruiting patients for the clinical trial of its proprietary titanium port implant technology, TIES. TIES is designed to be implanted within the stoma and features a lid for effective opening and closing.
- In February 2022, HR Pharmaceuticals, Inc., health care consumables company introduced Vitus Ostomy Care, a comprehensive line of accessories aimed at enhancing stoma and skin protection while ensuring a secure seal.
- In January 2022, Owens & Minor Inc. global healthcare logistics company and Apria Inc. provider of home healthcare equipment has finalized an agreement where Owens & Minor would acquire Apria, a move expected to expand their ostomy product portfolio
Market Concentration & Characteristics:
The ostomy care accessories market is moderately concentrated, with a few key players dominating the global market. Leading companies such as Coloplast, ConvaTec, and Hollister Incorporated hold significant market shares due to their extensive product portfolios, strong distribution networks, and continued investment in research and development. These companies focus on innovation, developing advanced and patient-centric ostomy accessories like skin barriers, seals, and belts to enhance patient comfort and ease of use.The market is characterized by growing demand for personalized, efficient, and aesthetically pleasing products. Increasing awareness and patient education, particularly in developed regions, are driving greater adoption of ostomy accessories. However, the market faces challenges related to high product costs and limited access in developing regions. Additionally, the rising trend of home healthcare and advancements in smart technology are shaping the future of the market, with manufacturers focusing on improving product functionality and patient outcomes.
Report Coverage:
The research report offers an in-depth analysis based on By Product, By Application and By End User. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The increasing prevalence of colorectal cancer and inflammatory bowel diseases will drive demand for ostomy care accessories.
- Technological advancements will continue to enhance product designs, improving durability, comfort, and user-friendliness.
- Rising awareness and patient education programs will boost adoption of ostomy accessories, particularly in developing regions.
- Growing emphasis on personalized and custom-fit products will cater to individual patient needs, increasing market appeal.
- The integration of smart technology in ostomy devices will offer real-time monitoring and alerts, improving patient care.
- Expansion of home healthcare services will create a greater need for user-friendly, self-applied ostomy care accessories.
- The trend towards discreet and aesthetic designs will further enhance patient confidence and increase product adoption.
- Emerging markets in Asia-Pacific and Latin America will offer significant growth opportunities as healthcare infrastructure improves.
- Reimbursement policies in developed countries will continue to support market growth by making accessories more affordable.
- Collaboration between manufacturers and healthcare providers will drive innovation and improve access to advanced ostomy care products.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the Ostomy Care Accessories Market?
What factors are driving the growth of the market?
Which region is expected to see the highest growth?
What are the main challenges in the ostomy care accessories market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Ostomy Care Accessories Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Ostomy Care Accessories Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 3,715 million → 2032: USD 6,287.38 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Ostomy Care Accessories Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Ostomy Care Accessories Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Ostomy Care Accessories Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Ostomy Care Accessories Market Drivers
- 3.3 Ostomy Care Accessories Market Restraints & Challenges
- 3.4 Ostomy Care Accessories Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Ostomy Care Accessories Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Ostomy Care Accessories Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Ostomy Care Accessories category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Ostomy Care Accessories Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Ostomy Care Accessories Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Ostomy Care Accessories market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Ostomy Care Accessories Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Ostomy Care Accessories Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Ostomy Care Accessories Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Ostomy Care Accessories (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Ostomy Care Accessories Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Ostomy Care Accessories Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Ostomy Care Accessories Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Ostomy Care Accessories Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Ostomy Care Accessories Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Ostomy Care Accessories Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Ostomy Care Accessories Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Ostomy Care Accessories Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Ostomy Care Accessories Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
