
Market Overview
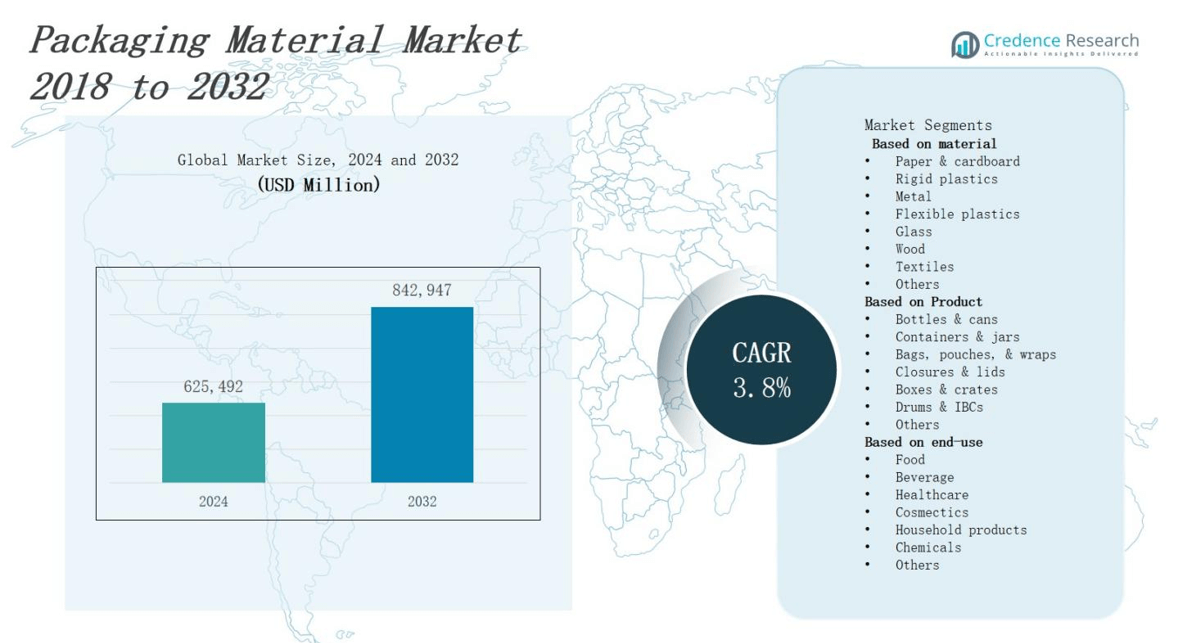
The Packaging Material Market is projected to expand from USD 625,492 million in 2024 to USD 842,947 million by 2032, registering a CAGR of 3.8%.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Packaging Material Market Size 2024 | USD 625,492 million |
| Packaging Material Market, CAGR | 3.8% |
| Packaging Material Market Size 2032 | USD 842,947 million |
E‑commerce expansion and stringent environmental regulations drive significant demand for sustainable, cost‑effective, lightweight packaging materials that reduce costs and carbon footprints. Manufacturers invest in recyclable polymers, bio‑based substrates, and advanced barrier films to extend shelf life and meet regulatory requirements. They leverage digital printing and automation to accelerate customization and improve operational efficiency. Smart packaging trends, including RFID tags and IoT sensors, enhance traceability and consumer engagement. Collaboration between suppliers and brand owners fosters innovation in modular designs and closed‑loop recycling systems. Companies pursue multi‑material hybrids and circular economy solutions to stay competitive and achieve long‑term market growth.
Asia Pacific leads the Packaging Material Market with robust e‑commerce growth and manufacturing capacity. Europe follows through advanced recycling infrastructure and stringent sustainability mandates. North America drives demand via automation, smart packaging, and strong consumer goods sectors. Latin America benefits from expanding retail and food service industries, while Middle East & Africa grows through oil, chemical, and pharmaceutical applications. Major competitors include Stora Enso, Owens‑Illinois, Crown Holding, Berry Plastics, Amcor, Ball Corporation, Sealed Air, Mondi, International Paper Company, and Reynolds Group, all investing in innovation and regional expansion to capture market share.
Market Insights
- The Packaging Material Market will grow from USD 625,492 million in 2024 to USD 842,947 million by 2032, at a CAGR of 3.8%.
- E‑commerce expansion and strict environmental regulations drive demand for sustainable, lightweight packaging solutions.
- Manufacturers invest in recyclable polymers, bio‑based substrates, and advanced barrier films to extend shelf life and meet compliance.
- Companies deploy digital printing and automation to speed customization and boost operational efficiency.
- Smart packaging features-RFID tags, IoT sensors, active materials-enhance traceability and consumer engagement.
- Asia Pacific leads with 40% market share, followed by Europe (25%), North America (20%), Latin America (8%), and Middle East & Africa (7%).
- Stora Enso, Owens‑Illinois, Crown Holding, Berry Plastics, Amcor, Ball Corporation, Sealed Air, Mondi, International Paper Company, and Reynolds Group compete through sustainability and technological innovation.
Market Drivers
Rising E‑Commerce and Sustainability Innovations
E‑commerce expansion drives packaging demand and sparks innovation in lightweight, durable materials. The Packaging Material Market responds to stringent environmental regulations by shifting toward recyclable polymers and bio‑based substrates. It uses barrier films to extend shelf life without increasing thickness. Manufacturers adopt automation and digital printing to customize packaging. Companies invest in research to create compostable materials compliant with regulatory standards. Collaboration between brands and suppliers accelerates sustainable design adoption.
- For instance, companies like KWiiD provide reusable box systems designed for multiple shipping cycles, improving sustainability by reducing reliance on single-use materials.
Cost‑Effective Materials and Operational Efficiency
Supply chain pressures push companies to seek cost‑effective packaging solutions without compromising quality. The Packaging Material Market supports this need by offering lightweight polymers and optimized material blends. It relies on just‑in‑time production to reduce inventory waste and storage expenses. Manufacturers use analytics to forecast demand and optimize procurement. They apply lean manufacturing principles to cut cycle times and minimize scrap. Strategic partnerships with raw material suppliers ensure price stability.
- For instance, OCEANIUM, a UK-based startup, produces home-compostable bio-packaging from sustainably farmed seaweed, replacing traditional throwaway packaging while maintaining durability.
Technological Integration and Smart Packaging Deployment
Enhanced traceability drives incorporation of smart technologies into packaging. The Packaging Material Market embraces RFID tags and IoT sensors to monitor product conditions in real time. It deploys QR codes that verify authenticity. Manufacturers integrate sensor data with cloud platforms to analyze performance and reduce losses. They develop active packaging that interacts with environment to preserve freshness. Companies partner with tech firms to innovate supply chain visibility and quality control.
Circular Economy and Regulatory Compliance
Regulatory bodies enforce stricter waste reduction and recycling mandates. The Packaging Material Market adapts by offering materials designed for circular economy models. It facilitates closed‑loop recycling through polymer grades and collection systems. Manufacturers invest in renewable feedstocks to lower carbon footprints and meet compliance targets. They optimize packaging designs to minimize material use and simplify disassembly. Companies engage stakeholders to develop industry‑wide recycling infrastructure and frameworks that support environmental goals.
Market Trends
Growing Adoption of Bio-Based and Recyclable Polymers
The Packaging Material Market embraces sustainable feedstocks to meet regulatory demands and consumer preferences. It shifts toward bio-based polymers derived from plant waste and recycled plastics that maintain barrier performance. Companies invest in research to develop compostable films with high tensile strength. They incorporate recycled content to reduce dependency on virgin materials and lower carbon footprints. Suppliers collaborate on certification programs to standardize quality and verify recyclability across regions.
- For instance, Danimer Scientific has developed compostable films with high tensile strength using polyhydroxyalkanoates (PHA), a bio-based polymer derived from bacterial fermentation, which are used in packaging applications to replace traditional plastics.
Integration of Smart and Active Packaging Technologies
The Packaging Material Market leverages sensor-enabled materials to track product conditions in real time. It employs RFID tags and QR codes for authentication and supply chain transparency. Companies produce active packaging that releases preservatives in response to moisture changes. They integrate temperature indicators that alert handlers to deviations. Firms partner with technology providers to incorporate nano-materials that monitor freshness. This trend enhances safety and supports data-driven logistics decisions processes.
- For instance, BASF SE focuses on developing biodegradable, high-barrier coatings and nanotechnology-enhanced active packaging that extend shelf life and reduce food waste by monitoring freshness indicators.
Expansion of Digital Printing and Customization Capabilities
The Packaging Material Market benefits from advanced digital printing to deliver personalized designs and rapid prototyping. It reduces lead times and supports small batch runs. Brands request variable data printing for targeted promotions and seasonal campaigns. Manufacturers adopt UV-curable inks to ensure high-resolution graphics and durability. They integrate workflow software to automate color management and quality control. This trend strengthens brand engagement and increases market agility and operational efficiency.
Emergence of Hybrid Materials and Light-Weighting Solutions
The Packaging Material Market explores hybrid composites that combine paperboard and plastics for strength and recyclability. It designs thin-gauge films to cut material usage and reduce shipping costs. Companies assess life-cycle impact to guide material selection. They trial coatings that enhance barrier properties without adding weight. Suppliers collaborate on pilot lines to test multi-layer structures. This trend drives innovation and supports sustainability targets and operational cost optimization across industries.
Market Challenges Analysis
Stringent Regulatory Compliance and Material Cost Volatility
Tight environmental laws require continuous updates to material formulations and approval processes. The Packaging Material Market faces pressure to comply with varied regulations across jurisdictions and certification schemes. It must absorb increased testing costs without passing them entirely to consumers. Raw material price shifts force budgeting challenges for producers and brand owners. It demands supply chain flexibility to secure alternative sources under short notice. Companies struggle to synchronize regulatory timelines and commercial launches without delaying product rollout.
Balancing Performance Requirements and Circular Economy Goals
High barrier properties and durability remain critical for many sectors, but circular economy targets require easier recyclability. The Packaging Material Market must innovate composite structures that maintain performance without harm to recycling streams. It faces technical barriers when replacing plastic layers with bio‑based films that sometimes lack moisture resistance. Cost constraints hinder adoption of novel materials that meet both performance and sustainability benchmarks. It demands close collaboration between designers, material scientists, and waste management firms. Industry players must educate recycling facilities to handle new substrates effectively.
Market Opportunities
Expansion of E‑Commerce and Customization Services
Rising online retail volumes create demand for tailored packaging solutions that enhance consumer experience and reduce returns. The Packaging Material Market capitalizes on advanced digital printing and automation platforms to deliver personalized designs at scale. It offers variable data printing that supports targeted promotions and seasonal releases. Manufacturers integrate rapid prototyping workflows to shorten product launch cycles. Strategic investments in smart packaging enable real‑time tracking and interactive brand engagement. Collaboration with e‑tailers secures long‑term contracts and drives volume growth.
Growth in Circular Economy Collaborations and New Feedstocks
Global sustainability commitments open avenues for partnerships between material producers, recyclers, and brand owners. The Packaging Material Market leverages bio‑based polymers and mono‑material structures that facilitate efficient recycling streams. It pilots pilot programs with waste management firms to validate closed‑loop solutions. Companies explore agricultural residues and algae‑derived polymers to diversify feedstock sources. Joint ventures accelerate certification of compostable films in key regions. This trend reduces dependence on virgin plastics and aligns with corporate net‑zero targets.
Market Segmentation Analysis:
By Material
Paper & cardboard lead demand due to wide use and recyclability. Rigid plastics dominate volume in durable applications, while flexible plastics support lightweight, cost‑effective formats. Metal segments find use in premium and corrosion‑resistant solutions. Glass meets sustainability goals in beverages and pharmaceuticals. Wood and textiles serve niche markets requiring natural or biodegradable packaging. Others include hybrid composites tailored to specific performance needs. Packaging Material Market tracks material preferences to guide product development and investment strategies.
- For instance, Tetra Pak employs paperboard in its beverage cartons to enable recyclability while maintaining product safety.
By Product
Bottles & cans account for substantial share given beverage and consumer goods requirements. Containers & jars sustain growth in food and cosmetic segments. Bags, pouches, & wraps register rapid uptake due to convenience and minimal waste. Closures & lids deliver functional value by preserving quality and ensuring safety. Boxes & crates support logistics and bulk transport. Drums & IBCs handle industrial chemicals and large‑scale storage. Packaging Material Market analyzes product performance to optimize manufacturing and distribution.
By End‑Use
Food applications represent the largest revenue source, driven by fresh and processed goods demand. Beverage segment follows through stringent safety and shelf‑life requirements. Healthcare packaging demands sterile, tamper‑evident formats for pharmaceuticals and medical devices. Cosmetics grow on innovation in premium and sustainable solutions. Household products use diverse formats to balance functionality and cost. Chemical end‑use requires robust, corrosion‑resistant containers. Packaging Material Market evaluates end‑use trends to align material selection with industry requirements.
- For instance, Ball Corporation specializes in metal beverage containers with advanced tamper-evident features and a strong commitment to sustainability, alongside innovations in recyclable aluminum cans that preserve product freshness
Segments:
Based on material
- Paper & cardboard
- Rigid plastics
- Metal
- Flexible plastics
- Glass
- Wood
- Textiles
- Others
Based on Product
- Bottles & cans
- Containers & jars
- Bags, pouches, & wraps
- Closures & lids
- Boxes & crates
- Drums & IBCs
- Others
Based on end-use
- Food
- Beverage
- Healthcare
- Cosmectics
- Household products
- Chemicals
- Others
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
Asia Pacific
Asia Pacific holds a market share of 40%. Strong e‑commerce volumes drive high packaging demand. The Packaging Material Market taps into regional manufacturing hubs with robust polymer and paper production. It supports local brand growth through cost‑effective logistics. Governments enforce strict environmental standards. Suppliers participate in joint ventures to expand capacity. Rapid urbanization and rising disposable incomes further fuel demand for innovative sustainable packaging solutions across multiple industries.
Europe
Europe commands a market share of 25%. The Packaging Material Market leverages strong recycling infrastructure to boost sustainable materials. It serves diverse industries from food processors to pharmaceutical firms. Regional regulations require high recyclability standards. Manufacturers innovate through mono‑material structures and barrier coatings. Partnerships with research institutes enhance material performance. Private investment in circular economy initiatives and consumer demand for eco‑friendly designs reinforce market momentum and drive new product development.
North America
North America holds a market share of 20%. The Packaging Material Market benefits from advanced automation and digital printing capabilities. It meets demand from e‑commerce giants and consumer goods brands. Industry players invest in smart packaging features such as RFID and IoT sensors. Firms optimize supply chain through integrated analytics. Public and private sectors fund sustainability research. Consumer expectations for personalized packaging and stringent food safety requirements accelerate adoption of innovative barrier and active packaging technologies.
Latin America
Latin America accounts for a market share of 8%. The Packaging Material Market responds to growing retail and food service sectors. It adapts materials to tropical climates and humidity concerns. Local producers expand capacity for paper and flexible plastic formats. Governments support recycling programs to reduce waste. International brands partner with regional suppliers to strengthen distribution. Market liberalization and infrastructural improvements encourage foreign investment and introduce new high‑performance packaging solutions into emerging markets.
Middle East & Africa
Middle East & Africa holds a market share of 7%. The Packaging Material Market targets oil and chemical industries with specialized containers. It develops moisture‑resistant films for arid regions. Regional hubs invest in paperboard and metal packaging for consumer goods. Stakeholders focus on building recycling infrastructure. Trade agreements facilitate import of advanced polymers and barrier materials. Growing hospitality and pharmaceutical sectors create new opportunities for premium and sustainable packaging innovations across the region.
Key Player Analysis
- Stora Enso
- Owens‑Illinois
- Crown Holding
- Berry Plastics
- Amcor
- Ball Corporation
- Sealed Air
- Mondi
- International Paper Company
- Reynolds Group
Competitive Analysis
Competition in the Packaging Material Market intensifies as global leaders invest in sustainable materials and digital capabilities. Amcor, Ball Corporation, and Crown Holding expand production capacity to meet e‑commerce demand. International Paper Company and Mondi focus on mono‑material solutions to improve recyclability. Owens‑Illinois and Reynolds Group deploy lightweight glass and flexible packaging to reduce costs. Sealed Air and Berry Plastics differentiate through active and smart packaging technologies. Stora Enso strengthens partnerships in bio‑based polymers to support circular economy initiatives. It monitors raw material prices and regulatory shifts to adjust product portfolios quickly. Strategic alliances with technology firms and investments in automated manufacturing lines enable faster time‑to‑market. Regional diversification and customer‑centric service models help companies capture emerging market share in Asia Pacific and Latin America. Firms leverage data analytics to forecast demand and optimize supply chain efficiency. They pursue targeted acquisitions to enter niche segments.
Recent Developments
- On February 20, 2024, IntegraMaterials launched its new heat-sealable paper pouch Cycle Pack. The Cycle Pack features a paper base, incorporating a surface treatment with protective barrier properties. The heat-sealable solution provides robust protection against humidity, light, and oxygen.
- In February 2024, Yorkshire Packaging Systems (YPS) launched compostable shrink films. The compostable film will be teamed up with an l-sealer for a high-gloss finish and strong seal, ideal for display packaging. It is available from 12-38 microns, with excellent tensile strength and a bright, highly transparent finish.
- On June 16, 2025, Amcor develops a first‑of‑its‑kind more sustainable shrink bag that reduces material use while maintaining barrier performance.
- On February 24, 2025, Berry Global and Mars announce new packaging solutions made from 100% recycled content for select Mars confectionery products.
Market Concentration & Characteristics
High entry barriers and economies of scale shape concentration in the Packaging Material Market. Global leaders such as Amcor, Ball Corporation, and International Paper hold major revenue shares, leveraging their vast production facilities and distribution networks. It requires substantial capital investment in specialized extrusion and coating equipment and compliance testing. Mid‑tier firms differentiate through regional focus and niche materials, including compostable polymers and mono‑material structures. Suppliers forge partnerships with brand owners to secure long‑term contracts and share innovation costs. Consolidation through mergers and acquisitions further concentrates power among leading players. Technological advances in automation and digital printing accelerate time‑to‑market but raise investment thresholds for smaller entrants. Diverse customer requirements across food, beverage, healthcare, and industrial sectors demand flexible production capabilities. Competitive pressure drives continuous portfolio optimization and cost management to sustain profitability.
Report Coverage
The research report offers an in-depth analysis based on Material, Product, End-Use and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Mono-material packaging designs increase recycling efficiency by simplifying separation processes, reducing contamination of waste streams.
- AI-driven quality control systems detect manufacturing defects in realtime, minimizing waste while improving product consistency.
- Strategic alliances with bio-feedstock suppliers secure sustainable raw materials, supporting long-term resource availability for manufacturers.
- Smart packaging integrates temperature indicators and freshness sensors, improving transparency across supply chains, reducing spoilage.
- Automation investments increase production throughput and reduce labor expenses, improving operational scalability across packaging applications.
- Digital printing accelerates customization, supports small batch runs, enhancing brand differentiation through high-resolution packaging graphics.
- Hybrids combine strength and recyclability, enabling performance improvements, meeting circular economy requirements for packaging design.
- Collaborations between suppliers and brands foster innovation, accelerate product development, aligning packaging solutions with demand.
- Regulatory partnerships support streamlined approvals for novel materials, reducing time to market, ensuring jurisdictional compliance.
- Investment in closed-loop recycling infrastructure enables circular economy goals and lowers reliance on virgin feedstocks.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
E-commerce Expansion and Customization
The rapid growth of e-commerce is increasing demand for packaging materials that are lightweight, durable, and customizable, driving innovation in digital printing and automation to support fast, flexible packaging solutions.
Stringent Environmental Regulations
Tighter global regulations on packaging waste and recyclability are pushing manufacturers to invest in recyclable polymers, bio-based substrates, and advanced barrier films, accelerating the shift toward sustainable packaging materials.
Technological Integration and Smart Packaging
The adoption of RFID tags, IoT sensors, and active packaging materials is enhancing traceability, product safety, and consumer engagement, creating new value propositions and differentiating offerings in the packaging material market.
Cost-Effective and Lightweight Materials
Supply chain pressures and the need to reduce shipping and storage costs are driving the adoption of lightweight polymers and optimized material blends, supporting operational efficiency and cost savings for manufacturers and end-users.
Circular Economy and Closed-Loop Recycling
Growing emphasis on circular economy models and closed-loop recycling systems is encouraging the development of mono-material and hybrid packaging solutions, reducing reliance on virgin feedstocks and supporting long-term sustainability goals.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Packaging Material Market?
What are the key segments within the Packaging Material Market?
What are some challenges faced by the Packaging Material Market?
Who are the major players in the Packaging Material Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End-Use
- 1.2.1 Food
- 1.2.2 Beverage
- 1.2.3 Healthcare
- 1.2.4 Cosmetics
- 1.2.5 Household products
- 1.2.6 Chemicals
- 1.2.7 Others
- 1.3 By Product
- 1.3.1 Bottles & cans
- 1.3.2 Containers & jars
- 1.3.3 Bags, pouches, & wraps
- 1.3.4 Closures & lids
- 1.3.5 Boxes & crates
- 1.3.6 Drums & IBCs
- 1.3.7 Others
- 1.4 By Material
- 1.4.1 Paper & cardboard
- 1.4.2 Rigid plastics
- 1.4.3 Flexible plastics
- 1.4.4 Metal
- 1.4.5 Glass
- 1.4.6 Wood
- 1.4.7 Textiles
- 1.4.8 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 1.22 trillion → 2032: USD 2.08 trillion
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Packaging Material Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Packaging Material Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Packaging Material Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Packaging Material Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Packaging Material Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Packaging Material Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Packaging Material Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Packaging Material Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 1.22 trillion → 2032: USD 2.08 trillion)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Packaging Material Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End-Use - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Food
- 12.3.7.2 Beverage
- 12.3.7.3 Healthcare
- 12.3.7.4 Cosmetics
- 12.3.7.5 Household products
- 12.3.7.6 Chemicals
- 12.3.7.7 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Product - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Bottles & cans
- 12.4.7.2 Containers & jars
- 12.4.7.3 Bags, pouches, & wraps
- 12.4.7.4 Closures & lids
- 12.4.7.5 Boxes & crates
- 12.4.7.6 Drums & IBCs
- 12.4.7.7 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Material - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Paper & cardboard
- 12.5.7.2 Rigid plastics
- 12.5.7.3 Flexible plastics
- 12.5.7.4 Metal
- 12.5.7.5 Glass
- 12.5.7.6 Wood
- 12.5.7.7 Textiles
- 12.5.7.8 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Packaging Material End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Packaging Material Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Packaging Material Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Packaging Material Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Stora Enso
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Owens-Illinois
- 18.4 Crown Holding
- 18.5 Berry Plastics
- 18.6 Amcor
- 18.7 Ball Corporation
- 18.8 Sealed Air
- 18.9 Mondi
- 18.10 International Paper Company
- 18.11 Reynolds Group
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

