
Market Overview
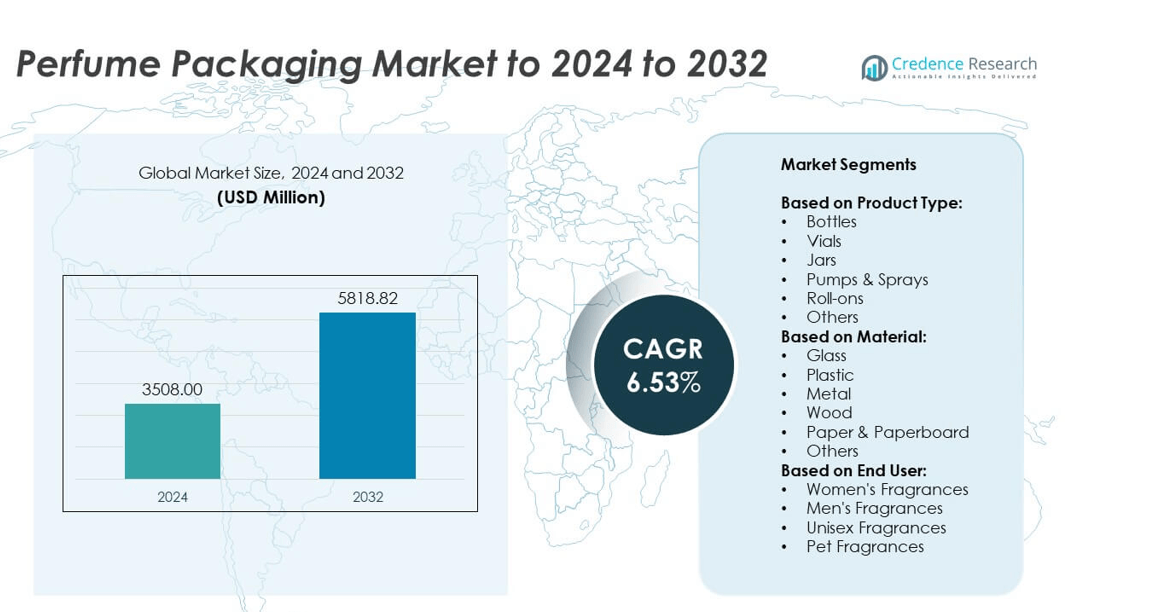
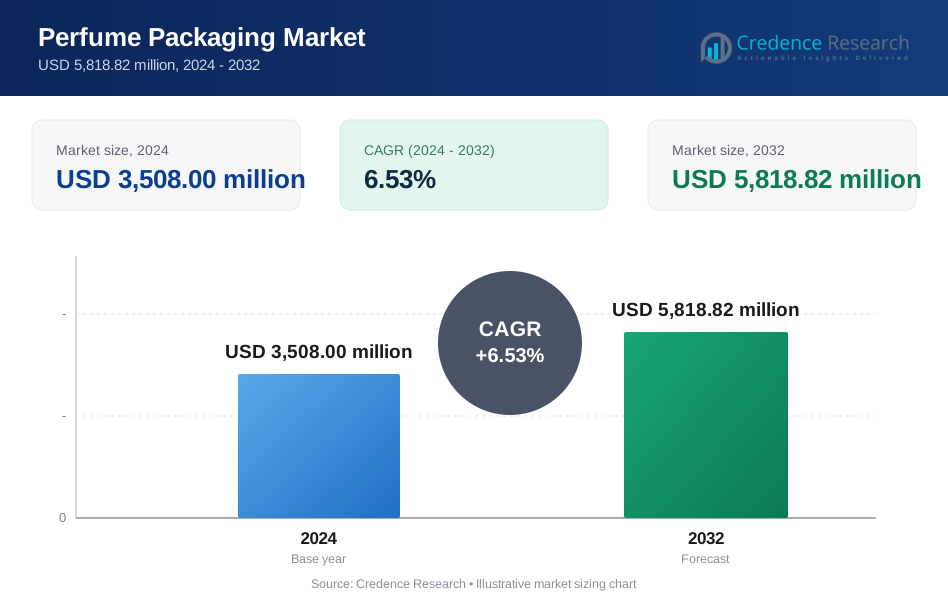
Perfume Packaging market size was valued at USD 3,508.00 million in 2024 and is anticipated to reach USD 5,818.82 million by 2032, at a CAGR of 6.53% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Perfume Packaging Market Size 2024 | USD 3,508.00 million |
| Perfume Packaging Market, CAGR | 6.53% |
| Perfume Packaging Market Size 2032 | USD 5,818.82 million |
The perfume packaging market is driven by major players such as Gerresheimer AG, Albea S.A, Vitro Corporation, AptarGroup Inc., Berry Global, Stölzle Glass Group, Verescence, and Zignago Vetro. These companies focus on premium glass bottle production, innovative closure systems, and sustainable packaging solutions to meet evolving consumer preferences. Strategic investments in lightweight glass manufacturing, refillable packaging formats, and decorative technologies strengthen their market position. North America led the market with around 35% share in 2024, supported by high demand for luxury fragrances and strong adoption of eco-friendly packaging. Europe followed closely with a 30% share, driven by luxury fragrance houses emphasizing premium aesthetics and sustainability.
Market Insights
- The perfume packaging market was valued at USD 3,508.00 million in 2024 and is projected to reach USD 5,818.82 million by 2032, growing at a CAGR of 6.53%.
- Growing demand for premium and luxury fragrances, along with sustainability initiatives, drives adoption of glass bottles and refillable packaging formats.
- Key trends include rising use of eco-friendly materials, lightweight glass production, and smart packaging technologies like NFC and QR codes for product authentication.
- The market is competitive with players focusing on innovation, decorative finishes, and partnerships with fragrance brands to launch personalized and limited-edition packaging.
- North America leads with 35% share, followed by Europe at 30% and Asia Pacific at 25%; bottles dominate the product segment with over 40% share, driven by their strong presence in luxury and mass-market fragrances.
Market Segmentation Analysis:
By Product Type
Bottles dominated the perfume packaging market in 2024, capturing over 40% of the market share. Their dominance is driven by premiumization trends and consumer preference for aesthetically appealing, durable packaging for luxury fragrances. Glass bottles with intricate designs and customizable shapes enhance brand identity and shelf appeal. The growing demand for refillable and sustainable bottles further boosts adoption, especially among luxury brands promoting eco-conscious packaging. Pumps and sprays are also witnessing steady growth, driven by convenience and precise dosing requirements for fine fragrances across both mass and premium product categories.
- For instance, Verescence has an annual production capacity of up to 600 million glass bottles for the perfumery and cosmetics industry. The company has partnered with L'Oréal on several products, including the refillable CREMA NERA Dual Essence Foundation for Armani Beauty. In September 2023, Verescence collaborated with Albéa on a 50ml refillable glass jar called TWIRL. Dior, meanwhile, has offered its own line of refillable travel bottles for its La Collection Privée, independent of Verescence.
By Material
Glass led the market with more than 50% share in 2024, driven by its premium look, barrier properties, and recyclability. High-end fragrance brands prefer glass packaging for its ability to preserve fragrance integrity and deliver a luxury experience. Rising consumer demand for sustainable and recyclable packaging materials has encouraged brands to invest in lightweight glass bottles with reduced carbon footprints. Plastic holds a significant secondary share due to its cost-effectiveness and design flexibility, particularly for travel-size products and mass-market fragrances, where weight reduction and affordability are key drivers.
- For instance, SGD Pharma produces more than 2 billion vials and bottles per year for the pharmaceutical industry. The company has a strong focus on sustainability, highlighted by initiatives like the Nova lightweight glass bottle and an award-winning CSR strategy, including achieving an EcoVadis Platinum rating. In 2024, SGD Pharma successfully produced glass bottles containing 20% post-consumer recycled glass at its Zhanjiang plant in China during its first PCR campaign.
By End User
Women's fragrances held the largest market share at over 55% in 2024, supported by high product launches and strong consumer spending on premium perfumes. Brands invest heavily in unique and elegant packaging designs to attract female consumers, focusing on personalization and luxury appeal. The rise of limited-edition collections and influencer-driven marketing campaigns further supports demand. Men’s fragrances are growing rapidly, supported by increasing grooming awareness and rising disposable incomes, while unisex fragrances are emerging as a niche segment driven by Gen Z consumers seeking gender-neutral and inclusive products.
Market Overview
Growing Demand for Premium and Luxury Fragrances
Growing demand for premium and luxury fragrances is the leading driver for the perfume packaging market. Brands are focusing on innovative, high-quality packaging to enhance shelf appeal and brand differentiation. Consumers increasingly prefer sophisticated, personalized, and sustainable packaging solutions that reflect exclusivity. This trend pushes manufacturers to invest in advanced design technologies and premium materials like glass and metal. Rising disposable incomes and urbanization, especially in emerging markets, further boost sales of premium fragrances, driving steady demand for visually appealing and durable perfume packaging.
- For instance, Interparfums Inc. reported net sales of $1.45 billion in 2024, a 10% increase over the previous year. The company's portfolio is heavily reliant on prestige fragrances, which are typically packaged in glass bottles. Interparfums has announced corporate social responsibility initiatives, with its Paris-based subsidiary, Interparfums SA, reporting that it recovered 90% of the 30 metric tonnes of waste it generated in 2023.
Rising Sustainability Initiatives
Rising sustainability initiatives are another major growth driver shaping the market. Brands are moving toward eco-friendly materials such as recyclable glass, bio-based plastics, and paperboard to meet consumer and regulatory expectations. Circular economy practices, including refillable perfume bottles and reduced plastic use, are gaining traction. These initiatives align with global sustainability goals, improving brand image and customer loyalty. Companies adopting green packaging benefit from competitive advantages and increasing acceptance among environmentally conscious consumers.
- For instance, Chanel has implemented refillable initiatives for products like the N°1 DE CHANEL cream and the 31 LE ROUGE lipstick to reduce packaging waste. The company has a stated goal of achieving net-zero greenhouse gas emissions by 2040 and reported a 1% reduction in Scope 1 and 2 emissions in 2024, alongside a 9% reduction in Scope 3 emissions. In 2024, Chanel also assessed over 90% of its Fragrance and Beauty suppliers for sustainability management systems, leveraging platforms like EcoVadis.
Technological Advancements in Manufacturing
Technological advancements in manufacturing processes act as a key driver for innovation in perfume packaging. Digital printing, 3D modeling, and automation enable faster production, cost efficiency, and mass customization. Smart packaging solutions, such as NFC-enabled tags and QR codes, allow brands to enhance consumer engagement and product authenticity verification. These technologies help brands improve supply chain efficiency and develop unique designs to differentiate their offerings. Advancements in lightweight materials and coating technologies also contribute to reduced environmental impact and better performance of perfume packaging.
Key Trends & Opportunities
Rise of Refillable and Reusable Packaging
The rapid adoption of refillable and reusable perfume packaging is a major market trend. Brands like Dior and Chanel are introducing refillable bottle systems to reduce waste and appeal to eco-conscious consumers. This trend also provides opportunities for new revenue streams through refill packs and loyalty programs. Growth in unisex fragrances further opens opportunities for minimalistic, gender-neutral packaging designs, catering to younger consumers seeking inclusivity. Customizable packaging for limited editions and personalized gifting segments is becoming a significant differentiator for premium fragrance brands globally.
- For instance, LVMH's Perfumes & Cosmetics division reported 4% organic revenue growth in 2024, driven by brand innovations and the success of flagship fragrances, including Christian Dior's Sauvage and Miss Dior Parfum.
Growth of E-commerce and Digital Packaging Solutions
E-commerce growth is creating new opportunities for innovative perfume packaging designs. With rising online fragrance sales, brands are investing in secure, tamper-proof, and visually appealing packaging that ensures safe delivery while maintaining premium aesthetics. Compact and travel-friendly packaging formats are gaining popularity to meet convenience needs. Digital-first campaigns are also driving demand for packaging with interactive features such as scannable codes and augmented reality, which enhance online shopping experiences and boost brand engagement across platforms.
- For instance, in December 2022, Puig introduced the digital platform WikiParfum, which at that time included approximately 19,600 scents and enabled users to browse, compare, and choose fragrances. The platform's library is regularly updated.
Key Challenges
High Production and Material Costs
High production and material costs remain a major challenge for perfume packaging manufacturers. The use of premium materials like glass, metal caps, and decorative finishes significantly increases production expenses. Small and mid-sized brands face margin pressures due to limited economies of scale. Fluctuations in raw material prices and rising energy costs further impact profitability. To address this, companies are focusing on lightweighting, optimizing designs, and exploring alternative materials that balance cost efficiency without compromising quality or consumer appeal.
Rising Counterfeit Products
Counterfeit products pose a growing challenge in the perfume packaging market. Fake fragrances often mimic original packaging, damaging brand reputation and consumer trust. This issue drives companies to adopt advanced anti-counterfeiting technologies such as holograms, NFC chips, and serialization on packaging. However, these solutions add extra costs to production and require constant technological updates. Regulatory authorities are also tightening compliance requirements, compelling manufacturers to invest in traceability systems and secure supply chains to prevent product duplication and safeguard brand integrity.
Regional Analysis
North America
North America held the largest share of the perfume packaging market with around 35% in 2024. Growth is driven by strong demand for premium and luxury fragrances, particularly in the United States, where consumer spending on personal care products remains high. The region benefits from established fragrance brands, high purchasing power, and significant adoption of sustainable and refillable packaging solutions. E-commerce channels further boost sales by offering convenient access to niche and designer perfumes. Manufacturers are focusing on innovative glass bottle designs and eco-friendly materials to cater to the growing preference for sustainability among environmentally conscious consumers.
Europe
Europe accounted for nearly 30% of the market share in 2024, supported by the presence of global luxury fragrance houses in France, Italy, and the UK. The region’s focus on craftsmanship and premium aesthetics drives demand for high-quality glass bottles and decorative closures. Regulatory emphasis on sustainability and recyclability encourages the use of eco-friendly materials and refillable formats. Rising popularity of artisanal and niche perfumes also contributes to growth. European manufacturers invest in design innovation and personalization features, making the region a key hub for premium packaging exports to other global markets.
Asia Pacific
Asia Pacific captured around 25% of the perfume packaging market share in 2024, emerging as the fastest-growing region. Increasing disposable incomes, rapid urbanization, and rising adoption of Western beauty and grooming trends are driving perfume consumption. Countries like China, India, and Japan are witnessing a surge in demand for both luxury and affordable fragrances. Local players are focusing on affordable, innovative packaging to cater to a diverse consumer base. Growth in e-commerce platforms and duty-free retail also supports expansion, while global brands are establishing manufacturing bases in the region to reduce costs and serve local demand.
Latin America
Latin America accounted for about 6% of the market share in 2024, driven by rising fragrance usage in Brazil and Mexico. The region is witnessing increasing demand for mid-range perfumes and packaging innovations that balance cost-effectiveness with aesthetic appeal. Local manufacturers are adopting lightweight materials and simple designs to cater to price-sensitive consumers. Growth in organized retail and expansion of international fragrance brands are supporting market development. Seasonal promotions and gifting culture further boost perfume sales, encouraging packaging manufacturers to focus on attractive, small-size, and travel-friendly formats to appeal to a wider customer base.
Middle East & Africa
Middle East & Africa held nearly 4% of the perfume packaging market share in 2024, supported by strong cultural preferences for fragrances. The region shows high demand for premium and luxury perfumes, particularly in Gulf countries, where spending on personal grooming is significant. Packaging trends lean toward ornate glass bottles and metal closures that reflect regional aesthetics and traditions. Growing tourism and duty-free sales further contribute to demand. Manufacturers are also introducing refillable packaging options and high-end customization to appeal to affluent consumers seeking exclusivity and sustainability in fragrance purchases.
Market Segmentations:
By Product Type:
- Bottles
- Vials
- Jars
- Pumps & Sprays
- Roll-ons
- Others
By Material:
- Glass
- Plastic
- Metal
- Wood
- Paper & Paperboard
- Others
By End User:
- Women's Fragrances
- Men's Fragrances
- Unisex Fragrances
- Pet Fragrances
By Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The perfume packaging market is characterized by the presence of key players such as Gerresheimer AG, SKS Bottle and Packaging Inc., Albea S.A, Vitro Corporation, Stölzle Glass Group, Zignago Vetro, SGD Pharma, Silgan Holdings Inc., Verescence, Coverpla S.A, AptarGroup Inc., Trivium Packaging, HCP Packaging, Premi Industries, Berry Global, and SGB Packaging Inc. The market is highly competitive, with companies focusing on innovation, premium design aesthetics, and sustainable solutions to capture consumer attention. Leading manufacturers invest in advanced manufacturing technologies such as lightweight glass production, digital printing, and automated decoration processes to enhance efficiency and reduce environmental impact. Strategic collaborations with fragrance brands, development of refillable and recyclable solutions, and expansion into emerging markets remain key growth strategies. Players are also prioritizing research and development to deliver unique shapes, decorative finishes, and eco-friendly materials, strengthening their market position while meeting evolving consumer preferences for personalization and sustainability.
Key Player Analysis
- Gerresheimer AG (Germany)
- SKS Bottle and Packaging Inc. (U.S.)
- Albea S.A (France)
- Vitro Corporation (Mexico)
- Stölzle Glass Group (Austria)
- ZIGNAGO VETRO (Italy)
- SGD Pharma
- Silgan Holdings, Inc. (U.S.)
- VERESCENCE (France)
- Coverpla S.A. (France)
- AptarGroup, Inc. (U.S.)
- Trivium Packaging (U.S.)
- HCP Packaging (China)
- Premi Industries (Italy)
- Berry Global (U.K.)
- SGB Packaging Inc. (U.S.)
Recent Developments
- In 2024, Aptar Beauty has released a new plastic fragrance pump made with post-consumer recycled resin (PCR).
- In 2024,Stoelzle Glass Group invested in R&D to develop lightweight glass bottles that maintain the desired luxury feel and durability. Lightweighting reduces material use, energy consumption during production, and transportation costs and emissions.
- In 2023, SGD Pharma company continued to emphasize the inherent recyclability of glass and collaborated with customers to optimize bottle designs for efficient recycling streams.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Material, End-User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will see rising demand for sustainable and recyclable perfume packaging solutions.
- Refillable and reusable packaging formats will gain significant traction among premium brands.
- Digital printing and 3D modeling will enable faster customization and unique designs.
- Smart packaging with NFC and QR codes will enhance consumer engagement and authenticity checks.
- Lightweight glass production will reduce carbon footprints and transportation costs.
- E-commerce growth will boost demand for durable, tamper-proof, and travel-friendly packaging.
- Gender-neutral and minimalist packaging designs will attract younger consumers and unisex fragrance buyers.
- Emerging markets in Asia-Pacific and Latin America will drive new growth opportunities.
- Strategic partnerships between fragrance brands and packaging suppliers will increase innovation speed.
- Automation and advanced manufacturing technologies will lower production costs and improve efficiency.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Premiumization and Luxury Fragrance Demand
The increasing consumer preference for premium and luxury fragrances is driving demand for high-quality, aesthetically appealing packaging, particularly glass bottles with intricate designs. Brands are investing in innovative packaging to differentiate their products and enhance shelf appeal, fueling market growth.
Sustainability Initiatives and Eco-Friendly Packaging
Growing environmental awareness and regulatory pressures are pushing brands to adopt recyclable materials, lightweight glass, and refillable packaging formats. These sustainability initiatives not only improve brand image but also attract eco-conscious consumers, expanding the market for green packaging solutions.
Technological Advancements in Packaging Manufacturing
Innovations such as digital printing, 3D modeling, and automation enable faster production, mass customization, and unique decorative finishes. Smart packaging technologies like NFC and QR codes enhance product authentication and consumer engagement, making packaging a key value driver.
Growth of E-commerce and Digital-First Packaging
The rise of online fragrance sales is increasing demand for secure, tamper-proof, and visually appealing packaging that ensures safe delivery and maintains premium aesthetics. Interactive packaging features and travel-friendly formats are gaining traction as brands adapt to digital retail channels.
Refillable and Reusable Packaging Trends
Brands are rapidly adopting refillable and reusable packaging systems to reduce waste and appeal to sustainability-minded consumers. This trend opens new revenue streams through refill packs and loyalty programs, while also supporting regulatory compliance and brand differentiation.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Perfume Packaging Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Perfume Packaging Market projected to grow between 2025 and 2032?
Which Perfume Packaging Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Perfume Packaging Market?
Who are the leading companies in the Perfume Packaging Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End User
- 1.2.1 Women's Fragrances
- 1.2.2 Men's Fragrances
- 1.2.3 Unisex Fragrances
- 1.2.4 Pet Fragrances
- 1.3 By Material
- 1.3.1 Glass
- 1.3.2 Plastic
- 1.3.3 Metal
- 1.3.4 Wood
- 1.3.5 Paper & Paperboard
- 1.3.6 Others
- 1.4 By Product Type
- 1.4.1 Bottles
- 1.4.2 Vials
- 1.4.3 Jars
- 1.4.4 Pumps & Sprays
- 1.4.5 Roll-ons
- 1.4.6 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 3,508.00 million → 2032: USD 5,818.82 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Perfume Packaging Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Perfume Packaging Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Perfume Packaging Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Perfume Packaging Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Perfume Packaging Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Perfume Packaging Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Perfume Packaging Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Perfume Packaging Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 3,508.00 million → 2032: USD 5,818.82 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Perfume Packaging Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End User - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Women's Fragrances
- 12.3.7.2 Men's Fragrances
- 12.3.7.3 Unisex Fragrances
- 12.3.7.4 Pet Fragrances
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Material - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Glass
- 12.4.7.2 Plastic
- 12.4.7.3 Metal
- 12.4.7.4 Wood
- 12.4.7.5 Paper & Paperboard
- 12.4.7.6 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Product Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Bottles
- 12.5.7.2 Vials
- 12.5.7.3 Jars
- 12.5.7.4 Pumps & Sprays
- 12.5.7.5 Roll-ons
- 12.5.7.6 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Perfume Packaging End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Perfume Packaging Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Perfume Packaging Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Perfume Packaging Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Gerresheimer AG
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Albea S.A
- 18.4 Vitro Corporation
- 18.5 AptarGroup Inc.
- 18.6 Berry Global
- 18.7 Stölzle Glass Group
- 18.8 Verescence
- 18.9 Zignago Vetro
- 18.10 SGD Pharma
- 18.11 Silgan Holdings Inc.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

