
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Peripheral Intravenous Catheter Market Size 2024 | USD 6,484.00 Million |
| Peripheral Intravenous Catheter Market, CAGR | 7.10% |
| Peripheral Intravenous Catheter Market Size 2032 | USD 11,224.28 Million |
Market Overview
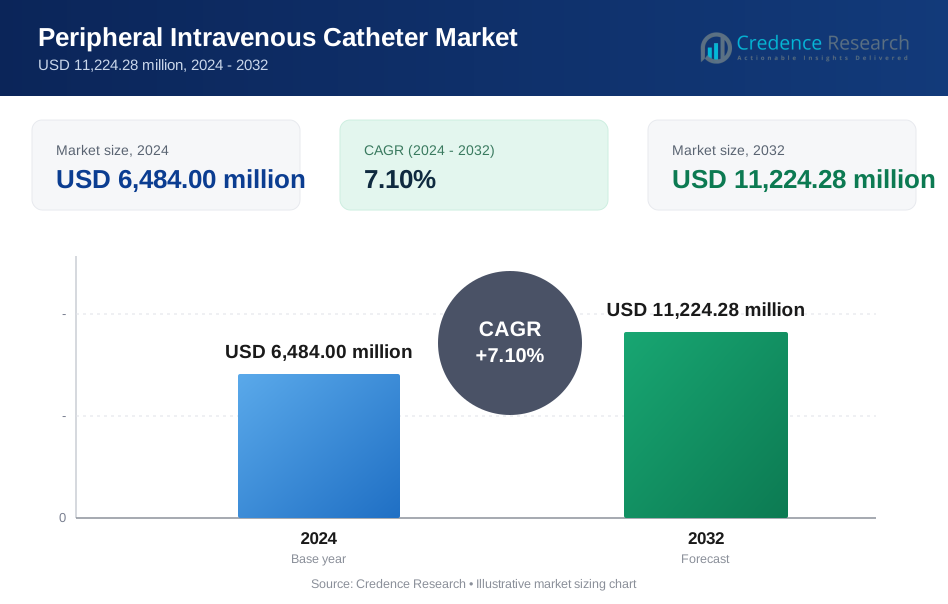
The Peripheral Intravenous Catheter Market is projected to grow from USD 6,484.00 million in 2024 to USD 11,224.28 million by 2032, reflecting a compound annual growth rate (CAGR) of 7.10%.
The Peripheral Intravenous Catheter Market is driven by the increasing prevalence of chronic diseases, which necessitate frequent intravenous therapies and medication administration. Advancements in catheter technology, such as improved safety features and materials, are enhancing patient comfort and reducing the risk of complications. The growing adoption of minimally invasive procedures and the expanding healthcare infrastructure in emerging markets are further fueling demand. Additionally, the rise in outpatient and home healthcare services is boosting the use of peripheral intravenous catheters, reflecting a broader trend toward more accessible and patient-centered care.
The Peripheral Intravenous Catheter (PIVC) Market is primarily led by North America and Europe, driven by advanced healthcare infrastructure and high adoption of innovative medical technologies. North America, particularly the United States, holds a significant share due to its robust healthcare system and focus on patient safety. Europe follows closely, with strong demand in countries like Germany, the UK, and France, where stringent regulations and a growing aging population drive market growth. Key players in this market include Terumo Corporation, B. Braun Melsungen AG, Teleflex Incorporated, and Becton, Dickinson, and Company, all leading innovation and expansion efforts globally.
Market Drivers
Rising Prevalence of Chronic Diseases and Advancements in Medical Procedures
The increasing prevalence of chronic diseases such as diabetes, heart disease, and cancer is another key driver of the PIVC market. For instance, India currently has around 60 Million diabetics, a number that is expected to swell to 90 Million by 2025. These conditions often necessitate regular intravenous therapies, making PIVCs an essential component of ongoing patient care. The rise in chronic disease cases globally is directly contributing to the demand for reliable and effective PIVCs. Furthermore, advancements in medical procedures and techniques, such as chemotherapy and dialysis, which require the use of PIVCs, are also boosting market growth. As medical technology evolves, the need for precise and efficient intravenous access is becoming more critical, further driving the adoption of PIVCs across various healthcare settings.
Increasing Healthcare Spending and Geriatric Population Growth
The Peripheral Intravenous Catheter (PIVC) Market is significantly influenced by the rise in healthcare spending globally. For instance, the World Health Organization’s Global Health Expenditure Database provides comparable data on health expenditure for more than 190 WHO Member States since 2000. As healthcare systems invest more in patient care and advanced treatment options, the demand for medical devices, including PIVCs, is expected to grow. This increased spending enables healthcare providers to adopt more advanced and higher-quality PIVCs, which improve patient outcomes and reduce complications. Alongside this, the growing geriatric population is a major driver for the PIVC market. Elderly individuals are more likely to require frequent intravenous therapies due to age-related conditions, leading to a higher demand for PIVCs. This demographic shift is expected to continue fueling market growth as the global population ages, particularly in developed regions with advanced healthcare infrastructure.
Technological Innovations and Home Healthcare Growth
Technological innovations in PIVC design and materials are playing a crucial role in expanding the market. The development of longer-dwelling catheters and peripheral venous access devices (PVADs) has improved patient outcomes by reducing the frequency of catheter replacement and minimizing the risk of complications. These advancements are enhancing patient comfort and safety, leading to increased adoption of PIVCs in both hospital and home care settings. The growing trend toward home healthcare is another significant factor driving the market. As more patients opt for home-based care, the demand for PIVCs for at-home treatments is increasing. This trend is particularly strong in regions with aging populations and rising healthcare costs, where home healthcare offers a cost-effective and patient-friendly alternative to traditional hospital care.
Growing Awareness of PIVC Benefits
Increasing awareness among healthcare professionals and patients about the benefits of PIVCs is further contributing to market growth. The reduced risk of infection, improved patient comfort, and overall effectiveness of PIVCs are becoming more widely recognized, leading to their broader adoption in various medical procedures. Educational initiatives and training programs for healthcare providers are also enhancing the proper use and management of PIVCs, which helps reduce complications and improve patient outcomes. As awareness continues to grow, the PIVC market is likely to see sustained demand, driven by the need for safe, effective, and patient-centered intravenous care solutions.
Market Trends
Focus on Patient Comfort and Safety with Smart PIVCs
The Peripheral Intravenous Catheter (PIVC) Market is increasingly focusing on enhancing patient comfort and safety, driven by innovations aimed at pain reduction and infection prevention. For instance, an evidence-based guide to PIVCs has been developed to enable better, smarter, and safer clinical practice and outcomes when using peripheral intravenous catheters. Manufacturers are developing PIVCs with advanced features that minimize discomfort during insertion and use, which is particularly important for patients requiring frequent intravenous access. Innovations in materials and catheter designs are also being implemented to reduce the risk of infections, a common concern associated with intravenous catheters. These advancements are not only improving the overall patient experience but also contributing to better clinical outcomes by minimizing complications. Moreover, the integration of smart technology into PIVCs is a significant trend in the market. Smart PIVCs incorporate sensors and monitoring systems that enable real-time tracking of infusion rates and detection of potential issues, such as blockages or leaks. These systems can trigger alerts, allowing healthcare providers to address problems before they escalate, thereby enhancing patient safety. The ability of smart PIVCs to provide valuable data and insights is transforming patient care, making these devices increasingly indispensable in both hospital and home healthcare settings.
Longer-Dwelling Catheters, PVADs, and Sustainable Practices
Another key trend in the PIVC market is the development of longer-dwelling catheters and Peripheral Venous Access Devices (PVADs), which are designed to stay in place for extended periods, reducing the need for frequent replacements. These catheters are made from advanced materials that enhance biocompatibility, minimize irritation, and reduce the risk of complications. The use of longer-dwelling catheters is particularly beneficial in managing chronic conditions, as they provide a stable and reliable means of intravenous access, thereby improving patient comfort and potentially lowering healthcare costs by reducing the number of insertions required over time. PVADs, on the other hand, offer a minimally invasive option for patients with difficult venous access, such as those with small or fragile veins. These devices are designed to reduce the risk of complications and improve patient outcomes by providing more consistent and reliable access to the venous system. In addition to these technological advancements, there is a growing emphasis on sustainability within the PIVC market. Manufacturers are exploring the use of eco-friendly materials in the production of PIVCs and are implementing recycling and waste reduction initiatives to minimize the environmental impact of these medical devices. The trend towards sustainability is increasingly important as healthcare systems worldwide become more conscious of their environmental footprint. Efforts to develop PIVCs that are both effective and environmentally responsible are likely to shape the future of the market, as manufacturers strive to meet the demands of both healthcare providers and environmentally conscious consumers.
Market Challenges Analysis
Infection Risk and Phlebitis: Addressing Complications in PIVC Use
One of the most significant challenges in the Peripheral Intravenous Catheter (PIVC) Market is the risk of healthcare-associated infections (HAIs). For instance, the Centers for Disease Control and Prevention (CDC) reports that HAIs are infections that patients get while or soon after receiving healthcare. PIVCs are a common source of these infections, which can lead to increased morbidity, mortality, and healthcare costs. The need to mitigate this risk is driving ongoing efforts to improve infection prevention practices and develop innovative PIVC designs that minimize the potential for infection. These innovations include the use of advanced materials and coatings that reduce bacterial adherence and the integration of features that enhance the aseptic insertion process. Alongside infection risks, phlebitis—an inflammation of the veins—is another common complication associated with PIVCs. Phlebitis can cause significant pain and discomfort for patients and, in severe cases, can lead to more serious complications, such as thrombosis or infection. To address this issue, manufacturers are focusing on developing PIVCs with materials and designs that reduce the risk of phlebitis, including the use of softer, more biocompatible materials and designs that promote better blood flow around the catheter.
Vein Occlusion and Regulatory Challenges: Navigating Complexities in the PIVC Market
Vein occlusion, where blood flow is blocked due to thrombosis or mechanical obstruction, presents another challenge in the PIVC market. This complication can lead to the failure of the intravenous line, requiring the removal of the PIVC and potentially causing delays in treatment. To prevent and manage vein occlusion, healthcare providers must employ proper placement techniques, monitor patients for signs of occlusion, and use appropriate anticoagulants when necessary. However, despite these preventive strategies, vein occlusion remains a significant concern, particularly in patients who require long-term intravenous therapy. In addition to these clinical challenges, PIVC manufacturers face stringent regulatory hurdles that can increase development and production costs. Compliance with regulatory requirements, such as those set by the FDA or European Medicines Agency, is essential to ensure the safety and efficacy of PIVCs. However, obtaining regulatory approval for new designs can be time-consuming and complex, often delaying the introduction of innovative products to the market. These regulatory challenges, coupled with the need for continuous innovation, make it crucial for manufacturers to maintain rigorous quality control and invest in research and development to stay competitive in the evolving PIVC market.
Market Segmentation Analysis:
By Product Type:
The Peripheral Intravenous Catheter (PIVC) Market is segmented by product type, with key categories including Short Peripheral IV Catheter, Ported PIVC, Non-Ported PIVC, Integrated/Closed PIVC, Closed with Extension Sets, and Closed PIVC. Short Peripheral IV Catheters are widely used due to their versatility and ease of insertion, making them a staple in various medical settings. Ported and Non-Ported PIVCs offer options for connecting additional lines or devices, with Non-Ported PIVCs being preferred in cases where minimal manipulation of the catheter is required. Integrated or Closed PIVCs, including those with extension sets, are designed to reduce the risk of infection and improve patient outcomes by minimizing exposure to external contaminants. The demand for these closed systems is growing, particularly in settings where infection control is a priority. The diverse range of PIVC types allows healthcare providers to select the most appropriate catheter for specific patient needs and clinical situations.
By Technology:
In terms of technology, the PIVC market is categorized into Conventional PIVC, Safety PIVC, Closed with Extension Set, Active PIVC with Blood Control, Passive PIVC with Blood Control, Active PIVC, and Passive PIVC. Conventional PIVCs remain prevalent due to their simplicity and cost-effectiveness. However, there is a growing shift towards Safety PIVCs, which are designed to reduce the risk of needlestick injuries and enhance user safety. Closed systems with extension sets are gaining traction for their ability to reduce infection risks and improve handling during catheterization. Active and Passive PIVCs with blood control features are particularly important in preventing blood exposure and ensuring a cleaner insertion process. These advanced technologies are increasingly favored in modern healthcare settings where patient safety and infection control are paramount. The evolution of PIVC technology reflects the market's focus on enhancing clinical outcomes, reducing complications, and improving the overall patient experience.
Segments:
Based on Product Type:
- Short Peripheral IV Catheter
- Ported PIVC
- Non-Ported PIVC
- Integrated/Closed PIVC
- Closed with Extension Sets
- Closed PIVC
Based on Technology:
- Conventional PIVC
- Safety PIVC
- Closed with Extension Set
- Active PIVC with Blood Control
- Passive PIVC with Blood Control
- Active PIVC
- Passive PIVC
Based on End User:
- Hospitals
- Ambulatory Surgical Centers (ASCs)
- Clinics
- Home Use
- Others
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America holds a significant share of the Peripheral Intravenous Catheter (PIVC) Market, accounting for approximately 35% of the global market. This dominance is driven by the region's advanced healthcare infrastructure, high adoption rates of innovative medical technologies, and a strong focus on patient safety. The United States, in particular, plays a crucial role in this market, with its well-established healthcare system and high prevalence of chronic diseases that require frequent intravenous therapies. For instance, the growing trend of home healthcare and outpatient services has led to an increased use of peripheral IV catheters outside traditional hospital settings. The presence of major market players in North America further strengthens the region's position, as these companies invest heavily in research and development to introduce new and improved PIVC products. Additionally, the increasing geriatric population in the region, coupled with rising healthcare spending, continues to drive the demand for PIVCs.
Europe
Europe follows closely, with around 30% of the global PIVC market share. The market in this region is characterized by a strong emphasis on healthcare quality and patient safety, leading to widespread adoption of advanced PIVC technologies. Countries such as Germany, the United Kingdom, and France are at the forefront of this growth, driven by their robust healthcare systems and high standards of medical care. The European market also benefits from stringent regulatory frameworks that ensure the safety and efficacy of medical devices, including PIVCs. Additionally, the rising prevalence of chronic diseases and the growing aging population in Europe are key factors contributing to the increased use of PIVCs. The region's focus on infection prevention and the adoption of closed and safety PIVCs further highlight its commitment to enhancing patient outcomes and reducing healthcare-associated complications.
Key Player Analysis
- Terumo Corporation
- R. Bard, Inc.
- Teleflex Incorporated
- Braun Melsungen AG
- Argon Medical Devices, Inc.
- Venner Medical
- Vygon
- Smiths Group plc.
- NIPRO Medical Corporation
- Becton, Dickinson, and Company
Competitive Analysis
The competitive landscape of the Peripheral Intravenous Catheter (PIVC) Market is characterized by intense rivalry among leading players such as Terumo Corporation, B. Braun Melsungen AG, Teleflex Incorporated, Becton, Dickinson, and Company, and Smiths Group plc. These companies are heavily investing in research and development to innovate and enhance their product offerings, focusing on improving patient safety, reducing infection risks, and increasing catheter durability. They are also expanding their global reach through strategic acquisitions, partnerships, and the introduction of advanced PIVC technologies tailored to meet diverse healthcare needs. The competition is further intensified by the push for compliance with stringent regulatory standards, which drives continuous innovation in product design and functionality. These market leaders maintain their competitive edge by offering a wide range of PIVC products that cater to both developed and emerging markets, ensuring they meet the varying demands of healthcare providers worldwide.
Recent Developments
- In March 2024, BD initiated an international study to assess the safety and effectiveness of the BD Vascular Covered Stent for the treatment of Peripheral Arterial Disease.
- In December 2023, Terumo launched the AZUR HydroPack™ Peripheral Coil System.
- In December 2023, Teleflex was awarded the Peripheral Access purchasing agreement with Premier, Inc.
- In February 2023, Teleflex announced the release of two new catheters: the U.S. Food and Drug Administration (FDA) 510 (k) clearance of the Triumph™ Catheter, and the first clinical use of GuideLiner ® Coast™ Catheter.
- In July 2024, Nipro Medical Corporation announced a significant expansion in the United States with the establishment of its first North American manufacturing facility in Greenville, North Carolina.
Market Concentration & Characteristics
The Peripheral Intravenous Catheter (PIVC) Market exhibits a moderate to high level of market concentration, with a few key players dominating a significant portion of the market. Companies such as Becton, Dickinson, and Company, B. Braun Melsungen AG, and Teleflex Incorporated lead the industry, benefiting from their extensive product portfolios, strong brand recognition, and global distribution networks. These market leaders are characterized by their continuous investment in research and development, which drives innovation and the introduction of advanced PIVC technologies. Despite the dominance of these major players, the market also features a range of smaller companies that cater to niche segments, offering specialized products and solutions. The competitive dynamics are shaped by ongoing technological advancements, regulatory compliance, and a growing emphasis on patient safety and infection control. As the demand for high-quality, reliable PIVCs continues to rise, market concentration is likely to remain centered around these leading firms, with opportunities for growth and differentiation in emerging markets.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Technology, End User and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market is expected to grow steadily due to the increasing prevalence of chronic diseases requiring frequent intravenous therapy.
- Advancements in PIVC technology will continue to enhance patient safety and reduce the risk of complications.
- The shift towards home healthcare will drive demand for user-friendly PIVCs suitable for at-home treatments.
- Increased focus on infection prevention will lead to the development of more advanced closed and safety PIVC systems.
- Emerging markets will present significant growth opportunities as healthcare infrastructure expands.
- Regulatory requirements will become more stringent, pushing manufacturers to innovate and ensure compliance.
- Integration of smart technology into PIVCs will enable real-time monitoring and improve patient outcomes.
- The aging global population will contribute to sustained demand for PIVCs, particularly in developed regions.
- Cost-effectiveness and sustainability will be key factors influencing PIVC design and material choices.
- Competitive pressures will drive further consolidation and strategic partnerships within the market.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Peripheral Intravenous Catheter Market?
What factors are driving the growth of the Peripheral Intravenous Catheter Market?
What are the key segments within the Peripheral Intravenous Catheter Market?
What are some challenges faced by the Peripheral Intravenous Catheter Market?
Who are the major players in the Peripheral Intravenous Catheter Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Peripheral Intravenous Catheter Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Peripheral Intravenous Catheter Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 6,484.00 million → 2032: USD 11,224.28 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Peripheral Intravenous Catheter Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Peripheral Intravenous Catheter Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Peripheral Intravenous Catheter Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Peripheral Intravenous Catheter Market Drivers
- 3.3 Peripheral Intravenous Catheter Market Restraints & Challenges
- 3.4 Peripheral Intravenous Catheter Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Peripheral Intravenous Catheter Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Peripheral Intravenous Catheter Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Peripheral Intravenous Catheter category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Peripheral Intravenous Catheter Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Peripheral Intravenous Catheter Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Peripheral Intravenous Catheter market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Peripheral Intravenous Catheter Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Peripheral Intravenous Catheter Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Peripheral Intravenous Catheter Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Peripheral Intravenous Catheter (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Peripheral Intravenous Catheter Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Peripheral Intravenous Catheter Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Peripheral Intravenous Catheter Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Peripheral Intravenous Catheter Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Peripheral Intravenous Catheter Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Peripheral Intravenous Catheter Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Peripheral Intravenous Catheter Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Peripheral Intravenous Catheter Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Peripheral Intravenous Catheter Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
