
Pet Food and Supplements Market Overview:
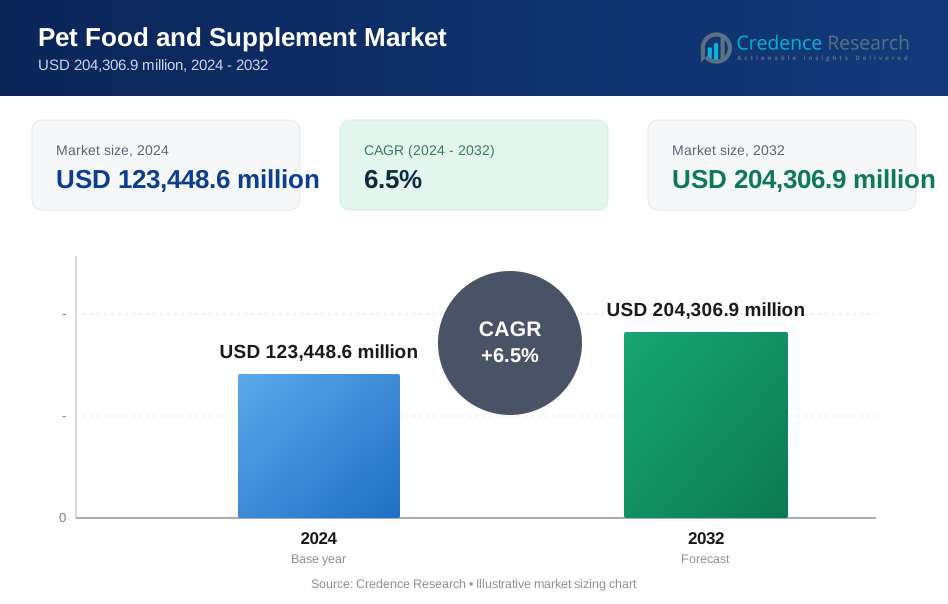
The Pet Food and Supplements Market size was valued at USD 123,448.6 million in 2024 and is anticipated to reach USD 204,306.9 million by 2032, at a CAGR of 6.5% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Pet Food and Supplements Market Size 2024 | USD 123,448.6 million |
| Pet Food and Supplements Market, CAGR | 6.5% |
| Pet Food and Supplements Market Size 2032 | USD 204,306.9 million |
Top players in the pet food and supplements market include Mars Petcare, Nestlé Purina Petcare, Hill’s Pet Nutrition, Blue Buffalo, and The J.M. Smucker Company. These companies lead due to strong global distribution, product innovation, and trusted brand equity. Zesty Paws and Virbac expand rapidly in the supplement space with specialized health-focused formulations. Wellness Pet Food, Champion Petfoods, and Diamond Pet Foods compete through natural and organic offerings targeting premium buyers. North America remains the leading region, holding a 35% market share in 2024, driven by high pet ownership, premiumization, and strong e-commerce penetration. Europe and Asia Pacific follow as key growth regions.

Pet Food and Supplements Market Insights
- The pet food and supplements market was valued at USD 123,448.6 million in 2024 and is projected to reach USD 204,306.9 million by 2032, growing at a CAGR of 6.5%.
- Rising pet humanization, growing awareness of preventive care, and increasing demand for premium, organic, and functional nutrition drive market growth across all product categories.
- Multivitamins lead the application segment with over 30% share, while dogs dominate the pet segment with more than 40% share due to high spending on canine wellness.
- The market is dominated by key players such as Mars Petcare, Nestlé Purina Petcare, Hill’s Pet Nutrition, and Blue Buffalo, with emerging brands gaining traction in supplements and organic offerings.
- North America leads with 35% of the market, followed by Europe at 27% and Asia Pacific at 21%; however, regulatory inconsistency and price sensitivity in developing regions continue to restrain broader market penetration.
Pet Food and Supplements Market Segmentation Analysis:
By Pet
The dog segment dominates the pet food and supplements market, accounting for over 40% of the total share in 2024. High spending on canine health, preventive care, and functional nutrition drives demand. Dog owners actively purchase tailored products targeting joint support, digestion, and immunity. Cats follow due to growing adoption in urban households and rising focus on feline-specific nutrition. Freshwater fish and other small pets contribute marginally but see steady demand from niche communities. Aquatic pet food and supplements benefit from increasing interest in ornamental fish care.
- For instance, Mars Petcare and Nestlé Purina together lead the global pet food industry, with Mars alone controlling about 38.9% of the dog food economy dry category and Nestlé Purina holding about 33.2% (economy dry dog food data).
By Application
Multivitamins hold the largest market share at over 30%, supported by their broad health appeal and daily-use nature. Consumers view them as foundational supplements for immunity, metabolism, and longevity. Skin & coat and hip & joint categories also gain traction, especially among aging pets and premium segments. Prebiotics & probiotics see rising demand due to gastrointestinal health awareness and vet endorsements. Calming supplements grow in popularity amid urban stressors and travel-related anxiety. The "others" category includes condition-specific products, contributing to expanding product diversity.
- For instance, multivitamin supplements deliver key vitamins A, B, C, D, and E to support overall wellness in pets (supplement functions).
By Source
Conventional products lead the market with more than 65% share in 2024 due to affordability and widespread availability. Mass-market brands prefer conventional sourcing for volume efficiency and broader consumer reach. However, organic pet food and supplements are growing rapidly, driven by pet humanization and owner preference for clean-label ingredients. Urban and affluent buyers increasingly shift toward organic due to perceived safety, sustainability, and premium value. Certifications and transparent sourcing continue to influence brand loyalty in this segment.
Pet Food and Supplements Market Key Growth Drivers
Rising Pet Humanization and Premiumization
The growing trend of pet humanization significantly drives the pet food and supplements market. Pet owners increasingly treat animals as family members, leading to a surge in spending on high-quality food and wellness products. Premium formulations that support immunity, digestion, skin, and joint health see strong adoption. Consumers prioritize functional ingredients like omega fatty acids, probiotics, and multivitamins, mirroring human health trends. This shift has pushed brands to expand clean-label, organic, and breed-specific offerings. Urbanization and smaller households have further reinforced emotional bonds with pets, boosting demand for customized nutrition. Social media and digital marketing amplify awareness, while influencer-led campaigns create trust and visibility. Overall, premiumization aligns with growing disposable income and the willingness to invest in long-term pet health.
- For instance, North America accounted for nearly half of global pet supplement demand in 2024, reflecting high spending on premium pet care products
Expanding Veterinary Recommendations and Awareness Campaigns
Veterinary endorsements play a vital role in shaping pet owner decisions, particularly for supplements. Clinics and pet hospitals promote nutritional interventions for chronic issues such as arthritis, digestive disorders, and anxiety. Veterinarians also advocate supplements for preventive care, especially among aging pets or those with breed-specific vulnerabilities. These professional endorsements boost consumer confidence and drive product credibility. At the same time, pet wellness awareness campaigns by brands and non-profits educate owners on the importance of nutrition beyond food. Online platforms, retail stores, and vet clinics serve as key education channels. This dual impact of trusted professional guidance and widespread informational outreach increases product trials and long-term adoption, significantly fueling market expansion.
- For instance, leading companies like Nestlé Purina launched veterinarian‑recommended supplement lines to strengthen product credibility in 2024.
Growth of E-Commerce and Direct-to-Consumer Channels
E-commerce and direct-to-consumer (DTC) models are transforming the pet food and supplements landscape. Online platforms offer a wide product range, subscription models, and doorstep convenience, which appeals to time-pressed urban consumers. Digital-first brands focus on personalization through data-driven recommendations and targeted marketing. Enhanced logistics, especially in Tier-1 and Tier-2 cities, enable timely delivery of specialized products. Influencer marketing, product reviews, and bundled subscription plans foster customer retention and repeat purchases. E-commerce also bridges gaps in availability of niche or premium products in physical stores. The rise of mobile commerce and loyalty programs further drives growth in online pet care retail. This trend strengthens brand-customer relationships and accelerates market reach across wider geographies.
Pet Food and Supplements Market Key Trends & Opportunities
Surge in Demand for Natural and Functional Ingredients
Natural, organic, and functional pet supplements are seeing notable growth due to increased scrutiny over ingredient safety. Pet owners seek products free from artificial additives, fillers, or synthetic preservatives. Functional ingredients like turmeric, CBD, glucosamine, and collagen gain popularity for targeted benefits. Clean-label transparency and sustainability claims resonate with health-conscious buyers. Brands that highlight sourcing traceability and science-backed efficacy are gaining trust and shelf space. This trend offers growth opportunities for companies developing organic formulations, limited-ingredient diets, or supplements tailored for life stages. Expansion into grain-free, allergen-free, and holistic nutrition segments aligns with evolving consumer expectations and regulatory shifts toward ingredient clarity.
- For instance, plant‑derived dietary additives featuring bioactive compounds are increasingly adopted in companion animal nutrition for physiological health support.
Personalization and Tech-Enabled Pet Nutrition
Personalized pet nutrition is emerging as a major opportunity in the market. Brands now offer supplements and meals tailored to a pet’s breed, age, weight, activity level, and medical history. DNA-based nutrition and gut microbiome testing enable more accurate product recommendations. Smart devices and apps track consumption patterns, activity, and health metrics, creating data-driven diet plans. This integration of tech into pet wellness enhances engagement and loyalty. Pet subscription services further strengthen personalization through recurring delivery and adaptive formulation options. The trend aligns with consumer desire for proactive, customized care and presents opportunities for innovation in product design, diagnostics, and digital platforms.
Pet Food and Supplements Market Key Challenges
Regulatory Complexity and Lack of Global Standardization
The pet food and supplement industry faces regulatory inconsistency across regions. Unlike human dietary supplements, pet products often lack harmonized standards for safety, labeling, and health claims. Some countries treat supplements as feed additives, while others categorize them under veterinary products, leading to unclear compliance paths. This lack of standardization complicates global expansion and delays product launches. Smaller brands face high compliance costs and approval delays, which limits market entry. Moreover, differing ingredient approval lists and testing protocols challenge formulation and marketing strategies. Regulatory gaps also allow low-quality or misleading products to enter the market, risking consumer trust.
Price Sensitivity and Limited Penetration in Emerging Markets
Despite rising awareness, price remains a major barrier in many developing countries. Premium pet supplements often cost more than standard pet food, which deters mass adoption in price-sensitive segments. Limited availability of veterinary guidance and poor retail penetration in rural or semi-urban areas further slows growth. Cultural factors may also reduce perceived need for specialized pet nutrition. In these markets, local brands with low-cost, generic products dominate, restricting growth opportunities for premium or niche global players. Overcoming this challenge requires tailored pricing strategies, awareness campaigns, and localized product development to match income levels and regional preferences.
Pet Food and Supplements Market Regional Analysis
North America
North America leads the pet food and supplements market with over 35% share in 2024. The region benefits from high pet ownership, rising disposable income, and strong demand for premium and organic products. The United States drives growth with advanced veterinary infrastructure, widespread e-commerce adoption, and increased focus on pet wellness. Consumers prioritize functional and breed-specific formulations. Canada follows with steady market expansion supported by regulatory clarity and specialty retail chains. High awareness and established brands dominate the competitive landscape, while innovation in personalization and subscription-based delivery models further strengthens North America's market leadership.
Europe
Europe holds around 27% of the global market share, driven by strict animal welfare regulations and a strong focus on pet nutrition. Countries such as Germany, the UK, and France lead adoption of natural and functional supplements. The region also sees growing demand for organic and sustainability-labeled products. Pet humanization continues to shape product preferences, especially in urban areas. Retailers expand offerings through online platforms and private-label solutions. Regulatory harmonization across the EU enhances market consistency, encouraging innovation and cross-border trade. Europe remains a mature but evolving market with increasing emphasis on ethical sourcing and health-driven formulations.
Asia Pacific
Asia Pacific accounts for approximately 21% of the pet food and supplements market, showing the fastest growth rate globally. Rising pet adoption in urban centers across China, Japan, South Korea, and India fuels demand. Changing lifestyles and growing middle-class populations support spending on premium and imported products. Japan leads in advanced pet care services, while China’s e-commerce boom accelerates product access and awareness. Emerging markets such as India see growth in both conventional and herbal supplement categories. Local and global brands expand aggressively through digital channels and retail partnerships, making Asia Pacific a key growth frontier.
Latin America
Latin America captures nearly 10% market share, supported by growing urbanization and increasing awareness of pet nutrition. Brazil and Mexico are the leading markets, with rising demand for functional and fortified products. The region’s improving veterinary services and expanding middle class contribute to higher supplement adoption. Online retail and specialty pet stores enhance availability of premium offerings. However, price sensitivity remains a challenge, and local brands often dominate due to affordability. Educational initiatives and veterinary partnerships are essential to improve product understanding and drive growth in both urban and semi-urban areas across Latin America.
Middle East & Africa (MEA)
The Middle East & Africa region holds around 7% market share, with steady growth driven by rising pet adoption and expanding retail infrastructure. Gulf countries such as the UAE and Saudi Arabia lead regional demand, supported by high-income households and increasing pet wellness awareness. Pet food and supplements gain traction in premium retail channels, while local distribution partnerships improve product access. In Africa, market penetration is still low due to limited awareness and high price sensitivity. However, growth opportunities exist in urban centers with expanding veterinary networks. MEA remains an emerging market with strong long-term potential.
Pet Food and Supplements Market Segmentations:
By Pet
- Dog
- Cat
- Freshwater Fish
- Others
By Application
- Multivitamins
- Skin & Coat
- Hip & Joint
- Prebiotics & Probiotics
- Calming
- Others
By Source
- Organic
- Conventional
By Distribution Channel
- Offline
- Online
By Food Type
- Wet Food
- Dry Food
- Snacks/Treats
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the pet food and supplements market is highly consolidated, with global players dominating due to strong brand recognition, diversified portfolios, and expansive distribution networks. Companies like Mars Petcare, Nestlé Purina Petcare, and Hill's Pet Nutrition lead the market through continuous product innovation, premium offerings, and strategic acquisitions. Mid-tier brands such as Blue Buffalo, Champion Petfoods, and Wellness Pet Food focus on natural, grain-free, and organic products to target health-conscious consumers. Supplement-focused firms like Zesty Paws and Virbac gain traction by offering condition-specific formulations supported by clinical research. Market participants leverage e-commerce, private labeling, and subscription models to strengthen customer retention. The rise of personalized nutrition and clean-label demand drives R&D investments across the board. Regional expansion, veterinary partnerships, and digital engagement strategies remain central to gaining competitive advantage. Overall, the market is evolving rapidly with innovation, transparency, and targeted wellness as key competitive parameters.
Key Player Analysis
- Blue Buffalo
- Zesty Paws
- Virbac
- Hill's Pet Nutrition
- Champion Petfoods
- Merrick Pet Care
- Ainsworth Pet Nutrition
- Spectrum Brands
- Wellness Pet Food
- Nutro Products
- Mars Petcare
- Big Heart Pet Brands
- The J.M. Smucker Company
- Nestlé Purina Petcare
- Diamond Pet Foods
Recent Developments
- In March 2025, Vegan Minerals, a supplier of sustainable nutrient solutions for human, pet, and plant health, announced the launch of its 100% plant-based, sustainable calcium ingredient Calcea. By providing this clean-label, plant-derived alternative to calcium, Vegan Minerals aims to redefine mineral nutrition. It has a natural honeycomb structure that touts superior absorption, according to the company. The ingredient is sourced from Lithothamnion, a calcified microalga, found off the coast of Brazil.
- In February 2025, Elanco Animal Health Incorporated announced the launch of Pet Protect, a line of veterinarian-formulated supplements for dogs and cats. Pet Protect emerges as a modernized, science-backed supplement line specifically designed to cater to the diverse health needs of pets. Bobby Modi, Executive Vice President, U.S. Pet Health and Global Digital Transformation, stated, "This underscores our dedication to enhancing the health and well-being of pets while driving growth and expanding our footprint in this dynamic market.
- In August 2024, Pet Honesty, the multiple award-winning, vet-recommended natural pet wellness brand, launched its latest format innovation: liquid supplements. This advanced collection includes Hip + Joint Health, Skin + Coat Health, and 10-in-1 Multivitamin, all formulated to address common pet wellness needs in a convenient, easy-to-dispense format, making meal time even tastier.
Report Coverage
The research report offers an in-depth analysis based on Pet, Application, Source, Distribution Channel, Food Type and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for personalized pet nutrition and breed-specific supplements will continue to rise.
- E-commerce and subscription-based delivery models will expand market access and retention.
- Organic and clean-label products will gain more traction among health-conscious pet owners.
- Companies will invest in R&D to develop functional supplements for targeted health conditions.
- Pet humanization will drive premium product purchases across urban and developed markets.
- Veterinary partnerships will strengthen product credibility and boost clinical-grade formulations.
- Asia Pacific will emerge as a key growth region with rising pet ownership and income levels.
- Smart devices and apps will enhance tracking of pet health and supplement usage.
- Sustainability in packaging and ingredient sourcing will become a priority for major brands.
- Market consolidation will increase through mergers, acquisitions, and regional expansion strategies.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Pet food and supplements market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Pet food and supplements market projected to grow between 2024 and 2032?
Which Pet food and supplements market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Pet food and supplements market?
Who are the leading companies in the Pet food and supplements market?
Which region commanded the largest share of the Pet food and supplements market in 2024?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Pet Food and Supplement Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Pet Food and Supplement Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 123,448.6 million → 2032: USD 204,306.9 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Pet Food and Supplement Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Pet Food and Supplement Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Pet Food and Supplement Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Pet Food and Supplement Market Drivers
- 3.3 Pet Food and Supplement Market Restraints & Challenges
- 3.4 Pet Food and Supplement Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Pet Food and Supplement Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Pet Food and Supplement Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Pet Food and Supplement category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Pet Food and Supplement Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Pet Food and Supplement Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Pet Food and Supplement market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Pet Food and Supplement Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Pet Food and Supplement Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Pet Food and Supplement Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Pet Food and Supplement (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Pet Food and Supplement Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Pet Food and Supplement Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Pet Food and Supplement Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Pet Food and Supplement Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Pet Food and Supplement Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Pet Food and Supplement Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Pet Food and Supplement Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Pet Food and Supplement Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Pet Food and Supplement Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
