
Market Overview:
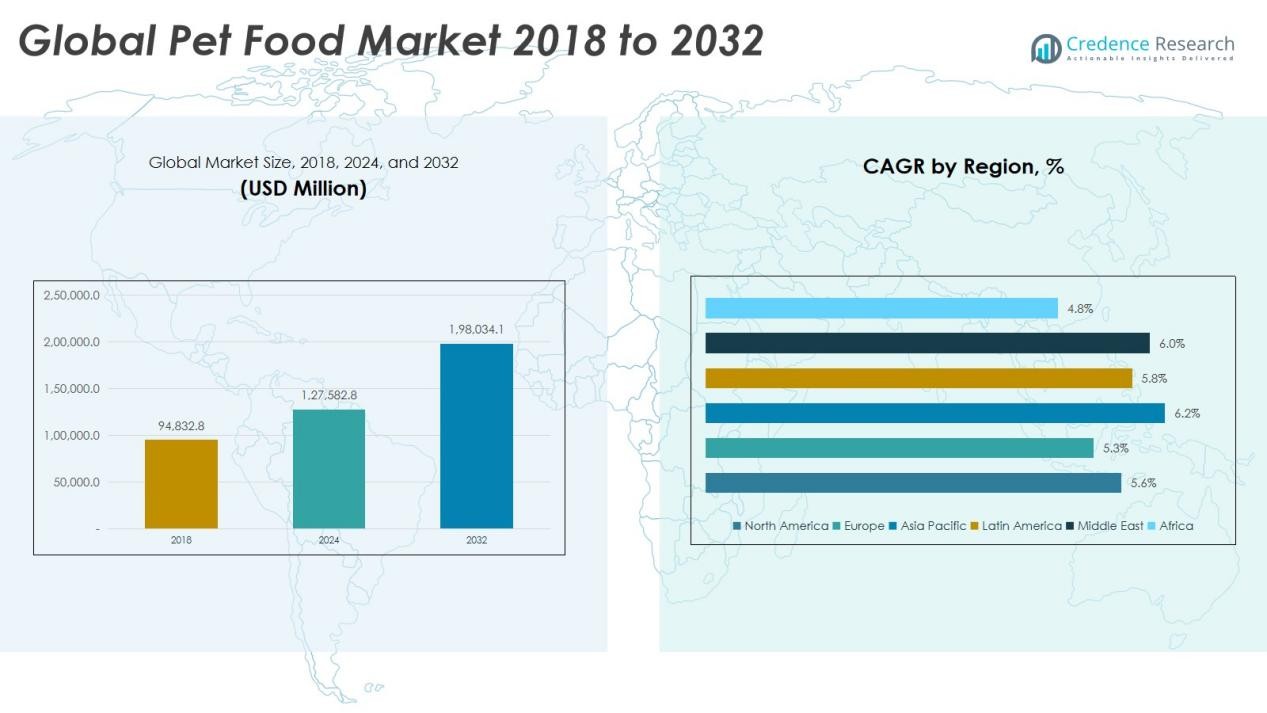
The Global Pet Food Market size was valued at USD 94,832.8 million in 2018 to USD 1,27,582.8 million in 2024 and is anticipated to reach USD 1,98,034.1 million by 2032, at a CAGR of 5.70% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Pet Food Market Size 2024 | USD 1,27,582.8 Million |
| Pet Food Market, CAGR | 5.70% |
| Pet Food Market Size 2032 | USD 1,98,034.1 Million |
Rising disposable incomes and urban lifestyles are driving demand for functional and natural ingredients in pet food formulations. The growing prevalence of obesity and chronic conditions in pets has also boosted interest in specialized diets that promote health and wellness. E-commerce growth and direct-to-consumer sales channels further enhance market accessibility and brand visibility.
North America dominated the global market in 2024, holding over 40% of the share due to strong pet ownership rates and high spending per pet. Europe followed with significant demand for sustainable and organic pet food products. The Asia Pacific region is expected to record the fastest growth, driven by increasing pet ownership, rapid urbanization, and rising awareness of pet care across China, India, and Southeast Asia.
Market Insights:
- The Global Pet Food Market was valued at USD 127,582.8 million in 2024 and is projected to reach USD 198,034.1 million by 2032, growing at a CAGR of 5.70%.
- Rising disposable incomes and urbanization are driving demand for functional, natural, and premium pet food products.
- North America held over 40% market share in 2024, supported by high pet ownership and advanced retail networks.
- Europe accounted for 28% share, with strong demand for sustainable, organic, and eco-friendly formulations.
- The Asia Pacific region, with a 22% share, is the fastest-growing market driven by increasing pet ownership in China and India.
- Key challenges include fluctuating raw material prices, supply chain disruptions, and stringent regulatory standards.
- Expanding e-commerce platforms, sustainable production practices, and personalized pet nutrition create strong future growth opportunities.
Market Drivers:
Rising Pet Humanization and Growing Focus on Pet Health
The Global Pet Food Market is driven by the growing perception of pets as family members. Pet owners increasingly demand high-quality, nutritious, and tailored food products that support pet health and wellness. This trend has fueled innovation in premium, organic, and functional food formulations. It encourages brands to invest in research to develop products with balanced nutrition, immunity support, and specific dietary benefits.
- For instance, Elanco launched Pet Protect in February 2025, a veterinarian-formulated supplement line backed by over 25 years of veterinary experience.
Increasing Disposable Income and Willingness to Spend on Premium Products
Rising household incomes have strengthened consumer spending on pet care, particularly in developed regions. Pet owners now prioritize quality over price, driving strong demand for premium, grain-free, and protein-rich diets. It has led to the expansion of specialty and customized food segments targeting breed-specific and age-specific needs. This shift supports strong revenue growth across urban and suburban markets worldwide.
- For instance, General Mills completed its acquisition of Whitebridge Pet Brands' North American business for $1.45 billion in late 2024, expanding its premium pet food portfolio with Tiki Pets and Cloud Star brands.
Expansion of E-commerce and Direct-to-Consumer Distribution Channels
The surge in digital retail platforms has transformed product accessibility and purchasing behavior in the pet food sector. Online marketplaces and brand websites offer convenience, product variety, and subscription options. It allows consumers to explore and compare nutrition profiles easily. Companies now leverage data analytics and targeted marketing to strengthen customer engagement and loyalty.
Growing Awareness of Sustainable and Ethical Production Practices
Consumers increasingly favor brands adopting sustainable sourcing, recyclable packaging, and cruelty-free production. The market reflects this shift through the introduction of eco-friendly packaging and plant-based protein options. It aligns with global sustainability goals and strengthens brand reputation. Companies investing in transparency and ethical supply chains continue to gain competitive advantages in the evolving pet food landscape.
Market Trends:
Shift Toward Functional, Natural, and Personalized Pet Nutrition
The Global Pet Food Market is witnessing a clear shift toward functional and natural formulations that address specific health concerns such as digestion, joint health, immunity, and weight management. Pet owners are increasingly drawn to ingredients with visible health benefits, including probiotics, omega fatty acids, and superfoods. Brands now emphasize transparency by disclosing ingredient sourcing and production practices. It encourages consumer trust and long-term loyalty. Personalized pet nutrition based on breed, age, and health data is also expanding rapidly. Companies are using digital platforms and subscription services to tailor meal plans, reflecting a strong alignment with human wellness trends.
- For Instance, Purina’s Pro Plan LiveClear cat food is the first formula clinically proven to reduce the major cat allergen (Fel d 1) on cat hair and dander, with studies showing an average reduction of 47% after three weeks of use.
Rise of Sustainability, Plant-Based Diets, and Technological Integration
Sustainability has become a defining trend across the global pet food supply chain. Companies are replacing animal-derived ingredients with plant-based or insect protein alternatives to reduce environmental impact. It supports eco-conscious consumers and aligns with the circular economy model. Technological innovation, including smart feeders, AI-based diet tracking, and precision formulation tools, is transforming product development and consumer interaction. The growing preference for sustainable packaging, recyclable materials, and ethically sourced raw inputs reinforces this movement. These advancements strengthen competitiveness and brand differentiation in a rapidly evolving marketplace.
- For Instance, Petnet's SmartFeeder device leveraged algorithms to automate and personalize meal schedules, aiming to support data-driven nutrition management, and the company went out of business by 2020 after shipping far fewer than 100,000 units and encountering widespread technical issues, including feeder jams and app failures.
Market Challenges Analysis:
Fluctuating Raw Material Costs and Supply Chain Disruptions
The Global Pet Food Market faces persistent challenges from volatile raw material prices and supply chain instability. Dependence on agricultural commodities such as meat, grains, and plant proteins exposes manufacturers to price fluctuations caused by climate change and trade disruptions. It pressures production margins and limits affordability for consumers. Logistical bottlenecks and rising transportation costs further affect product availability across regions. Companies are investing in local sourcing and alternative protein options to mitigate risks, but consistent supply remains difficult to maintain.
Regulatory Compliance and Product Safety Concerns
Strict international regulations on labeling, ingredient quality, and safety testing create hurdles for market expansion. The pet food sector must comply with varying regional standards, which increases production costs and slows product launches. It demands continuous monitoring of ingredients to ensure safety and traceability. Rising incidents of product recalls have increased consumer scrutiny of brand reliability. Small and medium producers face added pressure due to limited testing infrastructure. Regulatory harmonization remains essential for promoting trust and facilitating smoother global trade.
Market Opportunities:
Expansion in Emerging Markets and Growing Pet Ownership Rates
The Global Pet Food Market offers strong growth potential in emerging economies where pet ownership is rapidly increasing. Rising urbanization, income growth, and exposure to global pet care trends are fueling higher spending on premium and functional pet foods. It enables global brands to expand into untapped regions across Asia Pacific, Latin America, and the Middle East. Local manufacturers are also scaling operations to meet demand with affordable, region-specific formulations. Expanding distribution networks and e-commerce adoption further support accessibility and market penetration.
Innovation in Product Formulation and Sustainable Solutions
Continuous innovation in ingredients and packaging presents major opportunities for differentiation and brand value creation. Companies are investing in plant-based proteins, clean-label products, and specialized diets that address pet allergies or health conditions. It allows brands to attract environmentally conscious consumers seeking transparency and ethical sourcing. Sustainable packaging solutions, including biodegradable or recyclable materials, enhance corporate responsibility and appeal. Partnerships with veterinary professionals and technology firms also open new avenues for product personalization and precision nutrition.
Market Segmentation Analysis:
By Food Type
Dry food leads the Global Pet Food Market due to its convenience, cost-effectiveness, and long shelf life. Wet and canned food follow, offering higher palatability and hydration benefits for pets. Treats and snacks are gaining popularity as owners focus on pet indulgence and training rewards. It continues to expand across specialty diets such as grain-free, high-protein, and functional formulations tailored for health management.
- For Instance, Nestlé Purina is increasing wet pet food production at its Wisbech, UK plant with a £150 million investment announced in September 2024 to expand capacity and efficiency.
By Source
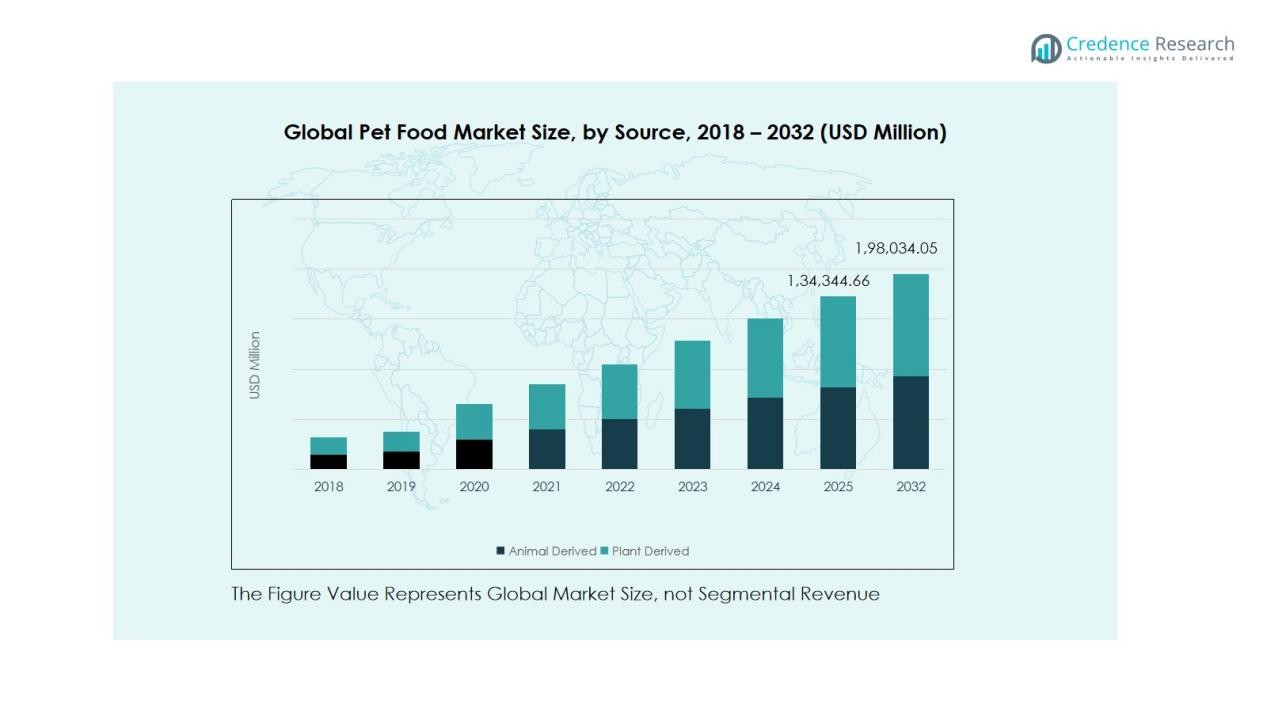
Animal-derived ingredients dominate because of their protein density and taste appeal. Plant-based and novel protein sources are growing fast, driven by sustainability awareness and pet allergies. Organic and natural ingredient-based formulations are expanding across premium categories, supported by owner preference for clean-label products. It reflects a clear market shift toward transparency, ethical sourcing, and nutritional innovation.
- For instance, Castor & Pollux’s ORGANIX line achieved USDA Organic certification for its recipes, with their Organic Chicken & Sweet Potato recipe comprising 95% certified organic ingredients, meeting strict organic production standards.
By Pet Type
Dog food holds the largest market share due to strong ownership rates and premium product adoption. Cat food follows, driven by demand for tailored nutrition in urban households. Products for other pets such as birds, fish, and small mammals represent a smaller but growing segment. It gains traction through niche innovations, customized diets, and fortified formulations promoting health and longevity.
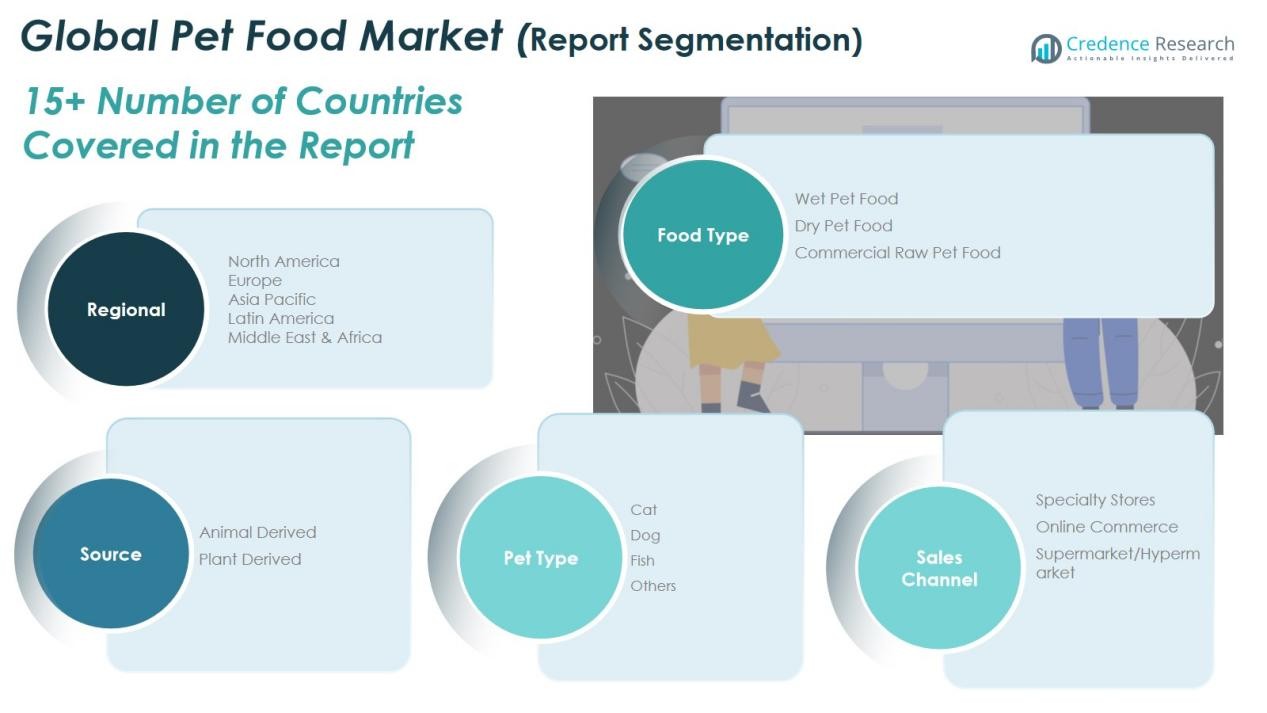
Segmentations:
By Food Type
- Wet Pet Food
- Dry Pet Food
- Commercial Raw Pet Food
By Source
- Animal Derived
- Plant Derived
By Pet Type
- Cat
- Dog
- Fish
- Others
By Sales Channel
- Specialty Stores
- Online Commerce
- Supermarket/Hypermarket
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America:
The North America Pet Food Market size was valued at USD 32,356.96 million in 2018, increased to USD 43,405.48 million in 2024, and is anticipated to reach USD 67,113.74 million by 2032, at a CAGR of 5.6% during the forecast period. North America accounted for a 34% share of the Global Pet Food Market, supported by high pet ownership and advanced retail networks. The region is driven by strong consumer preference for premium, organic, and functional products. It benefits from established brands like Mars, Nestlé Purina, and Hill’s Pet Nutrition, which dominate through innovation and wide distribution. The United States remains the key contributor, driven by high disposable income and strong awareness of pet nutrition. E-commerce and subscription-based services continue to enhance accessibility and convenience for pet owners.
Europe
The Europe Pet Food Market size was valued at USD 27,074.77 million in 2018, increased to USD 35,577.37 million in 2024, and is anticipated to reach USD 53,469.19 million by 2032, at a CAGR of 5.3% during the forecast period. Europe held a 28% share of the Global Pet Food Market, supported by a strong demand for sustainable and organic formulations. The region is characterized by strict food safety and labeling regulations that ensure high product quality. It benefits from growing consumer focus on eco-friendly packaging and ethical ingredient sourcing. The United Kingdom, Germany, and France lead consumption due to rising urban pet ownership and demand for health-specific food products. Private-label brands and e-commerce growth further support competitive expansion across the region.
Asia Pacific
The Asia Pacific Pet Food Market size was valued at USD 20,768.39 million in 2018, increased to USD 28,848.29 million in 2024, and is anticipated to reach USD 46,656.82 million by 2032, at a CAGR of 6.2% during the forecast period. Asia Pacific captured a 22% share of the Global Pet Food Market, emerging as the fastest-growing regional segment. Rising urbanization, expanding middle-class income, and growing awareness of pet health drive regional growth. China, Japan, and India lead demand with increasing pet adoption rates and evolving dietary preferences. It benefits from strong online retail growth and localized manufacturing efforts. Global brands are entering partnerships with regional players to expand their reach and adapt product offerings to local tastes.
Latin America
The Latin America Pet Food Market size was valued at USD 8,307.35 million in 2018, increased to USD 11,236.40 million in 2024, and is anticipated to reach USD 17,565.62 million by 2032, at a CAGR of 5.8% during the forecast period. Latin America represented a 9% share of the Global Pet Food Market, with strong consumption in Brazil, Mexico, and Argentina. The region is driven by growing awareness of pet health and the availability of affordable premium products. It benefits from expanding modern retail formats and improved online accessibility. Regional manufacturers are offering fortified and cost-effective formulations to attract value-focused consumers. Government initiatives supporting animal welfare and veterinary care are boosting market confidence and long-term growth potential.
Middle East
The Middle East Pet Food Market size was valued at USD 4,533.01 million in 2018, increased to USD 6,218.75 million in 2024, and is anticipated to reach USD 9,901.70 million by 2032, at a CAGR of 6.0% during the forecast period. The Middle East held a 5% share of the Global Pet Food Market, supported by rising pet ownership and disposable income. The region’s demand is concentrated in the UAE, Saudi Arabia, and Qatar, where consumers prefer premium imported brands. It benefits from expanding retail channels and greater access to specialized pet stores. Functional and grain-free formulations are gaining popularity among health-conscious consumers. Market players are focusing on online sales and product education to build consumer trust and awareness.
Africa
The Africa Pet Food Market size was valued at USD 1,792.34 million in 2018, increased to USD 2,296.49 million in 2024, and is anticipated to reach USD 3,326.97 million by 2032, at a CAGR of 4.8% during the forecast period. Africa accounted for a 2% share of the Global Pet Food Market, remaining in an early growth stage. Rising urbanization and growing middle-income households are driving gradual adoption of packaged pet food. South Africa leads regional demand due to higher awareness of pet nutrition and established retail structures. It faces challenges related to limited manufacturing capacity and import dependency. Market expansion efforts center on affordability, localized production, and consumer education to sustain long-term development.
Key Player Analysis:
- The Hartz Mountain Corporation
- Mars, Incorporated
- Nestlé Purina PetCare
- Hill’s Pet Nutrition
- General Mills, Inc.
- M. Smucker Co.
- United Petfood
- Simmons Pet Food
- Unicharm Corporation
- Real Pet Food Co.
- Delicious Food Factory (DFF)
- Other Key Players
Competitive Analysis:
The Global Pet Food Market is highly competitive, with global and regional players focusing on innovation and product quality. Leading companies such as The Hartz Mountain Corporation, Mars, Incorporated, Nestlé Purina PetCare, Hill’s Pet Nutrition, General Mills, Inc., J.M. Smucker Co., United Petfood, and Simmons Pet Food dominate through extensive portfolios and strong brand equity. It emphasizes nutritional advancements, sustainable sourcing, and premiumization to strengthen market presence. Companies invest in research, digital marketing, and e-commerce platforms to expand consumer reach and brand loyalty. Regional manufacturers focus on affordability, private-label production, and local ingredient sourcing to compete effectively with multinational corporations. The industry continues to witness consolidation through acquisitions and partnerships aimed at expanding production capacity, improving supply chains, and enhancing formulation diversity.
Recent Developments:
- In February 2025, Hill’s Pet Nutrition, through Colgate-Palmolive, agreed to acquire Care TopCo Pty Ltd, owner of the Prime100 fresh pet food brand, to expand its presence in Australia’s fresh pet food market.
- In January 2025, J.M. Smucker Co. announced an agreement to divest Cloverhill, Big Texas, and select private label brands to JTM Foods LLC for $40 million, shifting ownership of trademarks and its Chicago production facility.
Report Coverage:
The research report offers an in-depth analysis based on Food Type, Source, Pet Type, Sales Channel and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The Global Pet Food Market will continue expanding with rising pet adoption and humanization trends.
- Demand for organic, functional, and health-oriented pet food will strengthen across global markets.
- Emerging regions such as Asia Pacific and Latin America will lead future growth through urbanization and higher incomes.
- Personalization in pet nutrition and AI-driven feeding technologies will transform product development.
- E-commerce growth and subscription models will enhance consumer convenience and retention.
- Sustainability will remain central, driving innovation in recyclable packaging and ethical ingredient sourcing.
- Manufacturers will diversify protein sources, focusing on plant-based, insect-based, and lab-grown alternatives.
- Global players will pursue acquisitions and collaborations to expand their distribution and product portfolios.
- Regulatory tightening around labeling, safety, and nutrition standards will improve quality and consumer trust.
- Investment in research, smart feeding devices, and precision nutrition will shape the industry’s next growth phase.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for the Global Pet Food Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Global Pet Food Market projected to grow between 2024 and 2032?
Which Global Pet Food Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Global Pet Food Market?
Who are the leading companies in the Global Pet Food Market?
Which region commanded the largest share of the Global Pet Food Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 127,582.8 million → 2032: USD 198,034.1 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Pet Food Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Pet Food Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Pet Food Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Pet Food Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Pet Food Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Pet Food Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Pet Food Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Pet Food Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 127,582.8 million → 2032: USD 198,034.1 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Pet Food Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Pet Food Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Pet Food Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Pet Food Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

