
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
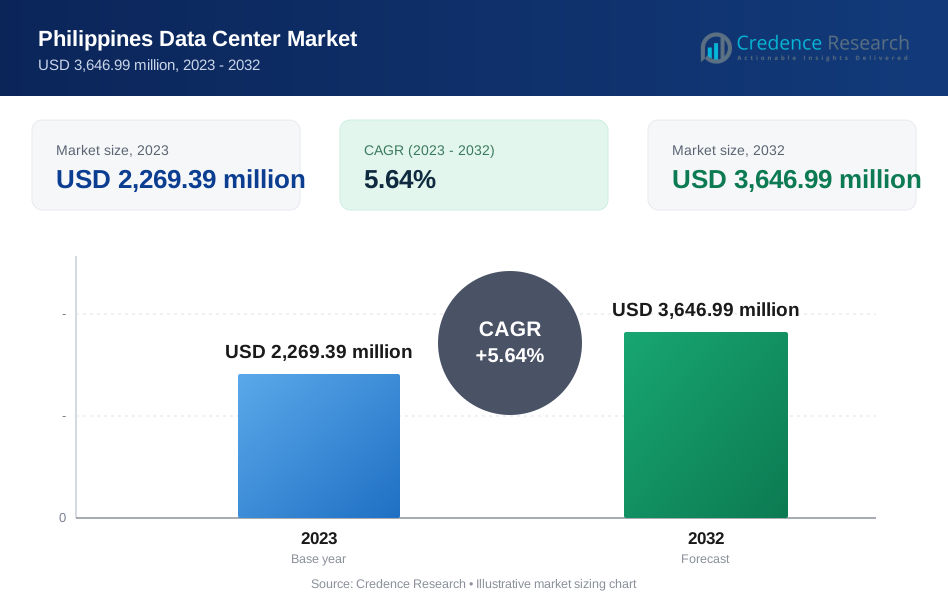
| Philippines Data Center Market Size 2023 | USD 2,269.39 Million |
| Philippines Data Center Market, CAGR | 5.64% |
| Philippines Data Center Market Size 2032 | USD 3,646.99 Million |
Market Overview
The Philippines data center market is projected to grow from USD 2,269.39 million in 2023 to an estimated USD 3,646.99 million by 2032, with a compound annual growth rate (CAGR) of 5.64% from 2024 to 2032. This significant growth is driven by the increasing demand for cloud services, data storage, and the rise of digital transformation across various sectors.
The market is primarily driven by the rapid digitalization of businesses, the growing adoption of cloud computing, and the rising need for disaster recovery and business continuity solutions. Additionally, government initiatives promoting the IT sector and the influx of investments from global tech giants are fueling market growth. Trends such as the increasing focus on sustainability and energy-efficient data centers are also influencing the market landscape.
Geographically, Metro Manila dominates the Philippines data center market, owing to its status as the country's primary business and financial hub. Other regions like Cebu and Davao are also emerging as key locations due to infrastructure development and strategic investments. Key players in the market include PLDT, Globe Telecom, ePLDT, Converge ICT Solutions, and NTT Communications, all of whom are actively expanding their data center capacities to meet the growing demand.
Market Drivers
Rapid Digital Transformation and Cloud Adoption
The Philippines is experiencing rapid digital transformation across industries, driving significant demand for data center services. According to a recent survey by the Department of Information and Communications Technology (DICT), a majority of Philippine businesses have accelerated their digital transformation initiatives in the past two years. The survey found that cloud adoption is a key priority, with many organizations migrating core business applications and data to the cloud. For instance, a study by a major cloud provider revealed that financial services, retail, and manufacturing sectors in the Philippines are leading cloud adoption. The COVID-19 pandemic has further catalyzed this trend, with companies rapidly transitioning to remote work and online services. A report by a global consulting firm highlighted that Philippine businesses across various sectors significantly increased their IT budgets for cloud migration and digital transformation projects. This shift is driving demand for data centers that can support cloud services, storage, and data processing. Major cloud providers are expanding their presence in the country, with several announcing plans to establish cloud regions in the Philippines. This growing cloud ecosystem is a key driver for data center investments, as providers seek to enhance local infrastructure to meet the rising demand for cloud and digital services.
Government Initiatives and Regulatory Support
The Philippine government has implemented several initiatives to support the growth of the data center market. The National Broadband Plan, spearheaded by the DICT, aims to improve internet connectivity nationwide. A progress report on the plan indicates significant advancements in fiber optic network deployment and increased internet speeds in many regions. The government has also established special economic zones focused on IT and data center development. For example, the Clark Freeport Zone has attracted several data center projects due to its strategic location and incentives. The Board of Investments (BOI) has included data centers in its Investment Priorities Plan, offering tax incentives for qualified projects. A recent BOI report shows an increase in approved data center investments, highlighting the effectiveness of these incentives. The government's Digital Philippines strategy emphasizes the importance of digital infrastructure, including data centers, in achieving the country's economic goals. A survey by a global technology association found that IT executives in the Philippines view government support as a crucial factor in their decision to invest in local data center facilities. These initiatives have attracted interest from both local and international data center operators, with several announcing expansion plans in the country.
Growing Demand for Disaster Recovery and Business Continuity Solutions
The Philippines' vulnerability to natural disasters has heightened awareness of disaster recovery and business continuity planning. A survey conducted by a leading IT services provider revealed that a significant number of Philippine businesses have experienced data loss or downtime due to natural disasters in recent years. This has led to increased demand for data centers offering robust disaster recovery solutions. For instance, a major telecommunications company reported a surge in inquiries for their disaster recovery services following recent typhoons. The Philippine Disaster Risk Reduction and Management Council has emphasized the importance of data resilience in its national strategy, encouraging businesses to invest in reliable backup and recovery systems. A study by an international business continuity association found that Philippine companies are increasingly prioritizing investments in disaster recovery capabilities, with many seeking data center providers that offer comprehensive business continuity solutions. Several data center operators have responded to this demand by developing facilities in less disaster-prone areas and offering advanced disaster recovery services. For example, a leading data center provider recently launched a new facility designed to withstand severe natural disasters, featuring redundant power and cooling systems.
Rising Demand for Colocation and Managed Services
As the digital economy expands, more businesses are turning to colocation and managed services to meet their IT infrastructure needs. Colocation services, which involve leasing space in a data center for servers and other hardware, offer companies a cost-effective way to maintain their IT operations without the need to build and manage their own data centers. This model is particularly appealing to small and medium-sized enterprises (SMEs) that lack the resources to invest in large-scale data center facilities. The demand for colocation services in the Philippines is being driven by several factors, including the need for scalable IT infrastructure, the growing volume of data, and the increasing complexity of IT environments. Additionally, managed services, which include the outsourcing of IT management and operations to third-party providers, are gaining traction as businesses seek to focus on their core competencies while leaving the management of IT infrastructure to specialists. Managed services providers offer a range of solutions, including network management, security, and cloud services, all of which are critical for businesses operating in a digital-first environment. The rising demand for colocation and managed services is propelling the growth of the data center market in the Philippines, as providers expand their offerings to meet the diverse needs of their clients.
Market Trends
Expansion of Edge Computing and Regional Data Centers
A significant trend in the Philippines data center market is the expansion of edge computing and regional data centers. As digitalization spreads across the country, there's growing demand to process data closer to its source, reducing latency and improving service delivery. This is driving the growth of edge data centers - smaller facilities located near end-users. For instance, a recent industry survey found that a majority of IT decision-makers in the Philippines are planning to increase their investments in edge computing infrastructure. These edge facilities are crucial for supporting emerging technologies like IoT, AI, and 5G networks. Additionally, as digital adoption increases outside Metro Manila, there's rising demand for regional data centers. Government data shows a notable increase in data center projects in cities like Cebu and Davao. This decentralization is helping to create a more resilient and efficient data infrastructure across the Philippines. Industry experts predict this trend will continue, with several major data center operators announcing plans to expand their presence in key regional hubs over the next few years.
Growing Emphasis on Sustainability and Green Data Centers
Sustainability has become a key focus in the Philippines data center market. A recent survey by a leading environmental organization found that a significant portion of data center operators in the country are prioritizing green initiatives. This shift is driven by increasing awareness of climate change and the need for energy-efficient solutions. Data center operators are investing in technologies that reduce energy consumption and minimize carbon footprints. For instance, government reports indicate a substantial increase in the use of renewable energy sources like solar and wind power in data center facilities. Additionally, industry data shows a growing adoption of advanced cooling systems that reduce reliance on traditional, energy-intensive methods. The emphasis on green data centers is not only driven by regulatory pressures but also by client demand for environmentally responsible services. A survey of business leaders in the Philippines revealed that sustainability is becoming a key factor in choosing data center providers. As this trend continues, experts predict that green practices will become a standard feature rather than a differentiator in the Philippines data center market.
Market Restraints and Challenges
High Energy Costs and Limited Infrastructure
One of the primary restraints in the Philippines data center market is the high cost of energy and the limited availability of reliable infrastructure. For instance, a recent industry survey found that data center operators in the Philippines consistently rank energy costs as their top operational concern. The country's electricity rates are among the highest in Southeast Asia, significantly impacting data centers' operational expenses. Additionally, the power infrastructure's reliability is a major issue, with frequent outages reported by data center managers, especially outside major urban areas. A government study highlighted that many regions experience regular power fluctuations, forcing data centers to invest heavily in backup power systems. The reliance on fossil fuels for energy generation also complicates efforts to meet sustainability goals, with a industry association report noting that most data centers struggle to implement green initiatives due to limited renewable energy options. These infrastructure challenges not only increase operational risks but also deter potential investments. A recent economic impact assessment indicated that improved power infrastructure could substantially boost data center growth in the country.
Skills Shortage and Talent Retention
The Philippines data center market faces significant challenges related to the availability of skilled professionals and talent retention. A comprehensive workforce survey conducted by a leading IT industry association revealed a widening skills gap in critical areas such as network management, cybersecurity, and cloud computing. For instance, data center operators reported difficulties in filling specialized roles, with some positions remaining vacant for extended periods. The survey also highlighted that a substantial portion of IT graduates lack the specific skills required for modern data center operations. Furthermore, talent retention is a pressing issue, with a government labor report showing a high turnover rate in the IT sector as professionals seek opportunities abroad. This brain drain effect is particularly pronounced in the data center industry, where the demand for experienced professionals often outstrips local supply. A recent economic study emphasized that addressing this skills shortage is crucial for the sector's growth, suggesting that improved training programs and industry-academia partnerships could help bridge the gap and enhance the competitiveness of the Philippines data center market.
Market Segmentation Analysis
By Type
The Philippines data center market is segmented into various types, each catering to different business needs and technological requirements. Enterprise data centers continue to be a significant segment, primarily utilized by large organizations to manage their internal data and IT infrastructure. These facilities are often custom-built to meet specific organizational needs. Edge data centers are gaining prominence in the market, driven by the increasing demand for low-latency applications and the need to process data closer to the source. This trend is particularly evident in industries requiring real-time data processing, such as IoT and autonomous vehicles. Colocation facilities have become increasingly popular among businesses looking to scale their operations without significant capital expenditure. For instance, a survey conducted by a leading IT consultancy firm revealed that a growing number of small and medium enterprises in the Philippines are opting for colocation services to reduce operational costs and improve scalability. Hyperscale data centers are witnessing substantial growth, designed to accommodate the needs of large-scale cloud providers and tech giants. The Philippine government's initiatives to attract foreign investments in the tech sector have contributed to this growth. Managed data centers are also gaining traction, providing outsourced IT services that allow businesses to focus on their core operations. Modular data centers are emerging as a flexible solution, offering scalability for businesses with fluctuating demands.
By Component
The Philippines data center market is segmented by component into Hardware, Data Centre Infrastructure Management Software, and Services, each playing a crucial role in the overall ecosystem. The Hardware segment encompasses a wide range of equipment essential for data center operations, including power systems, cooling systems, racks, servers, and networking devices. A recent government survey highlighted the increasing adoption of energy-efficient hardware components in data centers across the country, aligning with global sustainability trends. Data Centre Infrastructure Management Software (DCIM) is divided into cloud-based and on-premises solutions. Cloud-based DCIM is gaining popularity due to its scalability and ease of deployment, with a notable increase in adoption among small and medium-sized enterprises. The Services segment is further categorized into Professional Services, Integration & Implementation, Consulting, Support & Maintenance, and Managed Services. Managed services are particularly in demand as businesses seek to outsource complex IT tasks to specialized providers. A study conducted by a leading tech industry association revealed that the demand for managed services in the Philippines has grown significantly over the past few years, driven by the need for specialized expertise and cost optimization. The Integration & Implementation services are also seeing increased demand as organizations strive to seamlessly integrate new technologies into their existing infrastructure.
Segments
Based on Type
- Enterprise
- Edge
- Colocation
- Hyperscale
- Managed
- Modular
Based on Compound
- Hardware
- Power Systems
- Cooling Systems
- Racks
- Servers
- Networking Devices
- Others
- Nigeria Data Centre Infrastructure Management Software
- Cloud-based
- On-premises
- Service
- Professional Services
- Integration & Implementation
- Consulting
- Support & Maintenance
- Managed Services
Based on Size
- Small
- Mid-Sized
- Large
Based on Tier
- Tier 1
- Tier 2
- Tier 3
- Tier 4
Based on Industry
- IT & Telecom
- BFSI
- Manufacturing
- Healthcare
- Government
- Others
Based on Region
- Metro Manila
- Cebu
- Davao
- Other regions
Regional Analysis
Metro Manila (65%):
Metro Manila is the dominant region in the Philippines data center market, accounting for approximately 65% of the market share. As the country's capital and primary business hub, Metro Manila hosts most of the country's data centers. The region benefits from well-developed infrastructure, including reliable power supply, robust internet connectivity, and proximity to major business districts. This makes it an attractive location for both local and international data center operators. Major players have established significant data center facilities in this region to cater to the needs of enterprises, government agencies, and cloud service providers. For instance, PLDT Enterprise reported that their data center facilities in Metro Manila have seen increased demand from fintech and e-commerce companies in recent years. Additionally, Metro Manila's status as a financial hub drives demand from the banking, financial services, and insurance (BFSI) sector, further reinforcing its dominance in the market.
Cebu (20%):
Cebu is the second-largest region in the Philippines data center market, holding around 20% of the market share. Cebu's strategic location in the Visayas, coupled with its growing business environment, has made it a key area for data center development. The region is increasingly becoming a hub for outsourcing and business process outsourcing (BPO) activities, which demand reliable data center services. Cebu's connectivity to major undersea cable systems and its emerging IT infrastructure make it a favorable location for data centers. For instance, the Cebu Chamber of Commerce and Industry reported a significant increase in IT investments in the region over the past few years. Additionally, the local government's initiatives to promote digitalization and infrastructure development are attracting investments from data center operators looking to expand outside Metro Manila. The Cebu City government, for example, has implemented policies to streamline the process for establishing data centers in the city.
Key players
- Bitstop
- DataOne
- ePLDT Inc.
- GTI Corporation
- NTT Ltd.
- Space DC Pte Ltd.
- STT GDC Pte Ltd.
- VSTECS Phils Inc.
- Zenlayer Inc.
Competitive Analysis
The Philippines data center market is characterized by a diverse group of key players, each contributing to the market's growth through their unique offerings and strategic initiatives. ePLDT Inc. is a dominant player, leveraging its extensive telecommunications network and strong market presence to offer comprehensive data center solutions. NTT Ltd. and STT GDC Pte Ltd. bring global expertise and advanced technologies to the market, focusing on delivering high-reliability and scalable solutions. DataOne and GTI Corporation are notable for their specialized services, catering to specific industries and niche markets. Bitstop and VSTECS Phils Inc. provide essential IT infrastructure and services, supporting the digital transformation of businesses across the country. Zenlayer Inc. and Space DC Pte Ltd. are newer entrants, focusing on innovative and sustainable data center solutions, positioning themselves as key players in the growing demand for green data centers. The competitive landscape is dynamic, with both established and emerging players striving to capture market share through innovation, strategic partnerships, and customer-centric services.
Recent Developments
- In June 2024, ePLDT announced the upcoming launch of VITRO Sta. Rosa (VSR), the Philippines' biggest and first true hyperscale data center facility. The 50 MW capacity data center is set to go live in July 2024.
- In August 2024, ST Telemedia Global Data Centres (STT GDC) launched a nextIngeneration data hall in its Makati facility, expanding its presence in the Philippines.
- In July 2024, SpaceDC announced plans for MNL1, a 72MW data center facility in Manila that will operate entirely on geothermal and wind power.
- In September 2024, VSTECS Phils. Inc. announced the successful deployment of Versa Secure SDInWAN for RCBC, one of the country's largest commercial banks, enhancing the bank's network management and security.
- In July 2024, Equinix, in partnership with NTT Ltd., expanded into the Philippines with the acquisition of three data centers from Total Information Management.
Market Concentration and Characteristics
The Philippines data center market is moderately concentrated, with a mix of wellInestablished local and international players dominating the landscape. Major companies such as ePLDT Inc., NTT Ltd., and STT GDC Pte Ltd. hold significant market shares, leveraging their extensive resources, advanced technologies, and strong customer bases. The market is characterized by increasing competition as new entrants like Space DC Pte Ltd. and Zenlayer Inc. introduce innovative solutions, particularly in areas like sustainability and edge computing. Despite the dominance of a few key players, the market remains dynamic, driven by continuous investment in infrastructure, the expansion of cloud services, and growing demand across various sectors such as IT & Telecom, BFSI, and government. The market’s evolution is shaped by the need for high reliability, scalability, and energy efficiency, making it an attractive space for both established players and new entrants aiming to capitalize on the country’s digital transformation.
Report Coverage
The research report offers an inIndepth analysis based on Type, Compound, Size, Tier, Industry and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The demand for cloud services will continue to rise, driving the expansion of data centers to support the growing need for scalable and flexible IT infrastructure.
- Edge computing will gain momentum, with more data centers being developed in regional areas to reduce latency and support realIntime applications across the country.
- Sustainability will become a key differentiator, with data centers increasingly adopting green technologies and renewable energy sources to reduce their environmental impact.
- The Philippine government will continue to promote digital infrastructure development, offering incentives and support for data center investments to boost economic growth.
- Hyperscale data centers will see significant growth as global tech giants and cloud service providers expand their operations in the Philippines to meet rising demand.
- Colocation services will become more popular among businesses seeking costIneffective solutions for their IT needs, leading to further market expansion.
- As cyber threats evolve, there will be increased investment in advanced security measures, including AIIndriven threat detection and robust physical security protocols.
- The market will witness the growth of smart data centers, utilizing AI and IoT technologies to optimize operations, improve efficiency, and reduce operational costs.
- The establishment of data centers outside Metro Manila will accelerate, driven by the need for disaster recovery and the decentralization of digital infrastructure.
- As more players enter the market, competition will intensify, leading to potential mergers and acquisitions as companies seek to consolidate their market positions and enhance their offerings.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the Philippines data center market?
What are the main drivers of growth in the Philippines data center market?
Which regions are key to the Philippines data center market?
Who are some of the key players in the Philippines data center market?
What trends are shaping the future of the Philippines data center market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Philippines Data Center Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2023; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Philippines Data Center Market Snapshot
- 2.1.1 Market Size – Historical (2023) & Forecast (2023-2032) (2023: USD 2,269.39 million → 2032: USD 3,646.99 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Philippines Data Center Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2023 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2023
- 2.3.2 Top 10 Players by Volume Share – 2023
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Philippines Data Center Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Philippines Data Center Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Philippines Data Center Market Drivers
- 3.3 Philippines Data Center Market Restraints & Challenges
- 3.4 Philippines Data Center Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Philippines Data Center Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Philippines Data Center Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Philippines Data Center category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Philippines Data Center Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Philippines Data Center Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2023)
- 5.1.2 Global Export Volume by Country (2023)
- 5.1.3 Global Import Value by Country (2023)
- 5.1.4 Global Import Volume by Country (2023)
- 5.1.5 Net Trade Balance by Country (2023)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2023)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Philippines Data Center market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Philippines Data Center Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2023
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Philippines Data Center Market Share Analysis – 2023
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2023)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Philippines Data Center Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Philippines Data Center (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Philippines Data Center Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Philippines Data Center Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2023 & 2032)
- 7.1.2 Channel Mix Evolution (2023-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Philippines Data Center Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Philippines Data Center Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Philippines Data Center Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Philippines Data Center Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Philippines Data Center Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Philippines Data Center Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Philippines Data Center Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
