
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Polymer Biomaterials Market Size 2024 | USD 52788.5 million |
| Polymer Biomaterials Market, CAGR | 16.8% |
| Polymer Biomaterials Market Size 2032 | USD 182844.6 million |
Market Overview:
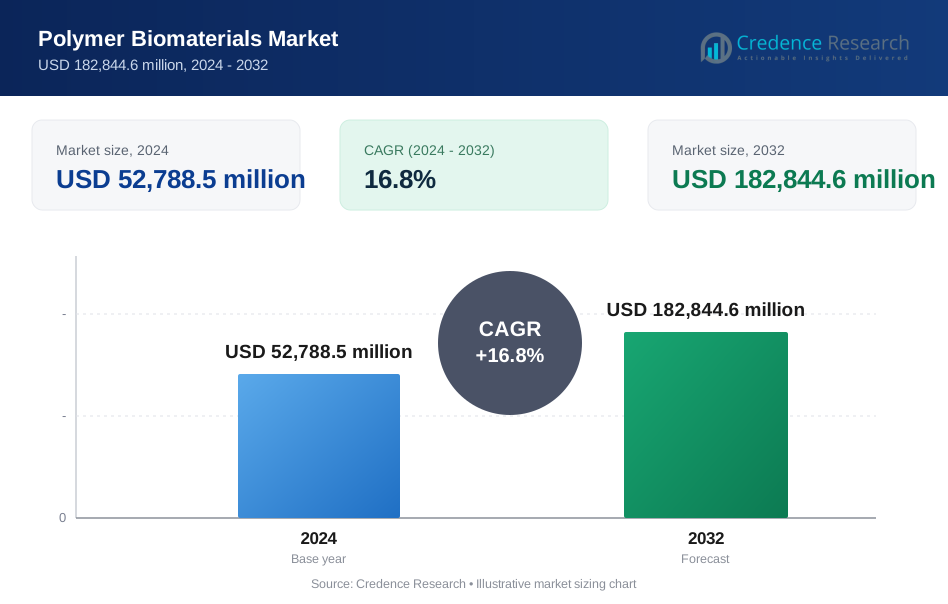
The Polymer Biomaterials market is projected to grow from USD 52788.5 million in 2024 to an estimated USD 182844.6 million by 2032, with a compound annual growth rate (CAGR) of 16.8% from 2024 to 2032.
The primary drivers of the Polymer Biomaterials market include the increasing demand for advanced medical devices and implants, driven by an aging population and the rising incidence of chronic conditions such as cardiovascular diseases, diabetes, and orthopedic disorders. Additionally, the ongoing advancements in polymer science are enabling the development of new biomaterials with enhanced biocompatibility, flexibility, and durability, which are crucial for various medical applications. The growing focus on minimally invasive surgical procedures and the need for biocompatible materials that can integrate seamlessly with human tissues are further propelling the market. Moreover, the expanding use of polymer biomaterials in regenerative medicine and tissue engineering is expected to drive significant growth, as these materials offer the potential to repair or replace damaged tissues and organs.
Regionally, North America holds the largest share of the Polymer Biomaterials market, driven by the presence of a well-established healthcare infrastructure, significant investments in research and development, and the high adoption rate of advanced medical technologies. The United States, in particular, is a major contributor to this market, owing to its robust medical device industry and extensive clinical research activities. Europe follows closely, with countries like Germany, France, and the UK leading the market, supported by strong government initiatives and increasing healthcare expenditures. The Asia-Pacific region is expected to witness the fastest growth during the forecast period, fueled by the rapid expansion of healthcare infrastructure, increasing investments in biotechnology and medical research, and the rising prevalence of chronic diseases in countries like China, India, and Japan. Emerging markets in Latin America and the Middle East & Africa are also anticipated to contribute to market expansion, driven by improving healthcare systems and growing awareness of advanced medical treatments.
Market Drivers:
Advancements in Medical Technology:
Advancements in medical technology are a significant driver of the Polymer Biomaterials market. As healthcare systems globally adopt cutting-edge technologies, there is an increasing demand for advanced materials that can meet the complex needs of modern medical devices and applications. Polymer biomaterials have become essential due to their versatility, allowing for the creation of products with enhanced biocompatibility, flexibility, and durability. Innovations in polymer chemistry and engineering are enabling the development of materials that can better mimic the properties of natural tissues, making them ideal for use in implants, prosthetics, and other medical devices. For instance, data from the Center for Connected Medicine survey indicates that 85% of healthcare executives believe that artificial intelligence (AI) has significant potential to improve clinical care. This continuous innovation in the field is expanding the potential applications of polymer biomaterials, further driving market growth.
Rising Prevalence of Chronic Diseases:
The rising prevalence of chronic diseases, such as cardiovascular diseases, diabetes, and orthopedic disorders, is another major driver of the Polymer Biomaterials market. These conditions often require long-term treatment, including the use of implants, prosthetics, and drug delivery systems, all of which benefit from the use of polymer biomaterials. As the global population ages, the incidence of these chronic conditions is expected to increase, leading to a higher demand for medical devices and materials that can provide effective and durable solutions. Polymer biomaterials are particularly well-suited for these applications due to their ability to be engineered to meet specific medical needs, including the ability to be biocompatible and capable of controlled drug release.
Growing Focus on Minimally Invasive Procedures:
The growing focus on minimally invasive surgical procedures is driving the demand for polymer biomaterials. These procedures, which aim to reduce patient recovery times and minimize surgical risks, often require the use of advanced materials that can be precisely fabricated and easily integrated into the body. Polymer biomaterials offer the flexibility and adaptability needed for these types of applications, making them an ideal choice for use in minimally invasive devices and implants. For instance, the WSES survey indicates that 83% of the total number of procedures performed in 2023 were minimally invasive, with the remaining 17% being surgical. As the medical community continues to shift towards less invasive treatment options, the demand for polymer biomaterials that can support these procedures is expected to rise, further propelling market growth.
Expanding Applications in Regenerative Medicine and Tissue Engineering:
The expanding applications of polymer biomaterials in regenerative medicine and tissue engineering are also key drivers of the market. These fields are rapidly evolving, with a growing focus on developing materials that can repair or replace damaged tissues and organs. Polymer biomaterials are at the forefront of these developments due to their ability to be engineered to support cell growth and differentiation, as well as their potential to be used in scaffolds that facilitate tissue regeneration. As research in regenerative medicine and tissue engineering progresses, the demand for high-quality polymer biomaterials is expected to increase significantly, driving growth in the market. The ability of these materials to be customized for specific medical applications makes them indispensable in the ongoing efforts to advance patient care and improve clinical outcomes.
Market Trends:
Increasing Adoption of Biodegradable Polymers:
A significant trend in the Polymer Biomaterials market is the increasing adoption of biodegradable polymers. These materials are gaining popularity due to their ability to break down naturally within the body, reducing the need for additional surgical procedures to remove implants or devices. Biodegradable polymers are particularly advantageous in applications such as drug delivery systems, where the material can safely degrade after the therapeutic agent has been delivered. The growing focus on reducing long-term complications and improving patient outcomes is driving the demand for these materials. As research and development continue to advance, new biodegradable polymers with enhanced properties are being introduced, further expanding their application in various medical fields.
Growth in 3D Printing Applications:
The use of 3D printing technology in the medical field is revolutionizing the way polymer biomaterials are utilized, and this trend is expected to drive significant growth in the market. 3D printing allows for the precise fabrication of complex structures, including customized implants and prosthetics tailored to individual patient needs. The ability to design and produce patient-specific devices using polymer biomaterials offers numerous advantages, including improved fit, functionality, and biocompatibility. For instance, the 3D Printing Industry Executive Survey reveals that 85% of healthcare facilities have adopted 3D printing for creating customized implants. As the technology becomes more accessible and cost-effective, its adoption is expected to increase, leading to greater demand for polymer biomaterials suitable for 3D printing applications. This trend is particularly relevant in the fields of orthopedics, dentistry, and reconstructive surgery, where personalized medical solutions are highly valued.
Advances in Nanotechnology:
Advances in nanotechnology are playing a crucial role in the development of new polymer biomaterials with enhanced properties and functionalities. Nanotechnology enables the manipulation of materials at the molecular or atomic level, allowing for the creation of biomaterials with improved strength, flexibility, and biocompatibility. In the context of polymer biomaterials, nanotechnology is being used to develop materials that can better mimic the natural environment of human tissues, promote cell growth, and deliver drugs more effectively. For instance, Startups Insights reports that 60% of nanotechnology startups are focused on developing advanced polymer biomaterials. This trend is driving innovation in various medical applications, including tissue engineering, drug delivery, and wound healing. As nanotechnology continues to evolve, its integration with polymer biomaterials is expected to open up new possibilities for medical advancements and market growth.
Increasing Focus on Sustainability:
The Polymer Biomaterials market is also witnessing an increasing focus on sustainability, driven by both environmental concerns and regulatory pressures. Manufacturers are increasingly looking for ways to develop biomaterials that are not only effective but also environmentally friendly. This has led to the exploration of renewable sources for polymer production, as well as the development of materials that have a reduced environmental impact throughout their lifecycle. The trend towards sustainability is particularly strong in regions with strict environmental regulations, such as Europe and North America. As healthcare providers and consumers alike become more conscious of the environmental impact of medical products, the demand for sustainable polymer biomaterials is expected to grow, shaping the future of the market.
Market Restraints and Challenges:
High Costs of Development and Production:
One of the key restraints in the Polymer Biomaterials market is the high cost associated with the development and production of these advanced materials. The process of designing, testing, and manufacturing polymer biomaterials that meet stringent biocompatibility and performance standards is both time-consuming and expensive. Research and development require significant investment, particularly when incorporating new technologies such as nanotechnology or 3D printing. Additionally, the production of these materials often involves specialized equipment and processes, further driving up costs. These financial barriers can limit the accessibility of polymer biomaterials, particularly in cost-sensitive markets or regions with limited healthcare budgets.
Regulatory Challenges:
Navigating the complex regulatory landscape is another significant challenge for the Polymer Biomaterials market. Given the critical nature of medical applications, polymer biomaterials must meet rigorous safety and efficacy standards set by regulatory bodies such as the FDA, EMA, and other regional authorities. The approval process for new biomaterials can be lengthy and resource-intensive, requiring extensive testing and documentation to demonstrate compliance with regulatory requirements. This can delay the time-to-market for new products and increase development costs. Additionally, differing regulatory standards across regions can complicate the global distribution of polymer biomaterials, creating challenges for manufacturers seeking to expand their market reach.
Biocompatibility and Longevity Concerns:
Biocompatibility and longevity of polymer biomaterials remain critical concerns that can restrain market growth. While advancements have been made in developing materials that interact favorably with human tissues, achieving consistent biocompatibility across various applications remains a challenge. Any adverse reactions, such as inflammation or rejection, can lead to complications and limit the use of certain materials. Furthermore, ensuring the long-term durability of polymer biomaterials, particularly in load-bearing or dynamic environments like orthopedic implants, is essential for their success. The ongoing need to balance biocompatibility with mechanical performance and durability presents a significant technical challenge for researchers and manufacturers in the field.
Competition from Alternative Materials:
The Polymer Biomaterials market also faces competition from alternative materials, such as ceramics, metals, and natural biomaterials, which may offer superior properties for certain applications. For example, metals are often preferred in orthopedic implants for their strength and durability, while ceramics are favored for their wear resistance and biocompatibility in dental applications. The availability of these alternatives can limit the adoption of polymer biomaterials, particularly in applications where they are perceived to offer less favorable performance characteristics. To overcome this challenge, polymer biomaterials must continue to evolve, offering enhanced properties that can compete with or surpass those of alternative materials.
Market Segmentation Analysis:
By Product, the market is categorized into natural polymer biomaterials and synthetic polymer biomaterials. Natural polymer biomaterials, such as collagen, gelatin, and chitosan, are widely used due to their inherent biocompatibility and ability to mimic natural tissues. These materials are particularly favored in applications like wound healing, tissue engineering, and drug delivery. Synthetic polymer biomaterials, including polyethylene, polypropylene, and polylactic acid (PLA), are valued for their versatility, durability, and ability to be engineered with specific properties. These materials are extensively used in the production of medical devices, implants, and prosthetics due to their strength and stability.
By Application, the market is segmented into cardiovascular, orthopedic, ophthalmology, wound healing, tissue engineering, and others. The cardiovascular segment is one of the largest, driven by the increasing prevalence of heart diseases and the demand for advanced stents and grafts. Orthopedic applications also represent a significant portion of the market, with polymer biomaterials being used in joint replacements, bone screws, and spinal implants. The tissue engineering segment is rapidly growing, fueled by advancements in regenerative medicine and the need for materials that can support the repair or replacement of damaged tissues. Wound healing and ophthalmology are other critical applications where polymer biomaterials play a vital role in improving patient outcomes.
Segmentation:
By Product,
- Natural polymer biomaterials
- Synthetic polymer biomaterials.
By Application,
- Cardiovascular,
- Orthopedic,
- Ophthalmology,
- Wound healing,
- Tissue engineering,
- North America
- The U.S
- Canada
- Mexico
- Europe
- Germany
- France
- The U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of Middle East and Africa
Regional Analysis:
North America
North America holds the largest share of the Polymer Biomaterials market, accounting for approximately 35% of the global market in 2023. The region's dominance is driven by its well-established healthcare infrastructure, robust research and development activities, and the presence of leading biotechnology and medical device companies. The United States, in particular, plays a critical role in the market, benefiting from significant investments in medical research and innovation, supported by both private and public sectors. The country’s focus on advancing healthcare technologies, coupled with a high prevalence of chronic diseases requiring advanced medical treatments, has fueled the demand for polymer biomaterials. Additionally, the stringent regulatory environment in the U.S., which mandates high standards for medical products, further supports the adoption of high-quality biomaterials in various applications.
Europe
Europe represents approximately 30% of the global Polymer Biomaterials market, making it the second-largest region. The market in Europe is driven by strong government support for healthcare innovation and a well-developed medical device industry. Countries such as Germany, the United Kingdom, and France are key contributors, supported by robust healthcare systems and significant investments in biotechnology and material sciences. Europe’s regulatory framework, which emphasizes safety and efficacy, has also encouraged the development and adoption of advanced polymer biomaterials. Additionally, the region's focus on sustainability and environmentally friendly practices is influencing the production and use of biomaterials that align with these values. The presence of major research institutions and a strong collaborative environment between academia and industry further enhances the region’s market position.
Asia-Pacific
The Asia-Pacific region is the fastest-growing market for Polymer Biomaterials, with a market share of approximately 25% in 2023. This rapid growth is driven by the expanding healthcare infrastructure, increasing investments in biotechnology, and the rising prevalence of chronic diseases in countries like China, India, and Japan. The region is witnessing significant government initiatives aimed at improving healthcare access and encouraging innovation in medical technologies. China, in particular, is emerging as a key market due to its large population and growing demand for advanced medical treatments. Japan’s strong focus on technological innovation and India’s expanding pharmaceutical and medical device sectors are also contributing to the region’s growth. The rising adoption of polymer biomaterials in regenerative medicine, drug delivery, and medical devices is expected to continue driving market expansion in Asia-Pacific.
Latin America and Middle East & Africa
Latin America and the Middle East & Africa collectively account for approximately 10% of the global Polymer Biomaterials market. These regions are emerging markets with significant growth potential, driven by improving healthcare infrastructure and increasing awareness of advanced medical treatments. In Latin America, countries like Brazil and Mexico are leading the market, supported by government efforts to enhance healthcare services and promote biomedical research. The Middle East & Africa region is also seeing growth, particularly in countries like Saudi Arabia and the UAE, where there is a strong emphasis on healthcare modernization and attracting foreign investments in the medical sector. However, challenges such as limited access to advanced technologies and varying regulatory standards may temper growth in these regions. Despite these challenges, the ongoing improvements in healthcare systems and the growing demand for innovative medical solutions are expected to support market growth in the coming years.
Key Player Analysis:
- BASF SE
- Bayer AG
- Berkeley Advanced Biomaterials.
- Bezwada Biomedical LLC
- Corbion NV
- Covestro A
- Foster Corporation
- Indorama Ventures Public Company Limited.
- Invibio Ltd.
- MITSUI & CO.
- MicroPort Scientific Corporation
- Novo Nordisk
- Royal DSM
- Starch Medical Inc
- Stein Fibers LTD
- STRATEC SE
- TikonaInfinet Private Limited
- TORAY INDUSTRIES INC.
- Victrex plc.
- L. Gore & Associates Inc.
- Wright Medical Group N.V.
- Zimmer Biomet
Competitive Analysis:
The Polymer Biomaterials market is characterized by a competitive landscape where several key players dominate due to their extensive product portfolios, strong research and development capabilities, and global distribution networks. Major companies such as BASF SE, Evonik Industries, Corbion, and Covestro lead the market by continuously innovating and expanding their biomaterial offerings to cater to the growing demand in medical applications. These companies leverage their expertise in polymer science to develop advanced biomaterials that meet the stringent requirements of biocompatibility, durability, and performance. Additionally, emerging players and startups are increasingly entering the market, focusing on niche applications and novel biomaterial technologies. Strategic partnerships, mergers, and acquisitions are common as companies seek to enhance their market positions and broaden their product offerings. The competitive environment is driven by the need for innovation and differentiation, as companies aim to meet the evolving needs of the healthcare and medical device industries.
Recent Developments:
- In July 2022, Corbion partnered with STENTiT and Vivolta to develop a regenerative stent aimed at treating patients with critical limb ischemia for clinical use.
- In April 2023, Novo Nordisk collaborated with Aspect Biosystems, a bioprinted biomaterials company, to develop bioprinted tissue therapeutics targeting diabetes and obesity.
- In March 2023, Invibio Ltd. launched its PEEK-OPTIMA AM filament, specifically designed for the additive manufacturing sector within the medical device industry, offering enhanced performance and precision.
- In January 2023, MicroPort Scientific Corporation received marketing authorization in Russia for its Firehawk Liberty Rapamycin Target Eluting Coronary Stent System, which is expected to extend the company's geographic reach.
Market Concentration & Characteristics:
The Polymer Biomaterials market exhibits a moderate level of concentration, with a few leading companies such as BASF SE, Evonik Industries, and Corbion holding significant market shares due to their extensive product offerings and strong R&D capabilities. These established players dominate the market through continuous innovation, focusing on developing advanced biomaterials that meet stringent biocompatibility and performance standards. The market is characterized by high entry barriers, driven by the need for specialized knowledge, significant capital investment, and compliance with rigorous regulatory requirements. Despite the dominance of major players, the market remains dynamic, with emerging companies and startups entering the field, particularly in niche segments such as regenerative medicine and drug delivery. The competitive landscape is shaped by ongoing advancements in polymer science, growing demand for personalized medical solutions, and the increasing integration of sustainable practices in material development.
Report Coverage:
The research report offers an in-depth analysis based on By Product, By Application. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The demand for biocompatible materials in medical devices will continue to drive market growth.
- Advances in polymer science will lead to the development of more sophisticated biomaterials.
- The growing prevalence of chronic diseases will increase the need for durable and effective biomaterials.
- Expansion in regenerative medicine will boost the adoption of polymer biomaterials.
- Rising healthcare investments in emerging markets will create new growth opportunities.
- The integration of nanotechnology will enhance the functionality of polymer biomaterials.
- Increasing regulatory support for innovative medical solutions will accelerate market expansion.
- Sustainability concerns will drive the development of eco-friendly biomaterials.
- 3D printing technologies will further increase demand for customizable polymer biomaterials.
- Strategic collaborations between industry and academia will foster innovation and market growth.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Advancements in Medical Technology
Continuous innovation in polymer chemistry and engineering is enabling the creation of biomaterials with improved biocompatibility, flexibility, and durability, supporting the development of next-generation medical devices and implants.
Rising Prevalence of Chronic Diseases
The increasing incidence of cardiovascular, orthopedic, and metabolic disorders is driving demand for polymer biomaterials used in implants, prosthetics, and drug delivery systems, especially as the global population ages.
Growing Focus on Minimally Invasive Procedures
The shift toward minimally invasive surgeries requires advanced, adaptable materials that can be precisely fabricated and integrated into the body, making polymer biomaterials essential for these applications.
Expanding Applications in Regenerative Medicine and Tissue Engineering
Polymer biomaterials are increasingly used in regenerative medicine and tissue engineering due to their ability to support cell growth and tissue repair, fueling market growth as these fields advance.
Increasing Adoption of Biodegradable and Sustainable Polymers
Rising environmental concerns and regulatory pressures are accelerating the adoption of biodegradable and eco-friendly polymer biomaterials, especially in regions with strict sustainability standards.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the Polymer Biomaterials market?
What are the primary drivers of market growth?
Which region holds the largest market share?
What are the main challenges facing the Polymer Biomaterials market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Product
- 1.2.1 Natural polymer biomaterials
- 1.2.2 Synthetic polymer biomaterials
- 1.3 By Application
- 1.3.1 Cardiovascular
- 1.3.2 Orthopedic
- 1.3.3 Ophthalmology
- 1.3.4 Wound healing
- 1.3.5 Tissue engineering
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 52,788.5 million → 2032: USD 182,844.6 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Polymer Biomaterials Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Polymer Biomaterials Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Polymer Biomaterials Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Polymer Biomaterials Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Polymer Biomaterials Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Polymer Biomaterials Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Polymer Biomaterials Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Polymer Biomaterials Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 52,788.5 million → 2032: USD 182,844.6 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Polymer Biomaterials Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Product - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Natural polymer biomaterials
- 12.3.7.2 Synthetic polymer biomaterials
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Cardiovascular
- 12.4.7.2 Orthopedic
- 12.4.7.3 Ophthalmology
- 12.4.7.4 Wound healing
- 12.4.7.5 Tissue engineering
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Global Polymer Biomaterials End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Polymer Biomaterials Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Polymer Biomaterials Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Polymer Biomaterials Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 BASF SE
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Corbion NV
- 18.4 Covestro AG
- 18.5 Invibio Ltd.
- 18.6 MicroPort Scientific Corporation
- 18.7 Royal DSM
- 18.8 Wright Medical Group N.V.
- 18.9 Zimmer Biomet
- 18.10 Bayer AG
- 18.11 TORAY INDUSTRIES INC.
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

