
Market Overview:
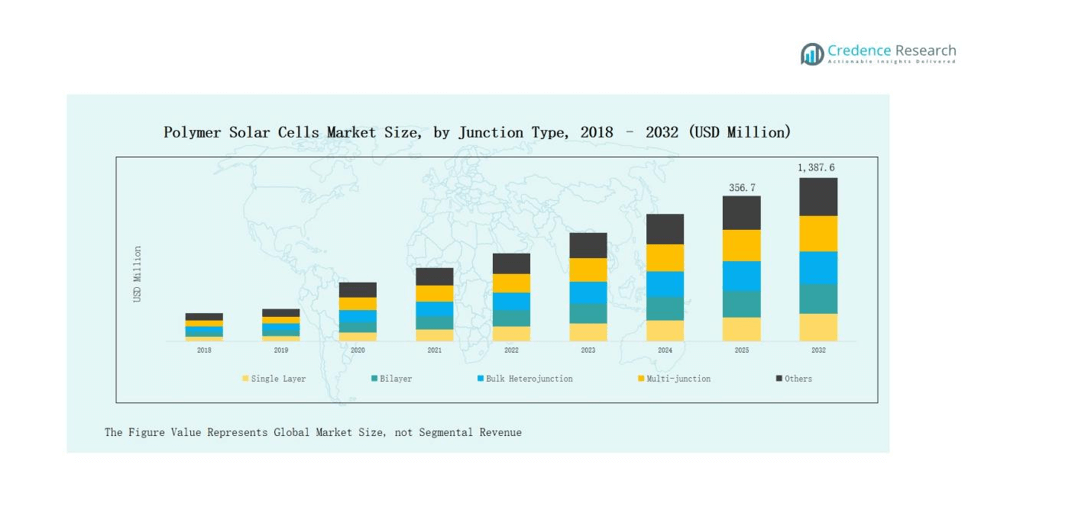
Polymer Solar Cells Market size was valued at USD 150.0 million in 2018 to USD 295.0 million in 2024 and is anticipated to reach USD 1,387.6 million by 2032, at a CAGR of 21.4% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Polymer Solar Cells Market Size 2024 | USD 295.0 million |
| Polymer Solar Cells Market, CAGR | 21.4% |
| Polymer Solar Cells Market Size 2032 | USD 1,387.6 million |
The Polymer Solar Cells Market is shaped by key players such as Heliatek GmbH, infinityPV ApS, BELECTRIC OPV GmbH (OPVIUS GmbH), SUNEW, Solarmer Energy, Armor Group, Solvay S.A., Eight19 Ltd., SolarWindow Technologies, Inc., and Raynergy Tek Incorporation. These companies focus on material innovation, printing technologies, and integration into applications like BIPV and consumer electronics to strengthen their competitive edge. Asia Pacific leads the market with 34% share in 2024, supported by large-scale renewable projects, robust consumer electronics demand, and strong government incentives, making it the dominant region in global adoption.
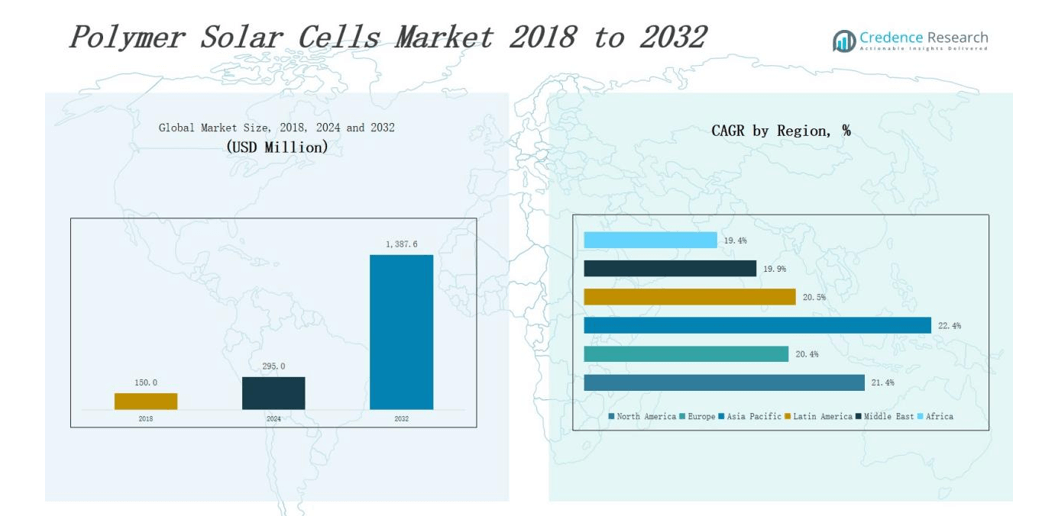
Market Insights
- The Polymer Solar Cells Market grew from USD 150.0 million in 2018 to USD 295.0 million in 2024 and is projected to reach USD 1,387.6 million by 2032 at a CAGR of 4%, with Asia Pacific leading adoption at 34% share in 2024.
- Bulk heterojunction cells dominate by junction type with 56% share, supported by superior light absorption and efficiency, while multi-junction designs at 21% share show rising potential through advanced material innovation.
- By application, BIPV leads with 42% share, driven by demand for flexible and aesthetic integration in urban infrastructure, followed by consumer electronics at 27% and automotive at 15%, expanding use in electric vehicles.
- Printing techniques account for 61% share, driven by scalable, low-cost roll-to-roll production, while coating techniques hold 39% share, supporting precision-driven applications in defense and automotive sectors.
- Regionally, North America holds 29% share, Europe 23%, Asia Pacific 34%, Latin America 7%, Middle East 4%, and Africa 3%, with growth driven by renewable projects, government incentives, and expanding off-grid power adoption.
Market Segment Insights
By Junction Type
Bulk heterojunction polymer solar cells dominate the market with 56% share due to their superior light absorption and charge separation efficiency. This design enhances power conversion, making it the most commercially viable option compared to single-layer or bilayer structures. Multi-junction cells, with 21% share, show strong potential as efficiency improves through material innovation, while single-layer and bilayer designs hold niche use in research and low-cost prototypes.
- For instance, Heliatek GmbH, a German pioneer in organic photovoltaics, introduced its HeliaSol® modules for building integration, demonstrating efficiencies above 13% in BHJ-based films.
By Application
BIPV (Building Integrated Photovoltaic) leads with 42% share, driven by demand for lightweight, flexible, and aesthetically integrated solar solutions in urban infrastructure. Consumer electronics follow with 27% share, supported by rising adoption of portable energy devices such as wearables, e-readers, and small gadgets. Automotive applications, at 15% share, gain traction through solar-embedded panels for electric vehicles, while defense and emergency use cases account for 10% share, benefiting from lightweight and rapid-deployment features.
- For instance, Lightyear 0, introduced in 2022, features integrated solar cells that can add up to 70 km of driving range per day under optimal conditions.
By Technique
Printing technique holds the largest market share at 61%, driven by scalability, low-cost roll-to-roll manufacturing, and high production speed. It enables flexible designs, supporting applications in consumer electronics and BIPV sectors. Coating technique accounts for 39% share, with adoption in high-precision applications where material uniformity and improved layer thickness control are essential, particularly in automotive and defense applications.
Market Overview
Rising Demand for Lightweight and Flexible Energy Solutions
The polymer solar cells market benefits from increasing adoption of lightweight and flexible photovoltaic technologies. Their thin-film design enables integration into curved and portable surfaces, offering unique advantages over rigid silicon-based alternatives. Consumer electronics, wearables, and building-integrated photovoltaics leverage these characteristics to deliver compact, energy-efficient solutions. Growing awareness of sustainable energy options and the push toward decentralized power generation further drive demand, positioning polymer solar cells as an innovative alternative for next-generation renewable energy applications across multiple industries.
- For instance, Ohio State University researchers found that integrating silver nanoparticles into polymer solar cells significantly improves electrical current generation, boosting potential efficiency and commercial viability for flexible solar applications
Advancements in Printing and Coating Techniques
Technological progress in large-area printing and coating techniques supports cost-effective and scalable production of polymer solar cells. Roll-to-roll printing, in particular, enables high-speed manufacturing while maintaining material flexibility and functional efficiency. These techniques reduce production costs significantly compared to traditional solar cell fabrication methods. The growing availability of advanced conductive polymers and inks further enhances efficiency and durability, accelerating commercialization. This combination of reduced costs and scalable technology creates a competitive advantage for polymer solar cells in both consumer electronics and BIPV applications.
- For instance, Ricoh launched a paper-based, printable photovoltaic cell in 2020, using organic semiconductors applied via printing methods to deliver lightweight, eco-friendly solar solutions
Government Incentives and Sustainability Goals
Supportive policies, subsidies, and incentives for renewable energy adoption directly boost the market for polymer solar cells. Governments worldwide emphasize clean energy integration into urban infrastructure and residential projects, aligning with global carbon neutrality goals. Flexible solar technologies enable unique deployment in locations where traditional modules are unsuitable, adding to their attractiveness. Financial support for R&D and pilot projects accelerates innovation, while favorable feed-in tariffs and tax benefits strengthen market adoption. These initiatives highlight polymer solar cells as a strategic contributor to renewable energy transitions.
Key Trends & Opportunities
Integration into Building-Integrated Photovoltaics (BIPV)
BIPV emerges as a significant growth avenue, with polymer solar cells enabling seamless integration into façades, windows, and rooftops. Their lightweight, flexible, and semi-transparent features allow architects and developers to design sustainable buildings without compromising aesthetics. This trend aligns with smart city projects and green building certifications, creating a robust opportunity for widespread adoption. Rising demand for energy-efficient infrastructure, particularly in Europe and Asia-Pacific, positions polymer solar cells as a competitive choice in urban energy transition strategies and sustainable construction projects.
- For instance, Sekisui Chemical in Japan received ¥157 billion in subsidies to scale its manufacturing of polymer solar cells for BIPV, highlighting government support for advancing these technologies in building applications.
Expanding Role in Consumer Electronics
The growing consumer shift toward portable, self-charging electronics drives opportunities for polymer solar cells. Flexible panels are increasingly used in wearables, e-readers, smartphones, and IoT-enabled devices, enhancing product appeal by reducing dependency on external charging. As the electronics industry prioritizes sustainability and longer battery life, polymer solar cells align with demand for innovative energy solutions. Their potential to power devices in off-grid and remote settings further enhances market prospects, especially as connected devices proliferate in developed and emerging economies.
- For instance, Mitsubishi Chemical Corporation has developed highly efficient and durable organic solar cell modules that are integrated into smart infrastructure and automotive applications, showcasing polymer solar cells' adaptability beyond traditional electronics.
Key Challenges
Lower Efficiency Compared to Conventional Solar Technologies
A primary limitation for polymer solar cells remains their lower energy conversion efficiency compared to crystalline silicon solar cells. While research has improved efficiency levels over recent years, the gap persists, reducing competitiveness in large-scale power generation. This challenge restricts adoption in high-demand energy projects where maximum output per surface area is critical. Addressing efficiency concerns through advanced polymer blends and hybrid structures is necessary to improve commercial acceptance and expand market share beyond niche applications.
Durability and Stability Issues
Polymer solar cells face durability challenges due to sensitivity to oxygen, moisture, and ultraviolet radiation. These vulnerabilities limit their long-term performance and reliability, especially in outdoor environments. Encapsulation techniques and barrier coatings are being developed to enhance stability, but costs remain high. Without improved operational lifespans, customers may hesitate to adopt polymer solar cells for permanent infrastructure projects. Overcoming degradation concerns through material innovation and protective layering remains essential to unlock wider market adoption and investor confidence.
High Production Costs for Advanced Materials
Although printing techniques reduce fabrication expenses, advanced conductive polymers, organic materials, and encapsulation layers contribute to high production costs. These expenses often offset the cost advantages of large-area printing, especially in early-stage commercialization. Limited large-scale supply chains for specialized materials also add to pricing volatility. Manufacturers must focus on improving economies of scale and material efficiency to make polymer solar cells more price-competitive against established alternatives. Failure to reduce costs could limit adoption to premium or specialized applications.
Regional Analysis
North America
North America holds a 29% market share in 2024, supported by strong adoption in BIPV and consumer electronics. The market grew from USD 39.8 million in 2018 to USD 77.0 million in 2024 and is projected to reach USD 361.4 million by 2032, reflecting a 21.4% CAGR. The U.S. dominates with extensive R&D and supportive renewable energy policies, while Canada and Mexico contribute through clean energy integration in infrastructure. Favorable subsidies, sustainability goals, and investment in innovative solar technologies ensure North America remains a leading hub for polymer solar cell development.
Europe
Europe accounts for 23% share in 2024, driven by demand in building-integrated photovoltaics and smart city projects. The market expanded from USD 32.2 million in 2018 to USD 60.3 million in 2024 and is expected to reach USD 264.0 million by 2032 at a 20.4% CAGR. Countries such as Germany, France, and the UK lead adoption, supported by strict energy efficiency regulations and renewable targets. Integration into architectural projects and rising demand for semi-transparent panels fuel growth. Europe’s emphasis on sustainable construction and carbon neutrality ensures continued investment in polymer solar cell innovation.
Asia Pacific
Asia Pacific dominates the global market with a 34% share in 2024, making it the fastest-growing region. The market rose from USD 58.1 million in 2018 to USD 117.3 million in 2024 and is projected to reach USD 587.6 million by 2032, posting a 22.4% CAGR. China, Japan, South Korea, and India drive growth with large-scale renewable projects, strong electronics industries, and government-backed clean energy initiatives. Widespread deployment in consumer devices, BIPV, and automotive applications further strengthens demand. Favorable policies, abundant manufacturing capabilities, and rising urbanization make Asia Pacific the key growth engine for this market.
Latin America
Latin America represents 7% of the market in 2024, showing steady growth across Brazil, Argentina, and emerging economies. The market expanded from USD 10.9 million in 2018 to USD 21.2 million in 2024 and is forecast to reach USD 93.5 million by 2032 at a 20.5% CAGR. Growth is supported by rising investment in clean energy infrastructure, government initiatives, and adoption in off-grid power systems. The flexible and lightweight design of polymer solar cells suits rural electrification projects, where energy access remains limited. Brazil leads deployment with increasing integration of renewable technologies into residential and commercial sectors.
Middle East
The Middle East holds a 4% share in 2024, with demand concentrated in GCC countries, Israel, and Turkey. The market increased from USD 5.8 million in 2018 to USD 10.6 million in 2024 and is projected to reach USD 45.2 million by 2032, growing at a 19.9% CAGR. Government-led diversification plans, such as Saudi Vision 2030 and UAE’s clean energy initiatives, support adoption. Polymer solar cells are favored for their lightweight, flexible integration into new infrastructure. Growing investments in sustainable urban projects and research collaborations strengthen the Middle East’s role as an emerging renewable energy hub.
Africa
Africa contributes 3% of the market in 2024, primarily driven by South Africa, Egypt, and emerging regional markets. The sector expanded from USD 3.3 million in 2018 to USD 8.5 million in 2024 and is projected to reach USD 35.9 million by 2032, recording a 19.4% CAGR. Adoption is supported by rural electrification needs and off-grid applications, where flexible solar modules provide cost-effective energy access. Government initiatives to expand renewable capacity, combined with rising energy demand, are driving gradual adoption. While challenges in infrastructure remain, the potential for polymer solar cells in Africa is significant.
Market Segmentations:
By Junction Type
- Single Layer
- Bilayer
- Bulk Heterojunction
- Multi-junction
- Others
By Application
- BIPV (Building Integrated Photovoltaic)
- Consumer Electronics
- Automotive
- Defence and Emergency
- Others
By Technique
- Printing Technique
- Coating Technique
By Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The Polymer Solar Cells Market is highly competitive, shaped by a mix of established renewable energy firms and specialized technology developers. Key players such as Heliatek GmbH, infinityPV ApS, BELECTRIC OPV GmbH (OPVIUS GmbH), SUNEW, Solarmer Energy, Armor Group, Solvay S.A., Eight19 Ltd., SolarWindow Technologies, Inc., and Raynergy Tek Incorporation focus on material innovation, efficiency improvements, and cost optimization to expand their market presence. Companies invest in advanced polymer blends, roll-to-roll printing, and encapsulation technologies to enhance performance and durability. Strategic partnerships with construction, automotive, and electronics industries enable broader integration of polymer solar cells in BIPV, consumer devices, and electric vehicles. Asia Pacific players leverage large-scale manufacturing and government incentives, while European firms emphasize sustainable building projects and research-led innovation. North American companies strengthen their position through extensive R&D and supportive policies. The competitive landscape is marked by continuous product development, pilot projects, and commercialization efforts aimed at scaling adoption globally.
Key Players
- Heliatek GmbH
- infinityPV ApS
- BELECTRIC OPV GmbH (OPVIUS GmbH)
- SUNEW
- Solarmer Energy, Inc.
- Armor Group
- Solvay S.A.
- Eight19 Ltd.
- SolarWindow Technologies, Inc.
- Raynergy Tek Incorporation
Recent Developments
- On February 12, 2025, Next Energy Technologies upgraded its pilot manufacturing line to produce larger laminated polymer solar cells measuring 40" x 60" to scale up production capacity and commercial viability.
- In November 2023, Heliatek partnered with Triflex to integrate solar films with advanced roofing solutions, offering waterproofing and clean energy generation simultaneously.
- In April 2025, infinityPV launched a slot-die coater designed for thin-film photovoltaic research, supporting scalable production of organic and inorganic solar cells.
Market Concentration & Characteristics
The Polymer Solar Cells Market reflects a moderately concentrated structure, with a limited number of specialized players holding significant influence over technological advancements and commercialization. It is characterized by continuous innovation in polymer materials, efficiency improvements, and scalable manufacturing techniques such as roll-to-roll printing. Companies focus on flexible, lightweight, and semi-transparent modules that enable integration into BIPV, consumer electronics, and automotive applications. Market concentration is reinforced by strong intellectual property portfolios and collaborations between manufacturers, research institutes, and government programs supporting renewable adoption. Regional characteristics vary, with Asia Pacific dominating through large-scale production and incentives, while Europe emphasizes sustainable building integration and North America drives R&D efforts. Competition centers on product durability, efficiency gains, and cost reduction strategies. It demonstrates growth potential as ongoing investment and supportive policies encourage expansion into emerging markets, ensuring a balanced mix of innovation-driven competition and strategic alliances across key regions.
Report Coverage
The research report offers an in-depth analysis based on Junction Type, Application, Technique and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Polymer solar cells will see strong adoption in building-integrated photovoltaic projects worldwide.
- Lightweight flexible designs will increasingly power consumer electronics, wearables, and portable self-charging devices.
- Roll-to-roll printing advancements will ensure scalable, cost-effective, and high-speed production processes globally.
- Multi-junction structures will achieve higher efficiencies, driving broader commercial and industrial market applications.
- Automotive manufacturers will integrate polymer solar cells into electric vehicles to improve energy efficiency.
- Defense and emergency sectors will deploy portable solar solutions for reliable off-grid energy supply.
- Research collaborations will accelerate advanced polymer material innovation and extend operational device durability.
- Asia Pacific will continue leading global manufacturing and adoption, supported by government incentives.
- Supportive renewable energy policies will boost urban infrastructure projects using advanced polymer solar technologies.
- Companies will form strategic partnerships to strengthen commercialization and expand global market penetration.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Integration into Building-Integrated Photovoltaics (BIPV)
Polymer solar cells' lightweight, flexible, and semi-transparent properties enable seamless integration into building façades, rooftops, and windows, supporting the trend toward sustainable urban infrastructure and smart city projects. This drives demand in both new construction and retrofitting, especially in regions with strong green building incentives.
Advancements in Printing and Coating Techniques
Innovations in roll-to-roll printing and advanced coating methods have significantly reduced production costs and enabled scalable, high-speed manufacturing of polymer solar cells. These technological improvements make large-area and flexible solar modules commercially viable for mass-market applications.
Government Incentives and Sustainability Goals
Supportive policies, subsidies, and renewable energy targets from governments worldwide are accelerating the adoption of polymer solar cells. Financial incentives for R&D, pilot projects, and deployment in infrastructure projects directly boost market growth and encourage investment in advanced solar technologies.
Expanding Use in Consumer Electronics and Automotive
The demand for portable, self-charging devices and the integration of solar panels into electric vehicles are expanding the application scope of polymer solar cells. Their flexibility and lightweight design make them ideal for powering wearables, IoT devices, and automotive components, driving adoption in these fast-growing sectors.
Material Innovation and Efficiency Improvements
Continuous research into advanced polymer blends, multi-junction structures, and encapsulation techniques is improving the efficiency and durability of polymer solar cells. These innovations are closing the performance gap with conventional silicon cells, making polymer solar cells more attractive for broader commercial and industrial use.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth of the Polymer Solar Cells Market from 2024 to 2032?
What factors are driving the growth of the Polymer Solar Cells Market?
How are government policies impacting the polymer solar cells market?
Which regions are expected to lead the polymer solar cells market?
What are some key applications driving demand for polymer solar cells?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Technique
- 1.2.1 Printing Technique
- 1.2.2 Coating Technique
- 1.3 By Application
- 1.3.1 BIPV (Building Integrated Photovoltaic)
- 1.3.2 Consumer Electronics
- 1.3.3 Automotive
- 1.3.4 Defence and Emergency
- 1.3.5 Others
- 1.4 By Junction Type
- 1.4.1 Single Layer
- 1.4.2 Bilayer
- 1.4.3 Bulk Heterojunction
- 1.4.4 Multi-junction
- 1.4.5 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 295.0 million → 2032: USD 1,387.6 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Polymer Solar Cells Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Polymer Solar Cells Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Polymer Solar Cells Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Polymer Solar Cells Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Polymer Solar Cells Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Polymer Solar Cells Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Polymer Solar Cells Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Polymer Solar Cells Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 295.0 million → 2032: USD 1,387.6 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Polymer Solar Cells Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Technique - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Printing Technique
- 12.3.7.2 Coating Technique
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Application - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 BIPV (Building Integrated Photovoltaic)
- 12.4.7.2 Consumer Electronics
- 12.4.7.3 Automotive
- 12.4.7.4 Defence and Emergency
- 12.4.7.5 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Junction Type - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Single Layer
- 12.5.7.2 Bilayer
- 12.5.7.3 Bulk Heterojunction
- 12.5.7.4 Multi-junction
- 12.5.7.5 Others
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Polymer Solar Cells End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Polymer Solar Cells Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Polymer Solar Cells Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Polymer Solar Cells Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Heliatek GmbH
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 infinityPV ApS
- 18.4 BELECTRIC OPV GmbH (OPVIUS GmbH)
- 18.5 SUNEW
- 18.6 Solarmer Energy, Inc.
- 18.7 Armor Group
- 18.8 Solvay S.A.
- 18.9 Eight19 Ltd.
- 18.10 SolarWindow Technologies, Inc.
- 18.11 Raynergy Tek Incorporation
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

