
Market Overview
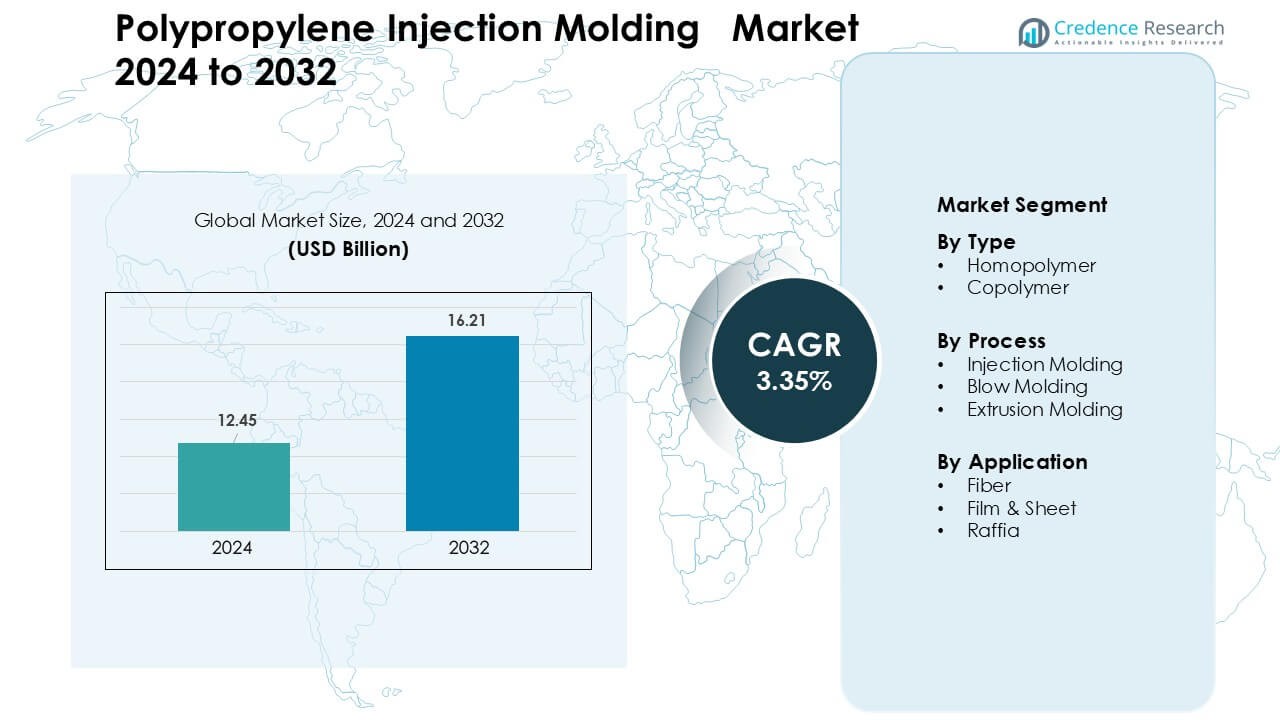
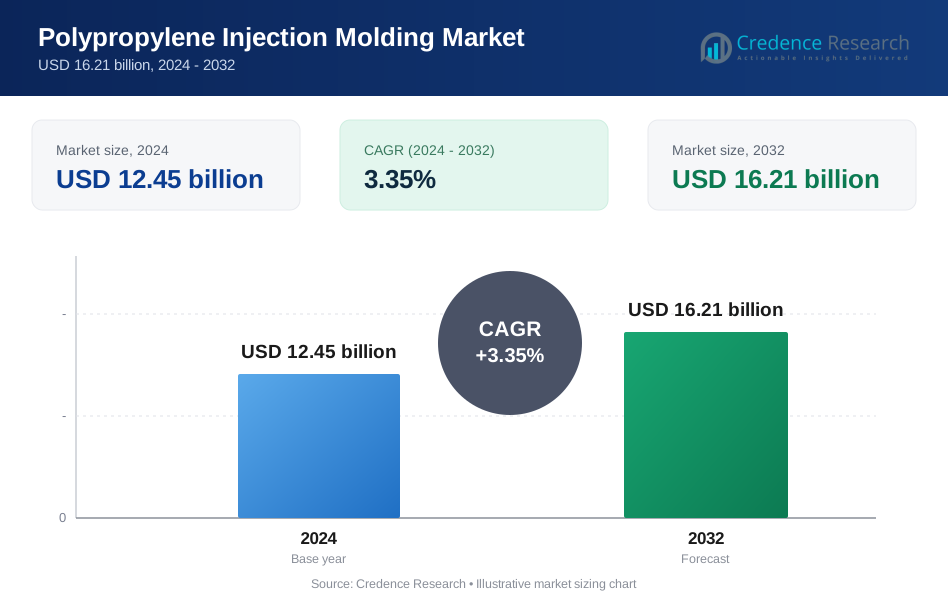
Polypropylene Injection Molding market was valued at USD 12.45 billion in 2024 and is anticipated to reach USD 16.21 billion by 2032, growing at a CAGR of 3.35% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Polypropylene Injection Molding Market Size 2024 | USD 12.45 Billion |
| Polypropylene Injection Molding Market, CAGR | 3.35% |
| Polypropylene Injection Molding Market Size 2032 | USD 16.21 Billion |
The polypropylene injection molding market is shaped by major players including DuPont, Braskem, Reliance Industries Limited, INEOS Group, LG Chem, SABIC, LyondellBasell Industries Holdings B.V., Exxon Mobil Corporation, BASF SE, and Borealis AG, each expanding advanced polypropylene grades for packaging, automotive, and consumer goods. These companies invest in reinforced, high-clarity, and recyclable materials to support large-volume molding operations across global manufacturing hubs. Asia-Pacific remained the leading region in 2024 with 41% share, driven by strong production capacity, rapid industrial growth, and rising demand from FMCG, automotive, electronics, and appliance sectors.
Market Insights
- The polypropylene injection molding market reached USD 45 billion in 2024 and is projected to hit USD 16.21 billion by 2032 at a CAGR of 3.35 %.
- Demand grew as packaging, automotive, and consumer goods producers increased use of lightweight, durable, and recyclable polypropylene components.
- Adoption of sustainable materials, recycled polypropylene, and advanced reinforced grades shaped new product trends across high-volume molding lines.
- Leading companies enhanced competitiveness through capacity expansion, high-performance grade development, and stronger partnerships with OEMs and converters.
- Asia-Pacific led the market with 41% share, while homopolymer dominated the type segment with 58% share and injection molding remained the top process with 61% share.
Market Segmentation Analysis:
By Type
Homopolymer dominated the type segment in 2024 with nearly 58% share due to strong use in rigid packaging, consumer goods, automotive interiors, and appliance components. Buyers preferred homopolymer because the grade offers high stiffness, good chemical resistance, and lower processing cost that supports large-volume output. Demand stayed solid as FMCG brands expanded lightweight packaging formats. Copolymer grew at a steady pace due to tougher impact properties, yet homopolymer maintained a lead because manufacturers used it widely for injection-molded caps, containers, and functional parts.
- For instance, LyondellBasell one of the world’s largest polypropylene homopolymer producers describes its homopolymer resins as delivering exceptional strength, clarity, and processability via Ziegler-Natta-catalyst technology, enabling efficient high-volume injection molding for packaging and automotive applications.
By Process
Injection molding held the dominant share in 2024 with roughly 61% because the process supports fast cycle time and high part accuracy for mass production. Producers relied on this process to supply automotive trims, storage boxes, medical components, and closures. Injection molding stayed ahead due to better design flexibility and lower scrap generation. Blow molding expanded in bottles and large hollow products, while extrusion molding gained use in sheets and profiles. Yet injection molding stayed the preferred option for polypropylene due to its broad industrial acceptance.
- For instance, the low melt viscosity and low moisture absorption (PP absorbs less than 0.01% water over 24 h) mean PP does not require pre-drying before molding, simplifying the processing workflow and speeding up throughput for large-scale production runs.
By Application
Film & sheet led the application segment in 2024 with close to 36% share, supported by heavy consumption in flexible packaging, food wraps, labels, and lamination structures. Packaging converters selected these grades for high clarity, strong seal strength, and good barrier improvement after metallization. Fiber grades grew due to geotextiles and hygiene products, while raffia advanced in woven bags for agriculture and cement. Film & sheet remained dominant because packaging producers scaled high-volume lines to meet rising demand for lightweight and recyclable solutions.
Key Growth Drivers
Growing Demand from Packaging and Consumer Goods
Strong expansion in packaging and consumer goods remained a major growth driver for the polypropylene injection molding market. Brands used injection-molded polypropylene for caps, closures, tubs, trays, and rigid containers because the material supports light weight, durability, and high design freedom. Global food and beverage companies expanded recyclable packaging lines, which pushed greater adoption of polypropylene grades designed for efficient molding cycles. Growth in personal care and household products increased purchases of molded components with high stiffness and chemical resistance. E-commerce also boosted demand for protective packaging formats. Rising output from FMCG and retail supply chains strengthened long-term market momentum.
- For instance, rigid PP boxes and stackable containers are widely used for warehousing and distribution of consumer goods, enabling lightweight, strong and reusable packaging an advantage in high-volume online retail logistics.
Rising Use of Polypropylene in Automotive Light weighting
Automotive manufacturers drove steady growth as polypropylene injection-molded components replaced heavier metal and rubber parts. Carmakers increased the use of molded polypropylene for dashboards, trims, consoles, under-the-hood parts, and battery housings to reduce vehicle weight. The shift toward fuel-efficient and electric vehicles raised demand for lighter components with high impact resistance and dimensional stability. Suppliers adopted advanced reinforced polypropylene grades to meet structural and safety needs while keeping costs low. Large investments in mobility platforms across Asia, Europe, and North America supported volume production. Growing EV manufacturing capacity further strengthened polypropylene consumption in automotive interiors and functional parts.
- For instance, when designing battery housings and under-hood components, many suppliers use fibre-reinforced polypropylene such as Fibremod from Borealis because it delivers structural strength and rigidity comparable to heavier materials while reducing mass of components significantly.
Advancement in High-Performance Polypropylene Grades
Continuous improvement in high-performance polypropylene grades created strong market expansion. Producers introduced impact-modified, mineral-filled, and glass-reinforced variants that enhanced stiffness, heat resistance, and moldability. These materials supported new applications in appliances, medical devices, electrical housings, and industrial components. Faster cycle times, better color consistency, and improved recyclability encouraged broader adoption in high-volume production lines. Innovations in odor-reduction and food-contact compliance increased demand from consumer and packaging industries. Growing investment in sustainable, low-VOC, and post-consumer recycled polypropylene solutions also created new opportunities for injection-molded parts across major end-use sectors.
Key Trends & Opportunities
Shift Toward Recycled and Sustainable Polypropylene Solutions
A key trend shaping the market is the rise of recycled and sustainable polypropylene grades. Brands increased commitments to circular packaging, which pushed demand for high-quality recycled polypropylene suitable for molding closures, housings, and consumer containers. Advances in chemical recycling improved feedstock purity and color stability. Regulations on plastic waste drove industries to adopt recyclable mono-material structures in packaging. Manufacturers also explored bio-based polypropylene grades for reduced carbon impact. Growth in closed-loop systems across FMCG and automotive supply chains created long-term opportunity for molded components using environmentally aligned materials.
- For instance, Amcor’s recyclable mono-PP bottles and containers use a combination of high-quality PP grades and optimized design for injection molding, allowing FMCG brands to meet circular economy goals while retaining durability and design flexibility.
Automation and Digitalization in Injection Molding Operations
Automation became a major opportunity as factories adopted robotic handling, smart mold monitoring, and real-time quality control. These systems enabled consistent part accuracy, lower defect rates, and rapid tool changes. Machine learning-based process optimization reduced cycle time and stabilized output during large production runs. Demand for integrated MES and Industry 4.0 platforms expanded in automotive, electronics, and medical molding facilities. Smart molding technology also helped reduce energy use, supporting sustainability goals. Rising investment in advanced molding machinery created room for capacity growth and operational efficiency improvements.
- For instance, Engel Austria integrates robotic pick-and-place systems and multi-axis automation with its injection molding machines, enabling cycle times under 20 seconds for small consumer parts while maintaining tight dimensional tolerances of ±0.05 mm.
Key Challenges
Volatility in Raw Material Supply and Pricing
Fluctuating polypropylene resin prices created a major challenge for manufacturers. Supply disruptions in propylene monomer markets, refinery outages, and trade restrictions triggered recurrent price variability. Production cost uncertainty affected profitability for molding companies serving packaging, automotive, and consumer goods. Smaller processors struggled with margin control during high-price cycles. Global dependence on petrochemical feedstocks limited flexibility for suppliers. Volatile resin costs also impacted contracts with large OEMs, forcing frequent renegotiations and tighter cost control across supply chains.
Competition from Alternative Materials and Processes
The market faced pressure from materials such as ABS, polyethylene, and engineering plastics that offered better strength, thermal stability, or surface finish for specific applications. Composites and 3D-printed materials also gained traction in low-volume or customized production. Regulatory pressure on plastics increased interest in paper-based and biodegradable alternatives, especially in packaging. These substitutions reduced polypropylene demand in selected segments. Competing molding processes like thermoforming and blow molding also captured opportunities in lightweight packaging and large hollow products. Manufacturers needed continuous innovation to maintain polypropylene’s competitive position.
Regional Analysis
North America
North America held nearly 28% share in 2024 due to strong demand from packaging, automotive, medical devices, and household goods. The United States led regional consumption as major FMCG and healthcare manufacturers expanded rigid packaging and molded component production. Automakers adopted lightweight polypropylene parts for trims, interiors, and EV-related components, which supported steady output. The region also saw higher interest in advanced copolymer grades and recycled polypropylene for sustainable packaging. Investments in automated molding lines and smart manufacturing strengthened market growth across key end-use sectors.
Europe
Europe accounted for about 24% share in 2024, driven by strict sustainability targets and high adoption of recyclable polypropylene packaging. Germany, Italy, and France strengthened demand through strong automotive, industrial, and electrical sectors that relied on high-performance molded parts. Regional regulations on single-use plastics pushed brands to expand mono-material polypropylene packaging. Growth in medical molding and consumer goods also supported volume expansion. Investments in bio-based polypropylene and chemical recycling technologies helped maintain Europe’s competitive position. Demand grew steadily as manufacturers adopted advanced molding systems to meet quality and efficiency standards.
Asia-Pacific
Asia-Pacific dominated the global market in 2024 with nearly 41% share, supported by large-scale packaging, automotive, electronics, and appliance production. China and India led demand growth due to expanding FMCG consumption and rising manufacturing output. Automakers invested in polypropylene components to support lightweight design in passenger vehicles and electric mobility. Southeast Asia strengthened demand through flexible packaging and consumer product manufacturing. Large production capacities and low-cost processing made the region a global hub for polypropylene molding. Continuous investments in extrusion, injection, and compounding facilities supported long-term expansion.
Latin America
Latin America captured close to 4% share in 2024, driven by growth in food packaging, household goods, and automotive component production. Brazil and Mexico remained the key contributors as regional converters expanded polypropylene-based rigid packaging for food, cosmetics, and cleaning products. Automotive suppliers increased use of molded polypropylene parts to support local vehicle assembly. Cost-sensitive sectors preferred homopolymer grades for mass-market goods. Infrastructure investment and rising urban consumption supported moderate growth. Recycling initiatives gained momentum, improving adoption of sustainable polypropylene solutions across regional manufacturing lines.
Middle East & Africa
Middle East & Africa held nearly 3% share in 2024 with demand driven by packaging, construction, and consumer product manufacturing. GCC countries expanded polypropylene molding capacity due to proximity to petrochemical feedstocks. Food and beverage companies increased use of rigid packaging formats, supporting steady demand. Africa’s growth came from rising consumption of low-cost household goods and expanding manufacturing clusters. Regional investments in plastics processing facilities strengthened local supply. Gradual adoption of modern injection molding systems and interest in recyclable polypropylene supported future market growth.
Market Segmentations:
By Type
- Homopolymer
- Copolymer
By Process
- Injection Molding
- Blow Molding
- Extrusion Molding
By Application
- Fiber
- Film & Sheet
- Raffia
By Geography
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Competitive Landscape
The competitive landscape of the polypropylene injection molding market features major players such as DuPont, Braskem, Reliance Industries Limited, INEOS Group, LG Chem, SABIC, LyondellBasell Industries Holdings B.V., Exxon Mobil Corporation, BASF SE, and Borealis AG, each strengthening their position through capacity expansions, advanced polypropylene grade development, and investments in high-efficiency molding materials. These companies focus on impact-modified, reinforced, and recyclable polypropylene solutions to meet rising demand from packaging, automotive, electronics, and consumer goods sectors. Strategic partnerships with converters and OEMs help secure long-term supply agreements. Many producers also invest in circular polymer programs, chemical recycling technologies, and bio-based polypropylene to align with sustainability requirements. Continuous upgrades in compounding capabilities, regional distribution networks, and application development centers enhance competitiveness and support large-scale adoption across global manufacturing ecosystems.
Key Player Analysis
- DuPont
- Braskem
- Reliance Industries Limited
- INEOS Group
- LG Chem
- SABIC
- LyondellBasell Industries Holdings B.V.
- Exxon Mobil Corporation
- BASF SE
- Borealis AG
Recent Developments
- In September 2025, Borealis AG announced an investment of over €100 million to expand and upgrade its polypropylene compounding facilities in Schwechat, Austria, adding new PP compounding capacity aimed at high-performance applications such as automotive and appliance injection-molded parts.
- In June 2024, DuPont announced an agreement to acquire Donatelle Plastics Incorporated, a contract manufacturer specializing in medical‑device components via injection molding, silicone processing, and precision tooling. This strengthens DuPont’s presence in healthcare‑segment molded plastic components.
- In January 2024, Braskem, in collaboration with Shell Chemicals, announced a program to produce circular polypropylene using ISCC‑PLUS–certified feedstock (from pyrolysis oil of plastic waste). This circular PP is intended for use in packaging, automotive, and other applications
Report Coverage
The research report offers an in-depth analysis based on Type, Process, Application and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand will rise as packaging and FMCG companies expand recyclable rigid packaging.
- Automotive suppliers will increase use of lightweight polypropylene components for EV platforms.
- Advanced copolymer and reinforced grades will support new applications in appliances and electronics.
- Growth in medical molding will boost demand for high-purity and chemical-resistant polypropylene.
- Automation and smart molding systems will enhance production speed and accuracy.
- Chemical recycling and bio-based polypropylene will gain stronger industry adoption.
- Manufacturers will invest in high-clarity and odor-controlled grades for food and personal care packaging.
- Asia-Pacific will continue to hold the dominant regional position due to large processing capacity.
- Regulatory pressure on sustainability will shift brands toward mono-material packaging formats.
- Global players will expand compounding and molding support centers to strengthen market presence.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Polypropylene Injection Molding Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is Polypropylene Injection Molding Market projected to grow between 2024 and 2032?
Which Polypropylene Injection Molding Market segment held the largest share in 2024?
What are the primary factors fueling the growth of Polypropylene Injection Molding Market?
Who are the leading companies in Polypropylene Injection Molding Market?
Which region commanded the largest share of Polypropylene Injection Molding Market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Polypropylene Injection Molding Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Polypropylene Injection Molding Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 12.45 billion → 2032: USD 16.21 billion)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Polypropylene Injection Molding Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Polypropylene Injection Molding Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Polypropylene Injection Molding Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Polypropylene Injection Molding Market Drivers
- 3.3 Polypropylene Injection Molding Market Restraints & Challenges
- 3.4 Polypropylene Injection Molding Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Polypropylene Injection Molding Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Polypropylene Injection Molding Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Polypropylene Injection Molding category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Polypropylene Injection Molding Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Polypropylene Injection Molding Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Polypropylene Injection Molding market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Polypropylene Injection Molding Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Polypropylene Injection Molding Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Polypropylene Injection Molding Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Polypropylene Injection Molding (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Polypropylene Injection Molding Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Polypropylene Injection Molding Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Polypropylene Injection Molding Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Polypropylene Injection Molding Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Polypropylene Injection Molding Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Polypropylene Injection Molding Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Polypropylene Injection Molding Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Polypropylene Injection Molding Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Polypropylene Injection Molding Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
