
Market Overview
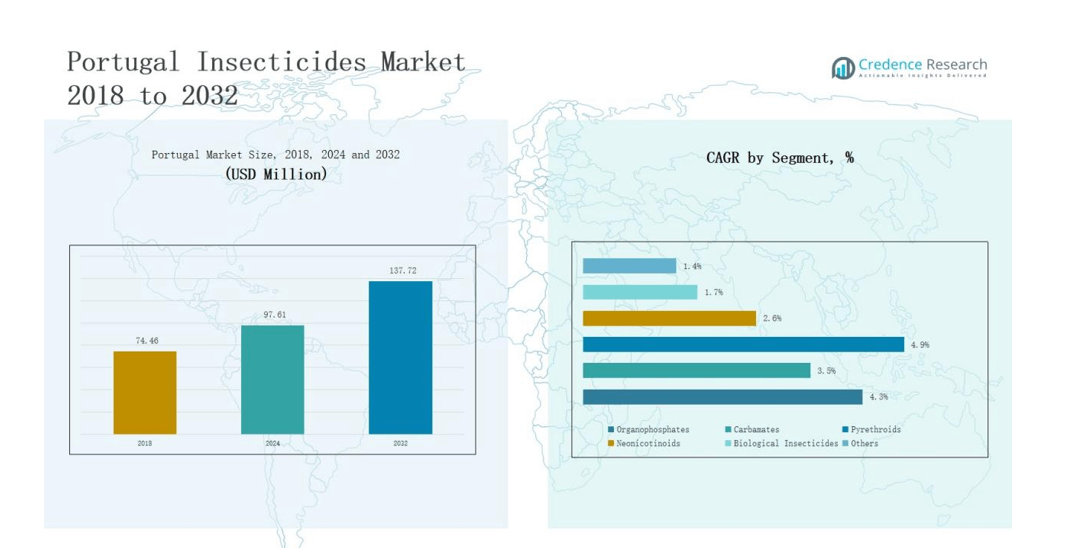
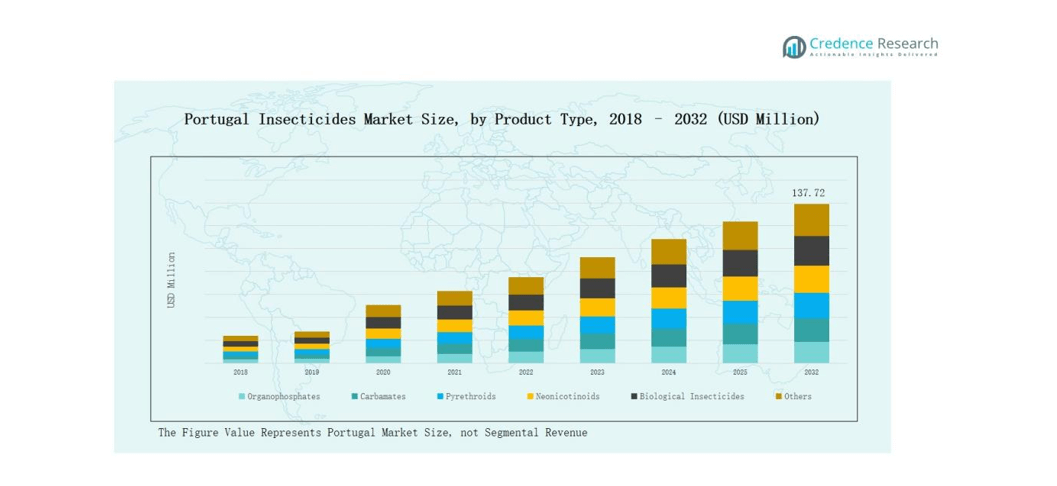
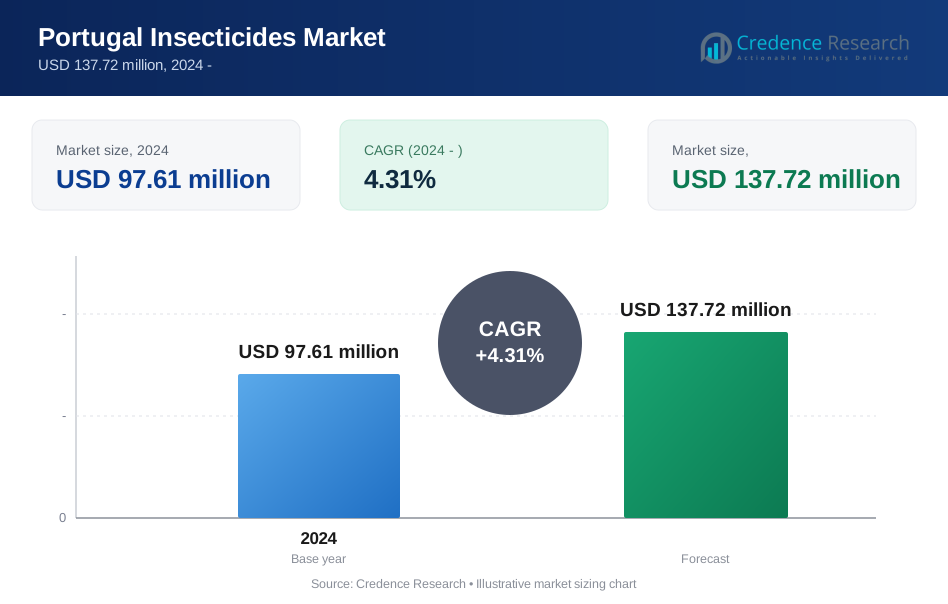
Portugal Insecticides Market size was valued at USD 74.46 million in 2018 to USD 97.61 million in 2024 and is anticipated to reach USD 137.72 million by 2032, at a CAGR of 4.31% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Portugal Insecticides Market Size 2024 | USD 97.61 million |
| Portugal Insecticides Market, CAGR | 4.31% |
| Portugal Insecticides Market Size 2032 | USD 137.72 million |
The Portugal Insecticides Market is shaped by the presence of global leaders and strong regional firms, each competing through innovation, regulatory compliance, and product diversification. Key players include Bayer CropScience, BASF SE, Syngenta, Corteva Agriscience, ADAMA, FMC Corporation, UPL Limited, Sipcam Portugal, Nufarm, and Valagro. These companies emphasize sustainable formulations and integrated pest management to address evolving agricultural needs. Among regions, Northern Portugal led the market in 2024, commanding 34% share, supported by intensive viticulture, horticulture, and high export-oriented crop production.
Market Insights
- The Portugal Insecticides Market grew from USD 74.46 million in 2018 to USD 97.61 million in 2024 and will reach USD 137.72 million by 2032.
- Organophosphates led by product type in 2024 with 32% share, followed by pyrethroids at 24% and neonicotinoids at 18%, while biological insecticides captured 15%.
- Agriculture dominated applications with 61% share in 2024, supported by vineyards, olive groves, and horticultural crops, while public health accounted for 17% and turf & landscape 9%.
- Northern Portugal commanded the highest regional share at 34% in 2024, driven by viticulture and horticulture, followed by Central at 27%, Southern at 22%, and Islands at 17%.
- Key players include Bayer CropScience, BASF SE, Syngenta, Corteva Agriscience, ADAMA, FMC Corporation, UPL Limited, Sipcam Portugal, Nufarm, and Valagro.
Market Segment Insights
By Product Type
Organophosphates dominated the Portugal insecticides market in 2024 with a 32% share, driven by broad-spectrum effectiveness in controlling pests across cereals, vegetables, and vineyards. Pyrethroids followed at 24%, favored for affordability and reliability in both crop protection and urban pest control. Neonicotinoids held 18%, primarily used in horticulture and fruit farming. Biological insecticides gained 15%, reflecting EU-driven sustainability trends. Carbamates captured 7%, while niche formulations under Others contributed 4%.
- For instance, Syngenta launched its biological insecticide Taegro in European markets, including Portugal, to support integrated pest management in horticulture and vineyards.
By Application
Agriculture remained the leading application, contributing 61% of Portugal’s insecticides revenue in 2024, supported by strong demand from vineyards, olive groves, and horticultural crops vital to exports. Public Health applications represented 17%, linked to mosquito and pest control programs. Turf & Landscape followed with 9%, covering sports fields and municipal spaces. Forestry accounted for 7%, focused on pine and eucalyptus protection. The Others category, including storage and domestic use, comprised 6% of market revenue.
- For instance, Syngenta supported Portugal’s national mosquito control campaigns with Actellic® 300CS, which the World Health Organization endorsed for vector control programs.
Market Overview
Rising Agricultural Intensification
Agricultural intensification in Portugal is a major driver for insecticide demand, accounting for the expansion of vineyards, olive groves, and horticultural crops. These sectors require reliable pest control to protect yields and maintain export quality standards. Farmers continue to adopt advanced formulations to address seasonal pest outbreaks. Increasing mechanization and modern irrigation further boost insecticide efficiency, strengthening their role in improving productivity and ensuring consistent supply to both domestic and international markets.
- For instance, Corteva Agriscience introduced the Closer insecticide in Portugal, designed to control sap-feeding pests in crops such as olives and citrus, using its sulfoxaflor active ingredient for targeted performance.
Government and EU Support for Crop Protection
The Portugal insecticides market benefits from supportive agricultural policies and EU-funded programs promoting crop productivity. Subsidies and grants aimed at modernizing farming practices encourage adoption of integrated pest management and selective insecticides. In addition, research initiatives foster innovation in eco-friendly formulations that comply with strict EU directives. Such support not only helps farmers balance pest control with environmental sustainability but also strengthens Portugal’s competitiveness in global agricultural exports, particularly in wine, olive oil, and fruit.
- For instance, Corteva Agriscience introduced Zorvec™ Active fungicide solutions across Southern Europe, including Portugal, to support sustainable vineyard protection with EU-compliant chemistry.
Increasing Pest Resistance and Climate Change
Rising pest resistance and climate variability are significant growth drivers for insecticide consumption in Portugal. Warmer temperatures, irregular rainfall, and longer growing seasons are enabling pest populations to thrive and spread, especially in vineyards and olive plantations. This scenario pushes farmers to adopt both chemical and biological insecticides in rotation. Demand for innovative solutions is expected to increase, as growers need sustainable pest management strategies that mitigate resistance while maintaining crop quality and productivity.
Key Trends & Opportunities
Shift Toward Biological Insecticides
A major trend shaping the Portugal insecticides market is the rapid shift toward biological solutions, which accounted for a growing share in recent years. Driven by EU’s Farm to Fork strategy and consumer demand for residue-free produce, farmers are integrating microbial and plant-based products into pest management practices. This transition creates opportunities for international and local players to introduce eco-friendly formulations, positioning biological insecticides as a key growth avenue in sustainable agriculture.
- For instance, Syngenta introduced its synthetic TYMIRIUM® nematicide/fungicide technology first in Argentina, providing long-lasting control of soil-borne pests and nematodes.
Integration of Precision Agriculture
The integration of precision agriculture technologies offers strong opportunities for insecticide optimization in Portugal. Tools such as drones, GPS-guided spraying, and AI-based pest monitoring are enhancing application efficiency while reducing wastage. These technologies allow farmers to target specific infestations with accurate doses, lowering costs and environmental impact. As adoption grows across vineyards and horticultural farms, precision agriculture will open new avenues for insecticide manufacturers, enabling customized solutions aligned with sustainable farming practices.
- For instance, EOSDA (EOS Data Analytics) partnered with local cooperatives in Alentejo to deploy satellite-based pest monitoring systems, allowing farmers to detect early outbreaks and optimize insecticide spraying schedules with higher accuracy.
Key Challenges
Stringent EU Regulations
Strict EU regulations on chemical usage present a significant challenge for Portugal’s insecticides market. Active ingredient bans, residue limits, and compliance checks restrict the use of several conventional insecticides, particularly organophosphates and carbamates. Farmers often face higher costs as they transition to approved alternatives. For manufacturers, the need to constantly reformulate products to meet compliance requirements delays product launches and increases R&D expenses, putting pressure on profitability while slowing market growth.
Rising Consumer Preference for Organic Produce
Growing consumer preference for organic and residue-free produce poses a challenge to traditional insecticides. Retailers and exporters increasingly demand certified products, forcing farmers to reduce reliance on chemical-based insecticides. This trend pressures conventional formulations while creating a competitive push for biological alternatives. For companies heavily dependent on chemical portfolios, adapting to evolving consumer demand requires restructuring strategies and investing in new technologies, which may strain resources and profitability in the short term.
Escalating Pest Resistance
Escalating pest resistance to widely used insecticides remains a persistent challenge in Portugal’s agriculture. Frequent application of similar active ingredients in vineyards, olive groves, and horticulture accelerates resistance buildup. As pests adapt, farmers need higher dosages or new products, raising costs and environmental risks. Manufacturers must continuously innovate resistance-management solutions, including integrated pest management and hybrid formulations. Without effective strategies, resistance threatens crop yields, reduces farmer confidence, and weakens long-term market sustainability.
Regional Analysis
Northern Portugal
Northern Portugal accounted for 34% share of the Portugal Insecticides Market in 2024, making it the leading regional segment. The dominance is supported by intensive viticulture in the Douro Valley and horticulture production. Farmers in this region adopt organophosphates and pyrethroids widely to protect vineyards from pest outbreaks. Biological insecticides are also expanding due to strict EU residue policies. The region’s role in wine exports sustains high demand for consistent pest management. Its diversified agriculture creates opportunities for both traditional and eco-friendly products.
Central Portugal
Central Portugal held 27% share of the national insecticides market in 2024. The region benefits from a strong concentration of olive groves and cereal cultivation that require reliable pest control. Neonicotinoids and organophosphates remain common, while biological alternatives are gaining traction. Public health programs addressing urban pests also support regional demand. It is experiencing rising adoption of integrated pest management techniques, driven by regulatory compliance. The region’s stable agricultural base ensures steady market growth for suppliers.
Southern Portugal
Southern Portugal represented 22% of the Portugal Insecticides Market in 2024. The Alentejo and Algarve areas dominate production of olives, citrus, and vegetables, creating sustained demand for targeted pest control. Farmers rely on pyrethroids and neonicotinoids, but biological insecticides are expanding rapidly to meet export quality standards. Public health usage for vector control also supports insecticide consumption. The hot climate contributes to higher pest activity, requiring frequent application cycles. This dynamic maintains the region’s importance for market participants.
Islands (Azores and Madeira)
The islands of Azores and Madeira accounted for 17% share of the Portugal Insecticides Market in 2024. Agriculture is specialized, with a focus on fruit crops, dairy, and ornamental plants. Pest control practices emphasize eco-friendly formulations to support biodiversity. Biological insecticides gain strong acceptance due to limited land resources and regulatory pressure. Public health applications are vital in maintaining tourism safety. The islands continue to represent a smaller but strategically significant segment for sustainable insecticide solutions.
Market Segmentations:
By Product Type
- Organophosphates
- Carbamates
- Pyrethroids
- Neonicotinoids
- Biological Insecticides
- Others
By Application
- Agriculture
- Forestry
- Turf & Landscape
- Public Health
- Others
By Region.
- Northern Portugal
- Central Portugal
- Southern Portugal
- Islands (Azores and Madeira)
Competitive Landscape
The Portugal Insecticides Market is characterized by the presence of global leaders and strong regional firms competing through product diversity, regulatory compliance, and innovation. Multinational companies such as Bayer CropScience, BASF SE, Syngenta, Corteva Agriscience, ADAMA, FMC Corporation, and UPL Limited dominate the landscape with broad-spectrum chemical and hybrid formulations. These players invest heavily in R&D to comply with strict EU directives and support sustainable agriculture. Regional firms, including Sipcam Portugal, Nufarm, and Valagro, enhance competitiveness by focusing on tailored solutions and expanding biological insecticide portfolios that align with rising eco-friendly demand. Competition is further shaped by strategic partnerships, product launches, and acquisitions aimed at strengthening distribution networks and addressing evolving pest challenges. Market participants emphasize integrated pest management and precision agriculture compatibility to maintain relevance. Overall, the market reflects a balance between established global brands and agile local companies responding to Portugal’s specific agricultural and regulatory environment.
Key Players
- Sipcam Portugal
- ADAMA
- Bayer CropScience
- BASF SE
- Syngenta
- FMC Corporation
- UPL Limited
- Corteva Agriscience
- Nufarm
- Valagro
Recent Developments
- In July 2025, Vestaron gained emergency approval in Portugal for its bioinsecticide SPEAR LEP to control Tuta absoluta in tomato crops, supported by partner LAINCO.
- In July 2025, ADAMA introduced its insecticide Trinalor™, offering rapid feeding cessation and up to three weeks of protection with low impact on beneficial insects.
- In March 2025, Syngenta launched the biological insecticide NETURE targeting corn leafhoppers and sap-sucker pests, enhancing control in corn and soybean crops.
- In October 2024, ADAMA gained registration for Sonavio®, a selective herbicide based on Bifenox, for broadleaf weed control in vegetables in Portugal.
Report Coverage
The research report offers an in-depth analysis based on Product Type, Application and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for biological insecticides will rise due to strict EU sustainability policies.
- Adoption of precision agriculture tools will enhance insecticide application efficiency.
- Farmers will increasingly rotate insecticides to manage growing pest resistance.
- Vineyards and olive groves will remain the leading consumers of insecticides.
- Public health programs will sustain demand for vector control products.
- Regulatory reforms will encourage faster transition to eco-friendly formulations.
- Partnerships between global and local firms will expand product availability.
- Digital monitoring systems will guide pest control decisions more effectively.
- Export-oriented crops will push adoption of residue-free pest management solutions.
- Regional players will gain ground by focusing on customized biological offerings.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Agricultural Intensification
The expansion of vineyards, olive groves, and horticultural crops in Portugal is increasing the need for effective insecticides to protect yields and maintain export quality, driving market growth.
Government and EU Support for Crop Protection
Supportive agricultural policies and EU-funded programs encourage the adoption of integrated pest management and selective insecticides, fostering innovation and compliance with sustainability standards.
Increasing Pest Resistance and Climate Change
Climate variability and escalating pest resistance are pushing farmers to adopt both chemical and biological insecticides in rotation, increasing overall market demand for innovative and sustainable solutions.
Shift Toward Biological Insecticides
EU sustainability policies and consumer demand for residue-free produce are accelerating the adoption of biological insecticides, creating new growth opportunities for eco-friendly product offerings.
Integration of Precision Agriculture
The adoption of precision agriculture technologies, such as drones and AI-based pest monitoring, is optimizing insecticide application, reducing waste, and supporting sustainable farming practices, thereby boosting market growth.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Portugal Insecticides Market, and what is its projected size in 2032?
Which Portugal Insecticides Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Portugal Insecticides Market?
Who are the leading companies in the Portugal Insecticides Market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Application
- 1.2.1 Agriculture
- 1.2.2 Forestry
- 1.2.3 Turf & Landscape
- 1.2.4 Public Health
- 1.2.5 Others
- 1.3 By Product Type
- 1.3.1 Organophosphates
- 1.3.2 Carbamates
- 1.3.3 Pyrethroids
- 1.3.4 Neonicotinoids
- 1.3.5 Biological Insecticides
- 1.3.6 Others
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 97.61 million → 2032: USD 137.72 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Portugal Insecticides Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Portugal Insecticides Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Portugal Insecticides Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Portugal Insecticides Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Portugal Insecticides Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Portugal Insecticides Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Portugal Insecticides Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Portugal Insecticides Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 97.61 million → 2032: USD 137.72 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Portugal Insecticides Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Application - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Agriculture
- 12.3.7.2 Forestry
- 12.3.7.3 Turf & Landscape
- 12.3.7.4 Public Health
- 12.3.7.5 Others
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Product Type - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Organophosphates
- 12.4.7.2 Carbamates
- 12.4.7.3 Pyrethroids
- 12.4.7.4 Neonicotinoids
- 12.4.7.5 Biological Insecticides
- 12.4.7.6 Others
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 Segment Growth Comparison
- 12.6 Segment Attractiveness and Priority Matrix
Chapter 13 Portugal Insecticides End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Portugal Insecticides Geographic Market Outlook, 2024-2032
- 14.1 Domestic Market Distribution and Demand Clusters
- 14.2 State- or Province-Wise Market Size and Forecast, 2024-2032
- 14.3 City and Metropolitan Market Outlook
- 14.4 Industrial, Manufacturing and Commercial Clusters
- 14.5 Geographic Concentration of Key End Users
- 14.6 Local Pricing and Purchasing Differences
- 14.7 Domestic Production Facilities and Capacity Map
- 14.8 Local Infrastructure and Project Pipeline
- 14.9 State-Level Policy and Incentive Differences
- 14.10 Subnational Investment Hotspots and Opportunities
- 14.11 Distribution and Logistics Networks
- 14.12 Domestic Competitive Footprint
Chapter 15 Portugal Insecticides Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Portugal Insecticides Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Bayer CropScience
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 BASF SE
- 18.4 Syngenta
- 18.5 Corteva Agriscience
- 18.6 ADAMA
- 18.7 FMC Corporation
- 18.8 UPL Limited
- 18.9 Sipcam Portugal
- 18.10 Nufarm
- 18.11 Valagro
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

