
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Power Grid System Market Size 2024 | USD 11677 million |
| Power Grid System Market, CAGR | 11.1% |
| Power Grid System Market Size 2032 | USD 27104.64 million |
Market Overview:
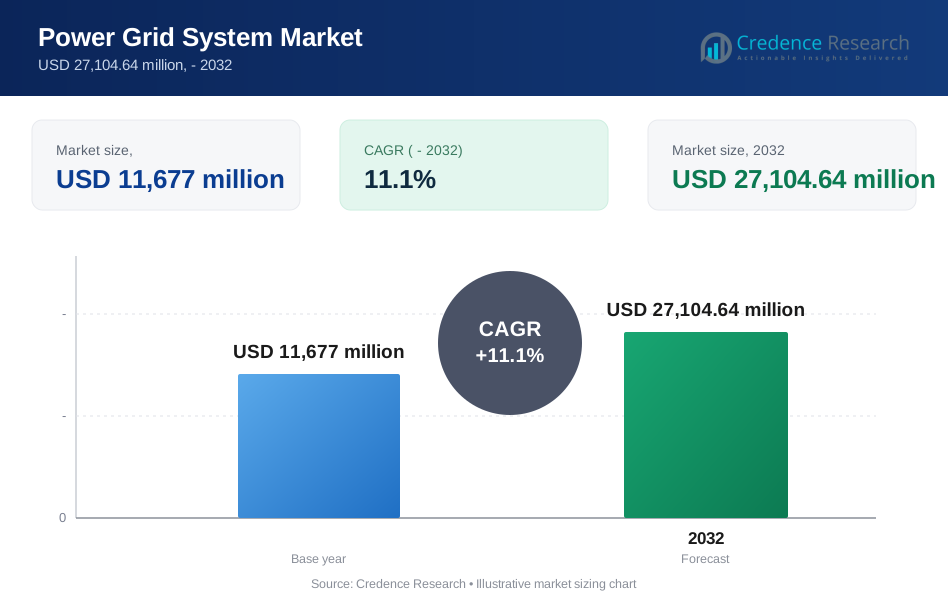
The Power Grid System Market is projected to grow from USD 11677 million in 2024 to an estimated USD 27104.64 million by 2032, with a compound annual growth rate (CAGR) of 11.1% from 2024 to 2032.
Several factors are fueling the growth of the Power Grid System Market. The ongoing shift towards renewable energy sources has led to a rise in distributed energy generation, necessitating the modernization of power grids to handle intermittent power supply and enhance grid stability. Additionally, increasing government initiatives and funding to upgrade aging infrastructure and improve grid resiliency are key drivers for the market. The growing adoption of smart grid technologies, such as advanced metering infrastructure and automated demand response systems, further propels market growth. Moreover, the demand for energy storage solutions is rising, driven by the need for efficient energy management and stable power supply. As emerging economies continue to industrialize, there is also a heightened demand for reliable electricity, which is accelerating the expansion of the power grid system market.
Regionally, North America and Europe lead the Power Grid System Market due to established infrastructure, favorable regulatory environments, and significant investments in smart grid technologies. North America benefits from government-led initiatives aimed at improving energy efficiency and grid reliability, while Europe is driven by stringent environmental regulations and commitments to renewable energy targets. The Asia-Pacific region is poised to experience substantial growth, attributed to rapid urbanization, population growth, and increasing energy demand in countries like China and India. These nations are investing heavily in power grid infrastructure to meet the rising electricity consumption and to support their growing economies. In contrast, the Middle East and Africa are gradually adopting grid modernization solutions to improve electricity access and reliability in remote areas, albeit at a slower pace compared to other regions.
Market Drivers:
Increasing Demand for Renewable Energy Integration:
The transition towards renewable energy sources is one of the most significant drivers of the Power Grid System Market. As global energy consumption continues to rise, governments and organizations are focusing on reducing carbon emissions and enhancing sustainable energy solutions. Renewable energy sources like solar, wind, and hydropower are being integrated into the existing power grid infrastructure, necessitating substantial upgrades to handle the variable nature of these energy sources. The intermittent power supply from renewables poses challenges to grid stability and reliability, making it essential to modernize grid systems with advanced technologies. This shift not only supports the energy transition but also aligns with various national and international policies aimed at achieving net-zero emissions by mid-century.
Advancements in Smart Grid Technologies:
The evolution of smart grid technologies is another key driver of growth in the Power Grid System Market. Smart grids incorporate digital communication, automation, and data analytics to improve the efficiency and reliability of power distribution. Technologies like advanced metering infrastructure (AMI), automated demand response (ADR), and grid management software enable real-time monitoring, which optimizes energy use and minimizes losses. These innovations help utilities better manage energy loads, prevent outages, and enhance the customer experience by providing more accurate billing and greater control over electricity usage. The deployment of smart grid solutions also opens up new opportunities for utilities to integrate renewable energy resources more effectively and to meet future demand with greater resilience.
Government Initiatives and Investments in Grid Modernization:
Government initiatives and funding play a crucial role in accelerating the development of power grid systems. Many governments worldwide have launched programs and policies that encourage the modernization of aging infrastructure and support the integration of clean energy. These programs often include grants, subsidies, and tax incentives to facilitate the deployment of smart grid technologies and energy storage solutions. In regions such as North America and Europe, government-led efforts have been instrumental in upgrading transmission and distribution networks. For example, the U.S. Department of Energy has allocated $13 billion for grid modernization projects, including the Grid Resilience and Innovation Partnerships (GRIP) Program, which includes a $10.5 billion investment to enhance grid flexibility and resilience, and a $2.2 billion investment in the nation’s grid for eight projects across 18 states. Emerging markets in Asia-Pacific are making significant investments to expand their grid capacity to accommodate growing urban populations. Such initiatives not only improve grid reliability but also provide a more robust platform for energy transition efforts, bolstering the overall growth of the market.
Rising Energy Demand in Emerging Economies:
Emerging economies, particularly in the Asia-Pacific, Latin America, and Africa regions, are witnessing rapid industrialization and urbanization, leading to a substantial rise in energy demand. Countries like China and India are experiencing significant population growth and urban development, which, in turn, increases the demand for reliable and efficient electricity supply. These nations are investing heavily in grid infrastructure to support economic growth and ensure energy access in both urban and rural areas. For instance, India’s Ministry of Power reported that the country’s total installed power generation capacity has increased by approximately 80% over the last decade, reaching 4,46,190 MW (4.46 GW) in June 2024. Additionally, as industries expand and new businesses emerge, there is a heightened need for resilient power grid systems to prevent outages and minimize downtime. This growing energy demand in emerging markets presents a considerable opportunity for power grid system providers, as governments and private companies look to enhance their grid capabilities and ensure a stable power supply.
Market Trends:
Adoption of Digitalization and Automation in Grid Management:
Digitalization and automation have become pivotal trends in the Power Grid System Market. Utilities are increasingly adopting digital technologies to enhance grid efficiency, optimize energy distribution, and minimize operational costs. Advanced data analytics, machine learning, and Internet of Things (IoT) solutions enable real-time monitoring of grid performance and help in predictive maintenance. By using automation tools, grid operators can swiftly identify and respond to potential issues, reducing downtime and ensuring a more reliable power supply. The integration of these technologies also enhances grid resilience, making it easier to manage the fluctuating demands and variable supply associated with renewable energy sources. The trend towards digitalized grid management is set to transform traditional power grids into smarter, more flexible, and efficient systems.
Expansion of Energy Storage Solutions:
Energy storage is becoming an integral component of the Power Grid System Market, driven by the need to manage renewable energy’s variable output and ensure a stable power supply. Battery energy storage systems (BESS), particularly lithium-ion batteries, are widely deployed to store surplus energy generated from solar and wind power. For example, Tesla’s Megapack has been deployed in various projects, with each unit providing a storage capacity of 3.9 MWh. These systems allow for energy to be stored during periods of low demand and dispatched when demand peaks, helping to balance the grid and enhance energy reliability. Moreover, advancements in battery technology are improving storage capacity and reducing costs, making large-scale energy storage solutions increasingly feasible. This trend is expected to continue as utilities seek to integrate more renewable energy into the grid, providing greater flexibility and supporting grid stability in the face of fluctuating energy demands
Growing Emphasis on Decentralized Energy Systems:
Another prominent trend in the Power Grid System Market is the shift towards decentralized energy systems. Distributed energy resources (DERs), such as rooftop solar panels, microgrids, and community energy storage, are gaining traction as they offer localized power generation and reduce dependency on centralized grids. Decentralized systems provide enhanced energy security, as they are less vulnerable to large-scale outages and offer a more reliable power supply to remote and underserved areas. This trend aligns with the growing demand for sustainability, as DERs often rely on renewable energy sources. For instance, EY reported that decentralized energy systems are critical for boosting global energy resilience and integrating renewable energy sources. The increase in decentralized systems also necessitates advanced grid management solutions to coordinate the flow of power across both central and distributed sources. As this trend continues, it is reshaping the structure of traditional power grids and promoting a more resilient, adaptable energy landscape.
Implementation of Grid Modernization Programs Worldwide:
Grid modernization is a crucial trend that is shaping the future of the Power Grid System Market. Around the world, governments and utilities are investing in modernizing grid infrastructure to improve efficiency, reliability, and sustainability. These initiatives often involve upgrading aging transmission and distribution networks, implementing advanced sensors, and deploying real-time monitoring systems. Grid modernization programs are particularly prominent in developed regions, such as North America and Europe, where utilities seek to enhance energy efficiency and integrate renewable energy seamlessly. In emerging economies, modernization efforts focus on expanding grid access to underserved communities and bolstering grid capacity to meet rising energy demands. As grid modernization gains momentum, it is expected to drive further advancements in power grid technology, fostering a more interconnected and resilient global energy system.
Market Restraints and Challenges:
High Costs of Infrastructure Upgrades:
One of the main challenges in the Power Grid System Market is the substantial cost associated with upgrading existing grid infrastructure. Modernizing power grids to incorporate renewable energy sources, digital technologies, and energy storage solutions requires significant financial investment. These expenses often extend beyond the initial cost of equipment to include installation, maintenance, and workforce training. For utilities and governments, securing the necessary funding can be challenging, particularly in emerging markets where financial resources may be limited. These high costs can slow down the pace of grid modernization projects, affecting the market's overall growth and development.
Cybersecurity and Data Privacy Concerns:
As power grids become increasingly digital and interconnected, cybersecurity risks are a growing concern. The integration of IoT devices, smart meters, and automated control systems exposes power grids to potential cyber threats that could disrupt energy supply and compromise data privacy. Utilities must invest in robust cybersecurity measures to protect against cyber-attacks, which can be both costly and complex. Additionally, regulatory compliance regarding data protection varies by region, creating challenges for utilities operating in multiple countries. These cybersecurity and data privacy concerns pose a significant restraint to the adoption of digital solutions within the Power Grid System Market.
Technical Challenges in Renewable Energy Integration:
While renewable energy integration is a driving force in the Power Grid System Market, it also presents notable technical challenges. The variable and intermittent nature of renewable sources, such as solar and wind power, can lead to grid instability and require sophisticated grid management strategies. Integrating renewables into the grid demands advanced technologies and energy storage systems to balance supply and demand effectively. Furthermore, existing grid infrastructure in many regions is not equipped to handle the increased complexity associated with distributed energy resources. These technical challenges can hinder the seamless integration of renewable energy, limiting the grid's ability to support a higher percentage of clean energy sources.
Regulatory and Policy Uncertainties:
Regulatory and policy uncertainties create additional challenges in the Power Grid System Market. Governments and regulatory bodies play a crucial role in shaping the energy landscape, and changes in policies can significantly impact grid modernization efforts. For example, shifts in energy policy, renewable energy subsidies, or environmental regulations can affect the financial viability of grid projects. Inconsistent or unpredictable regulatory environments can discourage investments and delay project implementation, creating barriers for utilities and companies looking to expand their grid capabilities. These uncertainties contribute to market restraint, as stakeholders face challenges in aligning their strategies with evolving policy frameworks.
Market Segmentation Analysis:
The Power Grid System Market is segmented based on components, depth, grid type, technology, application, and end-user, each addressing unique needs and contributing to the market's diverse growth landscape.
By Components, the market comprises cables, variable speed drives, transformers, switchgears, and others, including connectors, actuators, sensors, and penetrators. Cables and transformers are crucial for effective energy transmission and distribution, while switchgears and variable speed drives support efficient energy management and grid stability. This segment is critical for grid modernization, enabling seamless energy flow across the power infrastructure.
By Depth, the market is divided into shallow water and deepwater segments, particularly relevant for subsea power grids, where cables and connectors are essential for underwater energy transmission. The deepwater segment, in particular, is seeing growth with increased offshore wind installations and subsea grid expansion.
By Grid Type, the transmission and distribution grids form the market’s backbone. The transmission grid focuses on high-voltage power delivery over long distances, whereas the distribution grid is essential for lower-voltage power distribution to end users. Investments in both grid types are driven by a need for reliable, stable, and efficient energy delivery systems.
By Technology, conventional and smart grids segment the market. The smart grid segment is growing rapidly due to advancements in digitalization and automation, enabling real-time data collection, predictive maintenance, and enhanced energy efficiency. Conventional grids remain essential, particularly in regions where modernization is ongoing.
By Application, the market includes captive generation, wind power, and others, such as tidal and solar power, as well as diesel and gas-based floating power plants. Renewable energy applications, especially wind and solar power, are experiencing significant growth due to the global push towards cleaner energy sources.
By End User, the market is segmented into utility, industrial, commercial, and residential sectors. Utilities dominate the market due to large-scale energy needs and infrastructure requirements, while the industrial and commercial sectors also invest heavily in reliable and resilient grid systems. The residential sector is growing with increased adoption of smart grid technology, enabling efficient energy management at home.
Segmentation:
By Components
- Cables
- Variable Speed Drives
- Transformers
- Switchgears
- Others (connectors, actuators, sensors, and penetrators)
By Depth
- Shallow Water
- Deepwater
By Grid Type:
- Transmission Grid
- Distribution Grid
By Technology:
- Conventional Grid
- Smart Grid
By Application
- Captive Generation
- Wind Power
- Others (tidal power, solar power, and diesel & gas based floating power plants)
By End User:
- Utility
- Industrial
- Commercial
- Residential
- North America
- US
- Canada
- Mexico
- Europe
- Germany
- France
- UK
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
Regional Analysis:
North America
North America holds a prominent share of the Power Grid System Market, accounting for approximately 25% of the global market. The region’s market is driven by the United States and Canada, where substantial investments are being made to modernize aging grid infrastructure and enhance grid resiliency. North America is a leader in smart grid technology adoption, with numerous government initiatives focused on improving energy efficiency and integrating renewable energy sources. The U.S. government’s commitment to achieving energy security and reducing greenhouse gas emissions continues to bolster market growth. Additionally, the growing deployment of electric vehicles (EVs) in the region places further emphasis on upgrading grid infrastructure to handle increased electricity demands.
Europe
Europe holds around 20% of the global Power Grid System Market share, propelled by strong regulatory support for renewable energy integration and grid modernization efforts. Countries such as Germany, the United Kingdom, and France are at the forefront, driven by stringent environmental regulations and ambitious climate goals. The European Union's emphasis on achieving net-zero emissions by 2050 has accelerated investments in smart grid technologies, energy storage solutions, and decentralized energy systems. Moreover, Europe’s focus on offshore wind energy, particularly in the North Sea, drives the demand for subsea power grids and related infrastructure, which is crucial for connecting offshore renewable projects to the main grid.
Asia-Pacific
The Asia-Pacific region dominates the Power Grid System Market, with a significant share of around 35%. This dominance is due to rapid urbanization, industrialization, and rising energy demand in major economies like China, India, and Japan. China, in particular, is investing heavily in grid expansion and modernization to support its ambitious renewable energy targets. India's growing energy demand and focus on enhancing electricity access in rural areas contribute to regional growth. Asia-Pacific also sees substantial investments in smart grid projects and the integration of renewable energy sources. As the region experiences robust economic growth, the need for reliable and efficient power grid infrastructure continues to drive market expansion.
Latin America
Latin America accounts for approximately 10% of the global market share, with Brazil and Mexico leading the region’s power grid investments. The region is increasingly adopting renewable energy sources, such as solar and wind power, necessitating grid modernization to manage distributed energy generation. Latin America faces challenges related to aging infrastructure and frequent power outages, making investments in resilient grid systems a priority. Additionally, government incentives and policies promoting renewable energy are further propelling market growth in this region.
Middle East & Africa
The Middle East & Africa hold around 10% of the global Power Grid System Market. The market in this region is characterized by efforts to improve electricity access in remote areas and to support urbanization in rapidly growing economies. Countries like Saudi Arabia and the United Arab Emirates are investing in grid infrastructure to support economic diversification plans. In Africa, grid modernization efforts focus on enhancing energy access, as many countries still face significant electricity shortages. The Middle East is also exploring renewable energy projects, such as solar power, to diversify its energy mix, driving the demand for advanced grid solutions.
Key Player Analysis:
- ABB (Switzerland)
- Aker Solutions ASA(Norway)
- Apar Industries (India
- Baker Hughes (US)
- Deep C (Norway
- DEME (Denmark)
- Furukawa Electric Co., Ltd. (Japan)
- General Electric (US)
- Hitachi Energy (Switzerland
- Intertek Group (UK)
- J+S Subsea (UK)
- LS Cable & System (South Korea)
- Nexans (France)
- NKT (Denmark)
- Oceaneering International (US)
- Prysmian Group (Italy)
- Schlumberger (US
- Schneider Electric (France)
- Siemens Energy (Germany)
- SSG Cable (China)
- Sumitomo Electric Industries, Ltd. (Japan)
- TE Connectivity (Switzerland)
- TechnipFMC (UK)
- Teledyne Marine (US)
- ZTT (China)
Competitive Analysis:
The Power Grid System Market is highly competitive, with major players focusing on innovation, strategic partnerships, and mergers to maintain their market position. Key companies, including ABB Ltd., Siemens AG, General Electric, Schneider Electric, and Hitachi Energy, dominate the market by offering a comprehensive range of grid solutions and advanced technologies. These companies leverage their extensive experience in grid infrastructure and technology development to provide end-to-end solutions, from transmission and distribution to smart grid technologies. Additionally, regional players and emerging companies are gaining traction by specializing in renewable energy integration, energy storage solutions, and digital grid technologies. Intense competition is driven by the increasing demand for grid modernization, especially in emerging economies, as well as the global push towards renewable energy. Companies are continuously investing in R&D to develop efficient, cost-effective solutions to meet evolving energy demands and adhere to environmental regulations, enhancing the market’s overall competitiveness.
Recent Developments:
- In January 2022, Petrobras awarded TechnipFMC a subsea EPCI (Engineering, Procurement, Construction, and Installation) project for its Bzios 6 field (Module 7), signifying a greenfield expansion in Brazil's pre-salt region. The scope includes the supply of flexible and rigid pipelines, umbilicals, pipe end connectors, stiff jumpers, umbilical terminal components, and an anchoring device.
- In the same month, South Fork Wind-a partnership between Ørsted and Eversource-awarded Nexans a contract under a framework agreement to produce approximately 110 kilometers of high-voltage offshore cables. This project incorporates a three-phase 138 kV high-voltage alternating current (HVAC) subsea export cable, combined with two fiber optic cables, aimed at delivering 132 megawatts of electricity to Long Island, New York.
- In February 2022, Prysmian Group announced plans to open a new submarine coaxial cable manufacturing facility at the Brayton Point site in Massachusetts, US. This state-of-the-art factory will enable Prysmian to meet the rising demand for subsea cable solutions across the US market.
- In the same month, ABB and OneSubsea signed an agreement for Shell’s Ormen Lange project, which includes OneSubsea’s multi-stage subsea compression technology. Under this agreement, ABB will provide subsea converters and variable speed drives to power the underwater compressors, enhancing the project’s efficiency and reliability.
Market Concentration & Characteristics:
The Power Grid System Market is moderately concentrated, with a mix of well-established global players and numerous regional and local companies. Major players such as Siemens AG, ABB Ltd., General Electric, Schneider Electric, and Hitachi Energy lead the market, holding a significant share due to their extensive product portfolios, global reach, and advanced technological capabilities. The market is characterized by high barriers to entry due to the capital-intensive nature of power grid projects and the need for specialized expertise. Furthermore, companies focus heavily on innovation, with ongoing investments in research and development to drive advancements in smart grid technology, renewable energy integration, and energy storage solutions. Given the increasing demand for grid modernization and the rapid adoption of digital technologies, the market also exhibits characteristics of continuous innovation, competitive pricing, and a strong emphasis on strategic partnerships to meet evolving global energy needs and sustainability goals.
Report Coverage:
The research report offers an in-depth analysis based on By Components, By Depth, By Grid Type, By Technology, By Application and By End User. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The Power Grid System Market is expected to experience steady growth due to increasing global energy demand and the shift towards renewable energy sources.
- Technological advancements in smart grids will drive market innovation, improving efficiency and real-time monitoring.
- Expansion of renewable energy integration, particularly solar and wind, will boost demand for grid modernization projects.
- Rising investments in energy storage solutions will enhance grid stability and address challenges associated with renewable energy intermittency.
- Government-led initiatives for grid modernization and infrastructure development will propel growth in both developed and emerging markets.
- The adoption of digital technologies, such as IoT and AI, will support predictive maintenance and enhance grid resilience.
- Increasing focus on decentralization will encourage the development of microgrids and distributed energy resources (DERs).
- Strong emphasis on cybersecurity will drive investment in protective technologies for digital grid systems.
- Growing urbanization in Asia-Pacific and Latin America will expand grid capacity to meet rising electricity needs.
- Regional collaborations and strategic partnerships will foster innovation and help companies meet sustainability goals.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Renewable Energy Integration
The global shift towards renewable energy sources like solar and wind is driving the need for modernized power grids capable of handling intermittent supply and maintaining grid stability, thus fueling investments in advanced grid systems.
Advancements in Smart Grid Technologies
The adoption of digital communication, automation, and real-time data analytics in smart grids is improving energy efficiency, enabling predictive maintenance, and supporting the integration of distributed energy resources, which accelerates market growth.
Government Initiatives and Grid Modernization Funding
Substantial government investments and policy support for upgrading aging infrastructure and enhancing grid resiliency are propelling the deployment of new grid technologies and energy storage solutions worldwide.
Rising Energy Demand in Emerging Economies
Rapid industrialization and urbanization in countries such as China and India are increasing electricity demand, prompting significant investments in expanding and modernizing power grid infrastructure to ensure reliable supply.
Expansion of Energy Storage Solutions
The growing need to balance variable renewable generation with demand is driving the deployment of large-scale battery energy storage systems, which are essential for grid flexibility and reliability, further supporting market expansion.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected growth rate of the Power Grid System Market?
What will be the market size by 2032?
Which regions lead the Power Grid System Market?
What challenges does the Power Grid System Market face?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By End User
- 1.2.1 Utility
- 1.2.2 Industrial
- 1.2.3 Commercial
- 1.2.4 Residential
- 1.3 By Components
- 1.3.1 Cables
- 1.3.2 Variable Speed Drives
- 1.3.3 Transformers
- 1.3.4 Switchgears
- 1.3.5 Others (connectors, actuators, sensors, and penetrators)
- 1.4 By Technology
- 1.4.1 Conventional Grid
- 1.4.2 Smart Grid
- 1.5 By Application
- 1.5.1 Captive Generation
- 1.5.2 Wind Power
- 1.5.3 Others (tidal power, solar power, diesel & gas based floating power plants)
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 11,677 million → 2032: USD 27,104.64 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Power Grid System Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Power Grid System Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Power Grid System Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Power Grid System Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Power Grid System Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Power Grid System Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Power Grid System Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Power Grid System Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 11,677 million → 2032: USD 27,104.64 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Power Grid System Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By End User - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Utility
- 12.3.7.2 Industrial
- 12.3.7.3 Commercial
- 12.3.7.4 Residential
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Components - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Cables
- 12.4.7.2 Variable Speed Drives
- 12.4.7.3 Transformers
- 12.4.7.4 Switchgears
- 12.4.7.5 Others (connectors, actuators, sensors, and penetrators)
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Technology - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Conventional Grid
- 12.5.7.2 Smart Grid
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 By Application - Market Size and Forecast, 2024-2032
- 12.6.1 Segment Definition and Scope
- 12.6.2 Historical Market Size
- 12.6.3 Revenue Forecast, 2024-2032
- 12.6.4 Volume Forecast, 2024-2032
- 12.6.5 Base-Year Market Share, 2024
- 12.6.6 Segment CAGR and Growth Drivers
- 12.6.7 Subsegment Market Size and Forecast
- 12.6.7.1 Captive Generation
- 12.6.7.2 Wind Power
- 12.6.7.3 Others (tidal power, solar power, diesel & gas based floating power plants)
- 12.6.8 Subsegment Pricing and Adoption Trends
- 12.6.9 Leading Suppliers and Competition
- 12.6.10 Regional Demand and Opportunities
- 12.7 Segment Growth Comparison
- 12.8 Segment Attractiveness and Priority Matrix
Chapter 13 Global Power Grid System End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Power Grid System Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Power Grid System Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Power Grid System Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 ABB
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 Siemens Energy
- 18.4 General Electric
- 18.5 Schneider Electric
- 18.6 Hitachi Energy
- 18.7 Prysmian Group
- 18.8 Nexans
- 18.9 LS Cable & System
- 18.10 Sumitomo Electric Industries
- 18.11 Baker Hughes
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

