
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Pressure Ulcer Treatment Products Market Size 2024 | USD 5,660 million |
| Pressure Ulcer Treatment Products Market, CAGR | 9.61% |
| Pressure Ulcer Treatment Products Market Size 2032 | USD 8,852.36 million |
Market Overview:
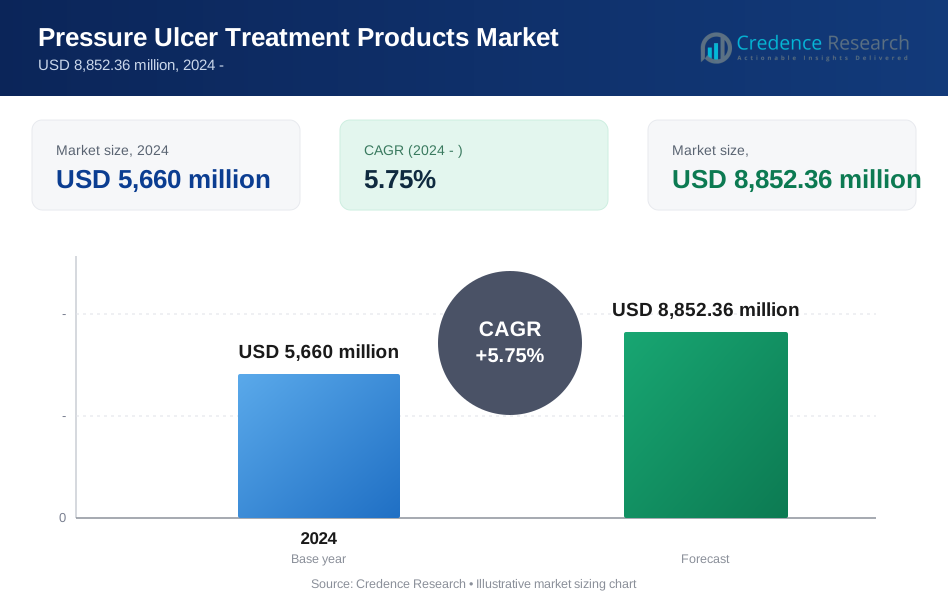
The global Pressure Ulcer Treatment Products Market is projected to experience substantial growth, expanding from USD 5,660 million in 2024 to an estimated USD 8,852.36 million by 2032, with a robust CAGR of 5.75% during the forecast period. This growth underscores the increasing awareness and adoption of advanced treatment options for pressure ulcers across healthcare settings. An aging population, higher incidence of chronic conditions, and heightened focus on patient care have driven the demand for more effective and preventive pressure ulcer treatments, contributing to the steady market growth.
Key drivers of this market include advancements in medical technology, a growing prevalence of chronic illnesses like diabetes, and a rising elderly population, which is particularly susceptible to pressure ulcers. Furthermore, the development of innovative products, such as specialized mattresses, dressings, and wound care devices, has enhanced treatment outcomes, reducing patient discomfort and accelerating healing times. Government initiatives and increased healthcare spending further propel the adoption of these products, emphasizing better quality care and management for bedridden and elderly patients.
Regionally, North America leads the market due to high healthcare expenditure, a well-established healthcare infrastructure, and a rising number of pressure ulcer cases. Europe closely follows, with significant contributions from countries with advanced healthcare systems, such as Germany and the UK. The Asia-Pacific region is anticipated to witness the fastest growth over the forecast period, driven by a large aging population in countries like Japan and China, coupled with increasing investments in healthcare infrastructure. Emerging economies in Latin America and the Middle East are also expected to present lucrative opportunities due to rising awareness and healthcare improvements, positioning these regions as potential growth areas in the near future.
Market Drivers:
Aging Population and Increased Prevalence of Chronic Conditions:
One of the primary drivers of the Pressure Ulcer Treatment Products Market is the aging global population, particularly in developed regions. With individuals aged 65 and above expected to comprise over 16% of the global population by 2050, as projected by the World Health Organization, the demand for specialized care and pressure ulcer prevention products is set to rise significantly. Older adults are at a higher risk for pressure ulcers due to limited mobility and the prevalence of chronic conditions such as diabetes, cardiovascular diseases, and obesity. This demographic trend creates a sustained need for effective pressure ulcer management and treatment solutions.
Technological Advancements and Product Innovation:
Rapid technological advancements and ongoing product innovation drive the growth of the pressure ulcer treatment sector. Leading companies are focusing on developing high-performance products like smart beds, dynamic support surfaces, and antimicrobial dressings. For instance, Hill-Rom Holdings, Inc., a leader in medical technologies, introduced the Hillrom Centrella Smart+ Bed System, equipped with sensors to detect patient movement and pressure, thus helping healthcare providers to monitor patients’ risk factors and improve care efficiency. Such innovations not only improve patient outcomes but also increase the adoption of pressure ulcer treatment products in hospitals and home healthcare settings.
Growing Healthcare Expenditure and Government Initiatives:
Increased healthcare spending by governments worldwide is another critical driver of market growth. Countries such as the United States allocate significant resources toward wound care and management. For instance, Medicare alone spends approximately USD 20 billion annually on wound treatment, including pressure ulcers, according to the Agency for Healthcare Research and Quality. Government-led initiatives to reduce pressure ulcer incidence through better hospital practices and funding for preventive solutions highlight the growing prioritization of patient care quality, leading to broader product adoption in healthcare facilities.
Rising Awareness and Focus on Quality of Care:
The rising awareness among healthcare providers, caregivers, and patients about the risks associated with untreated pressure ulcers further bolsters the demand for effective treatment products. Educational campaigns, both at institutional and public levels, emphasize preventive care and patient mobility as key factors in managing pressure ulcer risks. As a result, hospitals and care facilities are increasingly adopting advanced solutions to enhance patient safety and satisfaction. This trend aligns with broader shifts toward value-based care, where patient outcomes and experience drive healthcare decisions, further fostering market growth.
Market Trends:
Shift Toward Preventive Solutions and Early Intervention:
A major trend in the Pressure Ulcer Treatment Products Market is the increasing focus on preventive solutions and early intervention strategies. Hospitals and healthcare providers are investing in products that can help detect early signs of pressure ulcers to avoid severe cases and reduce treatment costs. For instance, Stryker Corporation’s ProCuity Bed Series, designed with integrated pressure sensors, allows for continuous patient monitoring, helping to identify patients at risk and apply preventive measures early. This shift toward preventive care aligns with healthcare providers' goals to improve patient outcomes while minimizing hospital readmissions due to pressure ulcers.
Adoption of Smart Technologies in Patient Care:
The integration of smart technologies, including AI-driven solutions and IoT-enabled devices, is transforming the pressure ulcer treatment landscape. Companies are introducing connected devices that monitor patient positioning and skin conditions, sending real-time data to healthcare providers. For example, Leaf Healthcare developed a wearable sensor that tracks patient movement and alerts caregivers to reposition patients to prevent pressure ulcers. Such advancements enhance patient safety and provide valuable data to healthcare professionals, contributing to more efficient and data-driven care management.
Increasing Demand for Home Healthcare and Remote Monitoring:
With the rising number of elderly patients preferring to receive care at home, the demand for pressure ulcer treatment products in home healthcare settings is growing. Remote monitoring tools and portable pressure-relief mattresses are becoming popular among home caregivers and families. For instance, Invacare, a leading manufacturer of home healthcare products, has seen an increase in demand for its pressure-reducing mattresses designed for home use. This trend is further fueled by reimbursement policies in certain regions that cover home care equipment, making these solutions more accessible and affordable for patients.
Emphasis on Sustainable and Biocompatible Materials:
Sustainability in healthcare products is gaining traction, with manufacturers focusing on eco-friendly and biocompatible materials for wound care and pressure ulcer prevention. For instance, Smith & Nephew, a prominent player in wound care, has developed biocompatible wound dressings with lower environmental impact. This trend is driven by regulatory pressures to reduce medical waste and by a growing consumer preference for sustainable products. The emphasis on sustainable materials in pressure ulcer treatment reflects the healthcare industry’s commitment to environmental responsibility without compromising product efficacy.
Market Challenges Analysis:
High Treatment Costs and Limited Reimbursement Policies:
One of the primary restraints in the Pressure Ulcer Treatment Products Market is the high cost associated with advanced treatment products. Specialized mattresses, smart sensors, and wound care products can be costly, often making them less accessible, particularly for smaller healthcare facilities and lower-income patients. While reimbursement policies in countries like the United States and parts of Europe cover certain treatment costs, limitations remain. For instance, the Centers for Medicare & Medicaid Services (CMS) restricts reimbursement for specific pressure ulcer treatments, creating a financial burden for patients who require ongoing, intensive care.
Lack of Awareness and Skilled Caregivers:
In many regions, especially in developing economies, a lack of awareness about pressure ulcer prevention and treatment hampers market growth. Inadequate training for caregivers on proper patient positioning, skin assessment, and preventive measures can result in delayed diagnoses and worsen patient outcomes. According to the World Health Organization (WHO), low awareness of pressure ulcer management practices is particularly prevalent in rural and underserved areas, posing a challenge for effective treatment.
Regulatory Hurdles in Product Approval:
Strict regulatory requirements for medical devices, particularly in developed regions, present a significant challenge for market players. Pressure ulcer treatment products must meet rigorous standards and pass multiple rounds of testing to receive approval from regulatory bodies, such as the U.S. Food and Drug Administration (FDA) and the European Medicines Agency (EMA). These stringent requirements often delay product launches and increase costs, slowing innovation and limiting the availability of new treatments.
Inconsistent Standards in Healthcare Facilities:
Another challenge is the inconsistency in pressure ulcer prevention protocols across healthcare facilities. While larger hospitals may have dedicated wound care teams and standardized practices, smaller facilities often lack such resources. The U.S. Agency for Healthcare Research and Quality (AHRQ) notes that variability in care standards contributes to differing patient outcomes, highlighting the need for consistent protocols across healthcare settings to address pressure ulcer management effectively.
Market Segmentation Analysis:
By Type
The Pressure Ulcer Treatment Products Market is segmented by type into wound care dressings, mattresses, and support surfaces, among others. Wound care dressings, such as foam and hydrocolloid dressings, play a crucial role in managing ulcerations and promoting healing, making them a dominant segment. Mattresses and specialized support surfaces, including low-air-loss and alternating pressure mattresses, are increasingly in demand for their effectiveness in redistributing pressure and preventing ulcer formation, particularly in hospital settings.
By Technology
Segmentation by technology includes traditional and advanced pressure ulcer treatment technologies. Traditional methods, such as basic wound dressings and positioning techniques, are widely used due to their cost-effectiveness. However, advanced technologies, such as air-fluidized therapy and powered overlays, are gaining traction as they offer superior outcomes in prevention and treatment. Technological advancements have introduced smart sensor-equipped mattresses and IoT-enabled support surfaces, which provide real-time monitoring and assist in early intervention, reducing ulcer severity and duration of hospital stays.
By End User
The market is also segmented by end users, including hospitals, home healthcare, and long-term care facilities. Hospitals represent the largest end-user segment, as they serve a high volume of patients requiring preventive care and treatment for pressure ulcers. Long-term care facilities, catering primarily to elderly and bedridden patients, also constitute a significant market share. The home healthcare segment is expanding rapidly, driven by a rising preference for at-home care and increased accessibility to portable pressure-relief products suitable for non-hospital settings.
Segmentations:
By Product Type- Wound Care Dressings
- Active Wound Care Therapies
- Wound Care Devices
- Hospitals
- Community Health Centres
- Homecare Centres
- Others
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
North America
North America holds the largest market share in the global Pressure Ulcer Treatment Products Market, driven by high healthcare expenditure, advanced medical infrastructure, and an aging population. The United States, in particular, has a strong demand for pressure ulcer treatment products, as approximately 2.5 million individuals are affected by pressure ulcers annually, according to the Agency for Healthcare Research and Quality (AHRQ). Increased adoption of advanced wound care solutions, coupled with government initiatives aimed at reducing hospital-acquired pressure ulcers, supports market growth in this region. Canada also contributes to the market with its well-developed healthcare system and rising focus on preventive care. Together, the North American market represents around 35% of the global market share.
Europe
Europe follows North America with a substantial share in the Pressure Ulcer Treatment Products Market, accounting for approximately 28% of the global market. The demand in this region is driven by a high prevalence of chronic diseases and a well-established healthcare system that emphasizes patient safety. Countries like the United Kingdom, Germany, and France invest heavily in pressure ulcer prevention and management to improve healthcare outcomes and reduce costs associated with long-term treatment. The National Health Service (NHS) in the UK, for example, has implemented initiatives to reduce pressure ulcer cases through better care protocols and product adoption. Government regulations, such as strict policies for hospital-acquired pressure ulcers, have further accelerated the adoption of preventive products in European healthcare settings.
Asia-Pacific
The Asia-Pacific region is anticipated to experience the fastest growth over the forecast period, with an estimated market share of around 22%. This growth is largely attributed to the region’s increasing elderly population, especially in countries like Japan and China, which leads to a higher demand for pressure ulcer treatment and prevention products. Additionally, rising healthcare investments and improvements in medical infrastructure are expected to boost the market in this region. As awareness of pressure ulcer prevention grows and disposable income increases, healthcare providers in the Asia-Pacific region are adopting advanced treatment products, including specialized mattresses and wound care dressings, for both hospitals and home care settings. Emerging economies, such as India, are expected to witness increased market penetration as healthcare access expands.
Latin America, Middle East, and Africa
Latin America, the Middle East, and Africa collectively represent around 15% of the global Pressure Ulcer Treatment Products Market. While these regions currently have a smaller market share, they present significant growth potential due to the gradual improvement in healthcare infrastructure and increasing awareness about pressure ulcer prevention. Brazil and South Africa, in particular, have shown rising demand for wound care products, with the expansion of private healthcare providers contributing to market growth. However, limited resources and slower adoption of advanced technologies in some parts of these regions may constrain market expansion. Government and international efforts to improve healthcare access and quality in these areas could enhance market opportunities over time.
Key Player Analysis:
- Smith & Nephew
- Mölnlycke Health Care
- Hill-Rom Holdings, Inc.
- Stryker Corporation
- Coloplast
- 3M Healthcare
- Cardinal Health
- Invacare Corporation
- Medtronic
- Integra LifeSciences
Competitive Analysis:
The Pressure Ulcer Treatment Products Market is highly competitive, with key players focusing on innovation, product expansion, and strategic partnerships to strengthen their market positions. Companies like Smith & Nephew, Mölnlycke Health Care, and Hill-Rom Holdings leverage advanced technologies to enhance product effectiveness, including smart sensor-equipped mattresses and biocompatible wound dressings. Firms such as Stryker Corporation and Medtronic have also invested in IoT-enabled devices, enabling real-time monitoring and predictive care for pressure ulcer prevention. Many players, including Cardinal Health and Coloplast, are expanding their presence in emerging markets to capture growth opportunities fueled by rising healthcare expenditure and aging populations. Additionally, competitive dynamics are influenced by mergers and acquisitions, as companies seek to broaden their product portfolios and geographic reach. Regulatory compliance remains a significant factor, requiring companies to continuously innovate while adhering to stringent standards set by bodies like the FDA and EMA.
Recent Developments:
- Mölnlycke Health Care launched a new line of wound care products in 2023 that are designed to reduce environmental impact, aligning with its "WeCare" sustainability roadmap. This initiative aims to make its products eco-friendlier without compromising on quality and effectiveness, a key component in Mölnlycke’s efforts to meet the Global Reporting Initiative (GRI) standards.
- Smith & Nephew introduced the RENASYS EDGE Negative Pressure Wound Therapy (NPWT) system in 2023, following FDA 510(k) clearance. This advanced wound care system provides targeted treatment for complex wounds and is part of Smith & Nephew’s broader strategy to expand within the NPWT segment, where they have seen growth opportunities.
- Stryker surpassed $20 billion in sales in 2023, attributing part of its growth to strong demand in wound care and pressure ulcer management products. This milestone reflects the company's commitment to innovation and responsibility, supporting over 150 million patients annually through enhanced products that promote better patient care and safety.
- Hill-Rom Holdings (now part of Baxter) expanded its portfolio in 2022 with the launch of the Centrella Smart+ Bed System, which features advanced pressure ulcer prevention technology. The system monitors patient movement and offers continuous pressure redistribution, helping reduce pressure ulcer risks in hospital settings by ensuring optimal support and comfort.
Market Concentration & Characteristics:
The Pressure Ulcer Treatment Products Market is moderately concentrated, with a mix of established global players and emerging companies. Key players, including Mölnlycke Health Care, Smith & Nephew, and Stryker, dominate the market through extensive product portfolios, advanced technology integration, and robust distribution networks. These companies invest heavily in R&D to introduce innovative solutions, such as smart beds and advanced wound dressings, which enhance treatment efficacy and patient outcomes. Smaller players and new entrants are also making notable advances, focusing on niche areas like sustainable materials and cost-effective solutions to capture untapped segments in emerging markets. High entry barriers, primarily due to stringent regulatory requirements and the need for significant R&D investment, contribute to the market’s concentrated structure, favoring companies with strong financial and operational capacities. This concentration drives competition, encouraging continuous innovation and improvement in pressure ulcer treatment products.
Report Coverage:
The research report offers an in-depth analysis based on Product Type, End User, and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The market is expected to see a steady increase in demand due to a growing elderly population and rising prevalence of chronic diseases globally.
- Innovation in advanced wound care technologies, such as AI-driven smart mattresses and real-time monitoring systems, will continue to shape product development.
- Increased healthcare expenditure in emerging markets will broaden access to pressure ulcer treatment products, encouraging wider adoption.
- Companies are likely to prioritize eco-friendly and sustainable materials, reflecting an industry-wide shift toward environmental responsibility.
- Demand for home healthcare solutions will rise as patients increasingly seek at-home treatment options, driving growth in portable and user-friendly products.
- Partnerships and collaborations among industry players, hospitals, and research institutions will enhance product efficacy and accelerate clinical advancements.
- Regulatory support for quality standards and patient safety will drive adoption of high-performance treatment products across healthcare facilities.
- Growing awareness of pressure ulcer prevention among healthcare professionals and patients will support the market’s expansion in preventive care solutions.
- Advances in digital health will enable remote monitoring and early intervention, reducing the burden on healthcare providers and improving patient outcomes.
- A focus on patient-centred care and value-based healthcare will encourage the adoption of advanced treatment products to reduce pressure ulcer incidence.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Pressure Ulcer Treatment Products Market?
What factors are driving the growth of the Pressure Ulcer Treatment Products Market?
What are some challenges faced by the Pressure Ulcer Treatment Products Market?
Who are the major players in the Pressure Ulcer Treatment Products Market?
Which segment is leading the market share?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Pressure Ulcer Treatment Products Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to the forecast period)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Pressure Ulcer Treatment Products Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (the forecast period) (2024: USD 5,660 million → forecast year: USD 8,852.36 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Pressure Ulcer Treatment Products Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs.
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Pressure Ulcer Treatment Products Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Pressure Ulcer Treatment Products Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Pressure Ulcer Treatment Products Market Drivers
- 3.3 Pressure Ulcer Treatment Products Market Restraints & Challenges
- 3.4 Pressure Ulcer Treatment Products Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Pressure Ulcer Treatment Products Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Pressure Ulcer Treatment Products Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Pressure Ulcer Treatment Products category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Pressure Ulcer Treatment Products Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through the forecast period
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through the forecast period
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Pressure Ulcer Treatment Products Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Pressure Ulcer Treatment Products market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Pressure Ulcer Treatment Products Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Pressure Ulcer Treatment Products Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Pressure Ulcer Treatment Products Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Pressure Ulcer Treatment Products (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Pressure Ulcer Treatment Products Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Pressure Ulcer Treatment Products Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & )
- 7.1.2 Channel Mix Evolution (the forecast period)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through the forecast period
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Pressure Ulcer Treatment Products Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Pressure Ulcer Treatment Products Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Pressure Ulcer Treatment Products Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Pressure Ulcer Treatment Products Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Pressure Ulcer Treatment Products Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Pressure Ulcer Treatment Products Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Pressure Ulcer Treatment Products Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
