
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
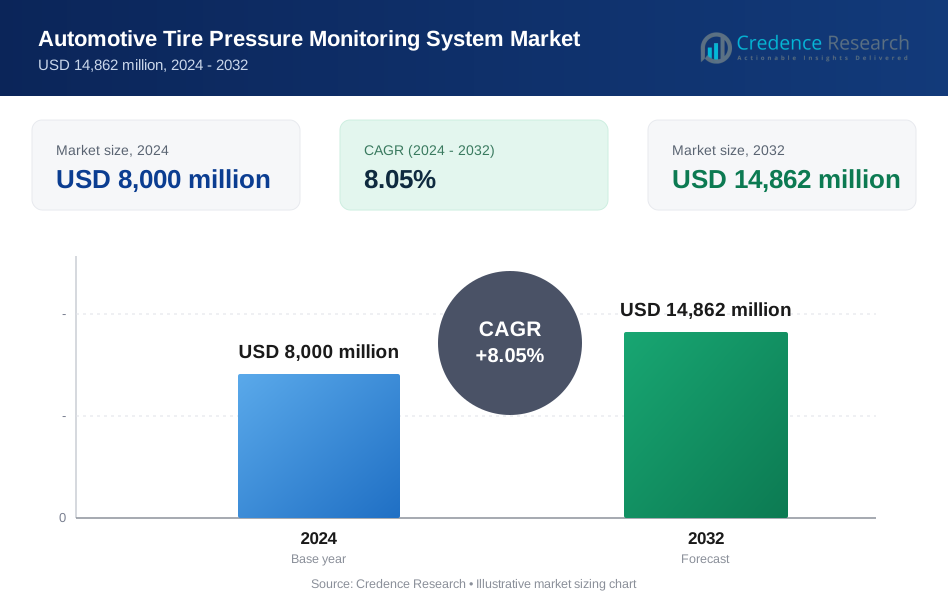
| Automotive Tire Pressure Monitoring System Market Size 2024 | USD 8,000 million |
| Automotive Tire Pressure Monitoring System Market, CAGR | 8.05% |
| Automotive Tire Pressure Monitoring System Market Size 2032 | USD 14,862 million |
Market Overview
The Global Automotive Tire Pressure Monitoring System Market is projected to grow from USD 8,000 million in 2024 to an estimated USD 14,862 million by 2032, with a compound annual growth rate (CAGR) of 8.05% from 2025 to 2032.
Market growth is primarily fueled by stringent safety regulations, especially in North America and Europe, where government bodies mandate the inclusion of TPMS in all new vehicles. The increasing number of road accidents caused by tire blowouts and under-inflation has heightened the demand for early detection and maintenance solutions. Additionally, rising fuel efficiency concerns and tire longevity considerations are encouraging fleet operators and consumers to invest in TPMS solutions. The trend towards vehicle electrification and intelligent transportation systems is further accelerating TPMS adoption.
Regionally, North America leads the market due to early regulatory implementation and high vehicle safety awareness, followed closely by Europe. The Asia-Pacific region is anticipated to witness the fastest growth during the forecast period, driven by expanding automotive production and rising consumer demand for safety technologies in countries such as China, India, and Japan. Key players operating in the global market include Continental AG, DENSO Corporation, Robert Bosch GmbH, Sensata Technologies, and Huf Hülsbeck & Fürst GmbH & Co. KG.
Market Insights
- The Automotive Tire Pressure Monitoring System Market is projected to grow from USD 8,000 million in 2024 to USD 14,862 million by 2032, at a CAGR of 8.05% from 2025 to 2032.
- Rising safety regulations and mandatory TPMS installation in new vehicles are fueling market expansion across OEM channels globally.
- Increased consumer awareness about tire-related accidents and the importance of vehicle maintenance is driving demand for TPMS solutions.
- The growing adoption of ADAS and smart vehicle technologies is encouraging the integration of advanced TPMS with real-time monitoring capabilities.
- High installation and maintenance costs, particularly for direct TPMS systems, continue to restrain market penetration in cost-sensitive regions.
- North America dominates the global market due to early regulatory enforcement, while Asia-Pacific is expected to witness the fastest growth.
- Europe maintains a strong position in the market due to stringent EU safety mandates and established automotive manufacturing infrastructure.
Market Drivers
Stringent Government Regulations Enforcing Vehicle Safety Standards
The Global Automotive Tire Pressure Monitoring System Market is gaining momentum due to stringent regulatory mandates that require the integration of TPMS in all new vehicles. In regions such as North America and Europe, laws compel manufacturers to equip vehicles with TPMS to reduce road accidents caused by under-inflated tires. These mandates have expanded beyond passenger cars to include light commercial vehicles and heavy trucks. Governments are focused on improving public road safety, which is driving demand for advanced tire monitoring technologies. The enforcement of these regulations ensures consistent market demand, particularly for original equipment manufacturers (OEMs). Emerging economies are also aligning with these safety standards, increasing the scope of market penetration.
- For instance, the U.S. TREAD Act mandates TPMS installation in all passenger vehicles, significantly boosting adoption rates across North America.
Rising Consumer Awareness of Tire Safety and Maintenance
Improved awareness among consumers regarding the risks associated with poorly maintained tire pressure is strengthening TPMS adoption. Drivers now recognize that under-inflated tires not only compromise vehicle control but also increase tire wear and fuel consumption. This awareness is supported by education campaigns and recommendations from automotive service providers. As vehicle owners become more safety-conscious, they show greater interest in technology that enhances real-time tire condition monitoring. It also builds trust in modern vehicle safety systems, encouraging widespread use. Manufacturers are responding to this demand by integrating TPMS into more vehicle models across price segments.
- For instance, over 75% of new passenger vehicles globally now come equipped with TPMS, reflecting widespread acceptance and regulatory influence.
Demand for Fuel Efficiency and Reduced Carbon Emissions
Growing emphasis on fuel efficiency and emissions reduction supports the use of TPMS, which helps maintain optimal tire pressure. Proper inflation minimizes rolling resistance, improving fuel economy and extending tire lifespan. Governments and environmental agencies are promoting technologies that contribute to lower vehicle emissions. TPMS plays a role in achieving these sustainability goals, making it valuable for eco-conscious consumers and fleet managers. It also enables predictive maintenance, which reduces vehicle downtime and operational costs. The technology aligns with broader environmental initiatives across the automotive industry.
Growth of Electrification and Advanced Driver Assistance Systems
The transition to electric vehicles and the adoption of advanced driver assistance systems (ADAS) have created new opportunities for TPMS integration. EV manufacturers prioritize weight reduction and safety, both of which benefit from effective tire pressure monitoring. TPMS complements other intelligent vehicle systems by providing continuous tire condition data to the vehicle’s central system. It supports autonomous functions by maintaining optimal tire performance, ensuring safe navigation. Integration with vehicle telematics further enhances the system’s value by enabling remote diagnostics and monitoring. These advancements are expanding TPMS applications beyond traditional usage scenarios.
Market Trends
Integration of TPMS with Connected Vehicle Technologies
Automakers are increasingly integrating TPMS with vehicle telematics and connected car systems to enhance real-time data monitoring and remote diagnostics. This trend is gaining momentum as OEMs focus on improving driver awareness and vehicle performance through seamless data sharing. Connected TPMS solutions allow users to receive alerts on smartphones and infotainment systems, providing better control over vehicle maintenance. It supports proactive servicing, which reduces the risk of accidents and boosts vehicle longevity. The shift toward software-defined vehicles is also facilitating TPMS upgrades through over-the-air updates. This enhances system functionality and aligns with the evolving digital automotive ecosystem.
- For instance, Volkswagen's Virtus model, launched in 2022, features over 40 advanced sensors, including sophisticated TPMS integration, showcasing the industry's shift toward connected vehicle technologies
Adoption of Battery-Less and Smart Sensor Technologies
Manufacturers are shifting toward battery-less TPMS solutions that rely on energy harvesting to power the sensors. These sensors improve product lifespan and eliminate the need for periodic battery replacements, making them suitable for modern vehicle platforms. Smart TPMS sensors offer more than pressure readings by also monitoring tire temperature and performance trends. It enables predictive analytics, which helps drivers and fleet managers make informed maintenance decisions. Sensor miniaturization and improved durability are also supporting broader adoption across vehicle categories. This trend reflects the industry's focus on sustainable and maintenance-free safety systems.
- For instance, advancements in radio frequency identification (RFID) and energy harvesting technologies are enabling the development of battery-free sensors that transmit data without traditional power sources, driving adoption across automotive applications
Increased Demand in Commercial Vehicle Fleets
Fleet operators are adopting TPMS to minimize downtime, improve safety, and lower operational costs. Tire failures can cause significant disruptions and financial losses in logistics operations, making real-time pressure monitoring critical. The Global Automotive Tire Pressure Monitoring System Market is responding to this need by offering scalable and fleet-compatible solutions. It supports centralized monitoring platforms, allowing fleet managers to track tire performance across multiple vehicles. The commercial segment’s growth is encouraging system providers to offer tailored, rugged TPMS units. Adoption in this segment is expected to accelerate during the forecast period.
Expansion of Aftermarket TPMS Offerings
The aftermarket segment is witnessing robust growth due to rising demand from vehicle owners looking to retrofit TPMS units into older vehicles. Consumers are more inclined to install cost-effective, easy-to-use systems that enhance safety without needing a full vehicle upgrade. It is driving innovation in universal TPMS kits that support various vehicle models. E-commerce platforms and service centers are promoting these products with installation services and maintenance plans. Aftermarket players are also introducing app-based systems to improve user experience. This trend is expanding access to tire monitoring technologies across vehicle segments and income groups.
Market Challenges
High Installation and Maintenance Costs Restrain Market Penetration
The high cost of installing and maintaining tire pressure monitoring systems remains a significant barrier to widespread adoption, particularly in price-sensitive markets. Direct TPMS solutions require individual sensors for each tire, which increases both initial costs and future maintenance expenses. Sensor replacements and recalibration procedures further add to the ownership burden, especially for older vehicles. Budget-conscious consumers and small fleet operators often delay or avoid TPMS upgrades due to these financial concerns. The Global Automotive Tire Pressure Monitoring System Market faces slower adoption in developing regions where vehicle safety investments are secondary to affordability. It limits market expansion beyond premium and mid-segment vehicles.
- For instance, over 10,522 thousand electric vehicles were sold globally in 2022, driving demand for advanced TPMS integration
System Compatibility and Technological Limitations Hinder Integration
TPMS integration can pose compatibility challenges, especially with older vehicle models and aftermarket wheels or tires. Variations in sensor standards and communication protocols may lead to performance issues or system errors. It complicates installation and reduces consumer confidence in aftermarket solutions. TPMS units may also suffer from signal interference, inaccurate readings, or sensor battery failures, impacting reliability. Manufacturers must address these limitations through standardized designs and better interoperability across vehicle platforms. These challenges restrict seamless integration and delay adoption in broader vehicle segments.
Market Opportunities
Expansion of TPMS in Emerging Automotive Markets
The Global Automotive Tire Pressure Monitoring System Market has strong growth potential in emerging economies due to rising vehicle production and increasing awareness of road safety. Governments in countries such as India, Brazil, and Indonesia are implementing new vehicle safety regulations, creating demand for advanced technologies like TPMS. Rapid urbanization and growing middle-class populations are driving higher automotive sales, especially in the passenger vehicle segment. It presents an opportunity for OEMs and suppliers to introduce cost-effective TPMS models tailored to regional needs. Local manufacturing partnerships can further support market entry and pricing competitiveness. These developments position emerging markets as key growth drivers over the forecast period.
Integration with Advanced Mobility and Smart Transportation Systems
The rise of electric vehicles, autonomous driving, and smart city initiatives offers new opportunities for TPMS integration. These applications require precise tire condition data to ensure vehicle efficiency, safety, and system coordination. TPMS can serve as a key component in fleet telematics and predictive maintenance systems, enabling real-time insights and reducing operational disruptions. It supports data-driven mobility solutions where safety and performance are monitored remotely. Companies that innovate with cloud-connected and AI-enabled TPMS platforms can differentiate their offerings in future-ready vehicles. This integration will expand the system’s relevance across evolving transportation ecosystems.
Market Segmentation Analysis
By Type
The Global Automotive Tire Pressure Monitoring System Market is segmented into direct and indirect TPMS. Direct TPMS dominates the market due to its superior accuracy and ability to provide real-time tire pressure readings through individual sensors installed in each tire. It is widely adopted in high-end vehicles and increasingly integrated into mid-range models as costs decline. Indirect TPMS, which relies on wheel speed sensors to estimate pressure deviations, holds a smaller share but remains popular for its lower cost and ease of integration. It appeals to cost-sensitive segments and markets with less stringent regulatory requirements.
By Sales Channel Type
The market is divided into OEM and aftermarket channels. The OEM segment holds the largest share, driven by regulatory mandates requiring TPMS installation in new vehicles across major markets. Manufacturers integrate TPMS during vehicle assembly, ensuring compliance and performance reliability. The aftermarket segment is growing steadily, supported by the demand for retrofitting solutions in older vehicles. Consumers are seeking affordable, easy-to-install TPMS kits, prompting suppliers to expand product offerings through retail and online channels.
By Vehicle Type
Passenger vehicles account for the majority share in the Global Automotive Tire Pressure Monitoring System Market due to their high production volumes and safety feature adoption. TPMS is becoming standard in new passenger cars, driven by consumer demand and regulatory norms. Commercial vehicles represent a growing segment, particularly in fleet operations. It supports operational efficiency, reduces downtime, and enhances road safety, encouraging wider adoption of TPMS across logistics and transportation sectors
Segments
Based on Type
- Direct TPMS
- Indirect TPMS
Based on Sales Channel Type
- OEM
- Aftermarket
Based on Vehicle Type
- Passenger Vehicle
- Commercial Vehicle
Based on Region
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis
North America Automotive Tire Pressure Monitoring System Market
North America holds a significant share of the Automotive Tire Pressure Monitoring System Market, accounting for 31% of the global revenue in 2024. Strict regulatory frameworks, such as the TREAD Act in the U.S., have made TPMS mandatory in all new vehicles, driving strong OEM demand. High consumer awareness and a mature automotive sector support early adoption of safety technologies. It continues to benefit from a large installed base of passenger and commercial vehicles equipped with TPMS. Major automakers and sensor nufacturers are based in the region, further strengthening market presence. The aftermarket segment is also expanding due to retrofitting needs.
Europe Automotive Tire Pressure Monitoring System Market
Europe commands 28% of the global Automotive Tire Pressure Monitoring System Market, backed by stringent EU safety mandates and advanced automotive manufacturing. Countries such as Germany, France, and the UK have adopted regulations requiring TPMS in new vehicles, promoting steady demand. OEM integration dominates the market, with premium vehicle manufacturers leading the trend. It benefits from strong collaboration between automotive and electronics industries, ensuring high-quality sensor production. The region also supports sustainability goals, encouraging TPMS adoption to improve fuel efficiency. Aftermarket demand is growing with the rise in used car ownership.
Asia-Pacific Automotive Tire Pressure Monitoring System Market
Asia-Pacific is the fastest-growing region in the Automotive Tire Pressure Monitoring System Market, contributing 24% of the global share in 2024. Rapid industrialization, increasing vehicle production, and rising safety awareness are driving market expansion. China, Japan, South Korea, and India are key markets with supportive government policies and growing consumer expectations. It is witnessing a shift from optional to mandatory TPMS in new vehicles, particularly in China and India. Local manufacturing and cost-effective technology development are accelerating adoption. OEMs are increasing TPMS integration in compact and mid-range models to meet new safety norms.
Latin America Automotive Tire Pressure Monitoring System Market
Latin America holds a smaller but emerging share of the Automotive Tire Pressure Monitoring System Market, contributing approximately 7% to global revenues. Brazil and Mexico lead the regional demand, supported by expanding automotive production and growing safety concerns. It is experiencing gradual regulatory shifts, which may encourage TPMS adoption in the near future. Market growth is currently driven more by high-end vehicles and fleet operators. Consumer awareness is improving, but cost sensitivity remains a barrier. Aftermarket products are gaining traction among urban vehicle owners.
Middle East and Africa Automotive Tire Pressure Monitoring System Market
The Middle East and Africa region accounts for 5% of the Automotive Tire Pressure Monitoring System Market in 2024, driven by growing urbanization and infrastructure development. Gulf countries like the UAE and Saudi Arabia are investing in road safety and vehicle standards, prompting interest in TPMS. It sees demand mainly from premium vehicle imports and commercial fleets seeking to reduce downtime and enhance safety. Limited regulatory enforcement slows market acceleration, especially in Africa. Rising disposable income and increasing awareness of automotive safety features are expected to create new opportunities. Market penetration remains modest but shows potential.
Key players
- Continental AG
- Denso Corporation
- Sensata Technologies, Inc.
- ZF Friedrichshafen AG
- NXP Semiconductors
- Pacific Industrial
- WABCO
- ATEQ
- DUNLOP Tech GmbH
- NIRA Dynamics AB
- Bartec USA LLC
Competitive Analysis
The Automotive Tire Pressure Monitoring System Market is highly competitive, with key players focusing on innovation, sensor accuracy, and system integration. Companies such as Continental AG, Denso Corporation, and Sensata Technologies lead the market through advanced product development and strategic partnerships with OEMs. It witnesses strong competition among players enhancing wireless communication, battery-free sensors, and real-time data analytics. NXP Semiconductors and ZF Friedrichshafen AG invest in scalable solutions for electric and autonomous vehicles. NIRA Dynamics AB and Bartec USA LLC focus on intelligent algorithms and diagnostics in indirect TPMS. Market participants are expanding their global presence through collaborations, manufacturing footprints, and aftermarket support. Price competitiveness, regulatory compliance, and durability remain critical factors shaping market positioning
Recent Developments
- In May 2025, Denso Corporation announced updates to its North American leadership, enhancing organizational efficiency to meet evolving customer needs.
- On 7 February 2025, NIRA Dynamics AB unveiled the Tread Wear Indicator, a real-time tire health monitoring solution that enhances safety, fuel efficiency, and sustainability.
- In January 2025, Bartec USA LLC announced TPMS promotions for Q1 & Q2 2025, including TPMS tools, sensors, and accessories.
Market Concentration and Characteristics
The Automotive Tire Pressure Monitoring System Market exhibits moderate to high market concentration, with a few dominant players controlling a significant share of the global revenue. It features a strong presence of established automotive suppliers and sensor manufacturers that leverage long-term OEM relationships and extensive distribution networks. The market is characterized by continuous technological advancements, regulatory-driven demand, and high entry barriers due to the need for compliance and precision engineering. Innovation in sensor technology, energy efficiency, and digital connectivity defines product differentiation. Standardization efforts and integration with broader vehicle systems are influencing design priorities. Competitive dynamics are shaped by pricing strategies, product reliability, and regional adaptation.
Report Coverage
The research report offers an in-depth analysis based on Type, Sales Channel Type, Vehicle Type and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The Automotive Tire Pressure Monitoring System Market will continue to expand, driven by stricter global safety regulations and mandatory compliance for new vehicle models. Regulatory bodies in emerging markets are expected to implement TPMS standards, increasing global coverage.
- OEM demand will remain strong as automakers integrate TPMS into a broader suite of safety and telematics systems. Embedded solutions that align with ADAS and EV architectures will gain more traction.
- Direct TPMS will dominate market share due to its higher accuracy and real-time data capabilities. Technological enhancements will reduce sensor costs, making it accessible across more vehicle segments.
- Aftermarket TPMS adoption will accelerate, particularly in developing countries where older vehicles dominate the road. Affordable, retrofit-compatible solutions will boost penetration outside the OEM channel.
- Battery-less TPMS and energy-harvesting technologies will gain popularity due to sustainability concerns and reduced maintenance needs. These innovations will support longer product life cycles and lower operating costs.
- Integration of TPMS with cloud-based platforms and mobile applications will enhance user engagement and vehicle diagnostics. Real-time alerts and remote monitoring will become standard features for fleet and personal vehicle users.
- Electric and autonomous vehicles will offer new growth avenues for TPMS as these platforms require high-precision tire data. Manufacturers will align TPMS development with EV safety and efficiency goals.
- Asia-Pacific will emerge as the fastest-growing regional market due to rising vehicle ownership, regulatory updates, and local manufacturing investments. China and India will lead adoption with expanding safety norms.
- Smart TPMS solutions using AI and predictive analytics will improve vehicle maintenance and operational planning. Advanced algorithms will enable early fault detection, improving safety and reducing downtime.
- Key market players will focus on strategic collaborations, M\&A, and global expansion to strengthen their competitive position. Product customization, sensor miniaturization, and multi-functional designs will differentiate offerings in the evolving landscape.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What was the market size of the Automotive Tire Pressure Monitoring System Market in 2023, and what is the forecast for 2032 along with the CAGR?
What are the main factors driving the growth of the TPMS market?
Which region currently leads the global TPMS market?
Who are the key players in the global TPMS market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue) (Volume Where Applicable)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Automotive Tire Pressure Monitoring System Scope – Segments & Subsegments Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 Industry Classification & Applicable Codes
- 1.5 Currency, Measurement Units & Valuation Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Automotive Tire Pressure Monitoring System Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 8,000 million → 2032: USD 14,862 million)
- 2.1.2 Volume & Revenue – Global Totals (Volume Where Applicable)
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Automotive Tire Pressure Monitoring System Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024 (Volume Where Applicable)
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Automotive Tire Pressure Monitoring System Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Automotive Tire Pressure Monitoring System Market Position in the Broader Industry Value Chain
- 3.1.2 Demand Structure & Purchasing Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Automotive Tire Pressure Monitoring System Market Drivers
- 3.3 Automotive Tire Pressure Monitoring System Market Restraints & Challenges
- 3.4 Automotive Tire Pressure Monitoring System Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Automotive Tire Pressure Monitoring System Value Chain Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.6.1.1 Key Input/Resource 1
- 3.6.1.2 Key Input/Resource 2
- 3.6.1.3 Key Input/Resource 3
- 3.6.2 Midstream – Core Operations & Value Creation
- 3.6.2.1 Operating Model & Process Overview
- 3.6.2.2 Key Operating Locations & Capabilities by Company
- 3.6.3 Downstream – Market Channels & End Users
- 3.6.3.1 Direct Sales & Customer Engagement Channels
- 3.6.3.2 Indirect Sales, Intermediaries & Partner Channels
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Key Inputs, Resources & Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Automotive Tire Pressure Monitoring System Supply Chain Analysis
- 3.8.1 Critical Input & Resource Availability Risk Assessment
- 3.8.2 Supplier & Operational Concentration Risk (Geographic Exposure)
- 3.8.3 Supply & Service Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Automotive Tire Pressure Monitoring System category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Automotive Tire Pressure Monitoring System Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Market Size × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute Revenue Growth Through 2032
- 4.3 Incremental Demand Opportunity
- 4.3.1 By Region – Incremental Demand Through 2032
- 4.3.2 Segment – Incremental Demand
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Priority Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Priority market opportunity scorecards reflect the geographic scope and strategic relevance of the study. Listed markets are indicative and may be adapted to the industry.
Chapter 5. Automotive Tire Pressure Monitoring System Cross-Border Trade & Market Access Analysis
- 5.1 International Trade & Cross-Border Activity Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024) (Volume Where Applicable)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024) (Volume Where Applicable)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Category 1 (Applicable Classification Code)
- 5.2.2 Category 2 (Applicable Classification Code)
- 5.2.3 Category 3 (Applicable Classification Code)
- 5.2.4 Category 4 (Applicable Classification Code)
- 5.2.5 Category 5 (Applicable Classification Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Category 1 (Applicable Classification Code)
- 5.3.2 Category 2 (Applicable Classification Code)
- 5.3.3 Category 3 (Applicable Classification Code)
- 5.3.4 Category 4 (Applicable Classification Code)
- 5.3.5 Category 5 (Applicable Classification Code)
- 5.4 Cross-Border Pricing & Transaction Benchmarks
- 5.4.1 Export Pricing – Segment & Country
- 5.4.2 Import Pricing – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Cross-Border Trade & Delivery Routes
- 5.5.1 Cross-Border Trade/Delivery Route 1
- 5.5.2 Cross-Border Trade/Delivery Route 2
- 5.5.3 Cross-Border Trade/Delivery Route 3
- 5.5.4 Cross-Border Trade/Delivery Route 4
- 5.5.5 Cross-Border Trade/Delivery Route 5
- 5.6 Trade Policy & Market Access Impact Assessment
- 5.6.1 Tariff & Non-Tariff Barriers
- 5.6.2 Regional Trade & Economic Integration Frameworks
- 5.6.3 Bilateral & Multilateral Trade Agreements
- 5.6.4 Cross-Border Operating, Licensing & Localization Requirements
Note: This chapter applies where cross-border trade or delivery is relevant to Automotive Tire Pressure Monitoring System. Goods, services, and digital offerings are assessed using applicable classifications and transaction measures. Import-export volumes, trade balances, and route analyses are included only where meaningful to the market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Automotive Tire Pressure Monitoring System Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Leading, Mid-Sized & Emerging Player Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Automotive Tire Pressure Monitoring System Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company (Volume Where Applicable)
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 Company Market Share by Key Segment
- 6.2.6 Company Market Share by Customer Group
- 6.3 Operating Scale, Capacity & Infrastructure Analysis
- 6.3.1 Global Operating Scale & Supply Capacity
- 6.3.2 Resource Utilization & Operating Efficiency
- 6.3.3 Output, Service Delivery & Activity Metrics
- 6.3.4 Operating Footprint & Infrastructure Map
- 6.3.5 Planned Operational & Capacity Expansion
- 6.4 Automotive Tire Pressure Monitoring System Competitive Benchmarking Matrix
- 6.4.1 Revenue, Growth, Profitability & Operating Metric Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Automotive Tire Pressure Monitoring System (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Products, Services & Solutions in Automotive Tire Pressure Monitoring System
- 6.5.3 Operational & Infrastructure Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Automotive Tire Pressure Monitoring System Market – By Sales & Delivery Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032) (Volume Where Applicable)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share (Volume Where Applicable)
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region (Volume Where Applicable)
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Sales & Delivery Channel
- 8.2.2 By Competitive Positioning & Price Tier
Chapter 9. North America Automotive Tire Pressure Monitoring System Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Automotive Tire Pressure Monitoring System Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Automotive Tire Pressure Monitoring System Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Automotive Tire Pressure Monitoring System Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Automotive Tire Pressure Monitoring System Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Automotive Tire Pressure Monitoring System Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Automotive Tire Pressure Monitoring System Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Supply, Output & Operating Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Demand, Adoption & Usage Assumptions
- Appendix F – Pricing & Revenue Metric Reference Tables
- Appendix G – Company Operations & Infrastructure Database
- Appendix H – Cross-Border Trade & Activity Data Tables (Where Applicable)
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
