
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
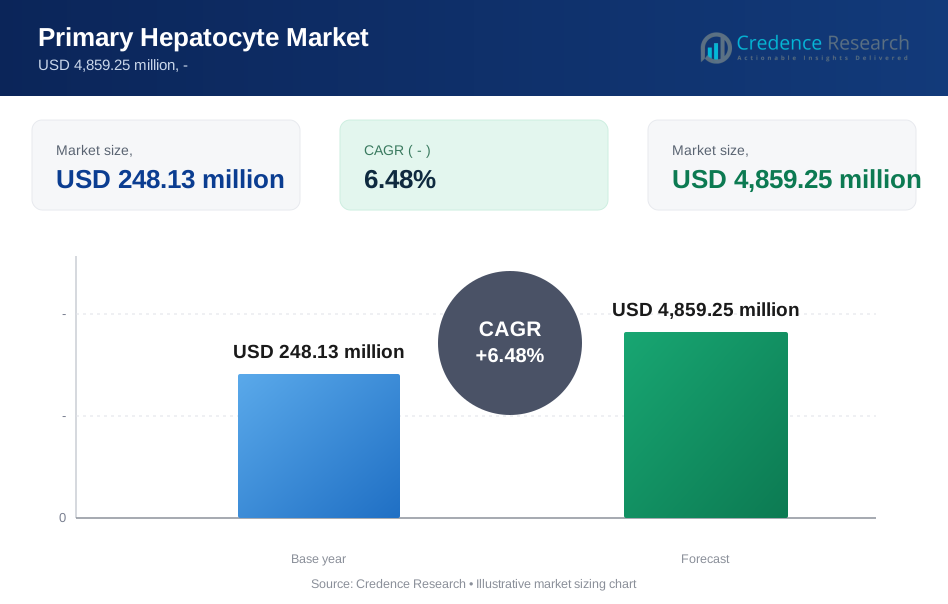
| Primary Hepatocyte Market Size 2023 | USD 248.13 million |
| Primary Hepatocyte Market, CAGR | 6.48%. |
| Primary Hepatocyte Market Size 2032 | USD 4859.25 million |
Market Overview:
The primary hepatocyte market is on track for substantial growth, with a projected increase from USD 248.13 million in 2023 to USD 4859.25 million by 2032, reflecting a robust compound annual growth rate (CAGR) of 6.48%. This growth is primarily driven by the rising prevalence of liver diseases, including hepatitis B, hepatitis C, and non-alcoholic fatty liver disease (NAFLD). The demand for advanced drug discovery and development processes is fueling the use of primary hepatocytes for in vitro testing and modeling, given their ability to provide a more realistic representation of human liver function compared to traditional cell lines.
Pharmaceutical and biotechnology companies are increasingly focusing on improving the efficiency and accuracy of drug discovery pipelines, making primary hepatocytes a valuable tool. Their application allows for better assessment of drug metabolism, toxicity, and efficacy. Furthermore, technological advancements in hepatocyte isolation and culture techniques are enhancing the viability and functionality of these cells, contributing to their increased use in drug discovery studies.
Emerging trends in the market include the utilization of bioprinting technologies to create 3D liver models, offering a more physiologically relevant platform for drug testing. Additionally, advancements in cryopreservation techniques are improving the storage and transportation of primary hepatocytes, enhancing accessibility, and reducing the limitations associated with fresh cell isolation procedures. The market is witnessing a growing emphasis on ethical sourcing practices and standardized protocols for primary hepatocyte isolation and culture, ensuring quality, consistency, and ethical procurement.
Opportunities for market players lie in the development of improved isolation and culture techniques, offering a broader range of primary hepatocytes, including cryopreserved cells and patient-derived options. Strategic partnerships with contract research organizations (CROs) and pharmaceutical companies can provide valuable insights and facilitate the development of targeted solutions for drug discovery applications. Proactive engagement with regulatory bodies and adherence to ethical sourcing practices will be crucial for ensuring the long-term sustainability of the primary hepatocyte market.
Market Drivers:
Factors such as unhealthy lifestyles, obesity, and increased alcohol consumption contribute to the rise in these diseases, creating a heightened demand for effective treatment options and intensifying drug discovery efforts. Primary hepatocytes play a pivotal role in these efforts, serving as a critical tool for researchers to assess the efficacy and safety of potential drugs for liver diseases, thereby propelling market growth.
The pharmaceutical industry's relentless pursuit of innovation in drug discovery and development is a primary driver for the growing demand for primary hepatocytes. These cells closely replicate human liver functions and metabolism, offering researchers a dependable platform for evaluating potential drug interactions with the liver and predicting their efficacy and safety in humans. The limitations of traditional testing methods, such as animal models and cell lines, further highlight the importance of primary hepatocytes as a more reliable and human-relevant alternative.
The increasing focus on personalized medicine is another significant catalyst for the primary hepatocyte market. These cells facilitate the study of individual patient responses to specific drugs, paving the way for the development of personalized treatment options for liver diseases.
Technological advancements in the culture and cryopreservation of hepatocytes are improving the viability and functionality of primary hepatocytes, making them more readily available for research and development purposes. This leads to a more efficient and reliable supply chain, further supporting market growth.
Government support, recognizing the substantial burden of liver diseases and increasing funding for related research, is providing a favorable environment for the primary hepatocyte market. Governments worldwide are dedicating resources to support research initiatives that utilize primary hepatocytes, aiding in the market's growth acceleration.
Furthermore, the expanding applications of primary hepatocytes in regenerative medicine, especially in cell transplantation therapies for liver cell replacement, are expected to contribute to the market's upward trajectory as regenerative medicine continues to advance.
Market Trends:
Rising Demand for In Vitro Drug Discovery
The in vitro diagnostics (IVD) market size worldwide was over 18 percent of the total global revenue in the medical technology industry in 2021. During the COVID-19 pandemic, Europe saw massive investment in IVD testing to scale up capacity and cope with historic demand.
Advancements in Hepatocyte Isolation and Culture Techniques
With the onset of the 20th century, hepatocyte culture witnessed immense advancements, such as spheroid cultures, matrigel cultures, tissue engineering-based scaffolds, and 3D bio-printing to maintain long-term functional hepatocytes in vitro. Cryopreservation of hepatocytes has increased due to the improvement of freezing and thawing methods.
Focus on Personalized Medicine and Precision Medicine
Precision medicine, also referred to as personalized medicine, helps physicians identify a patient’s unique disease risks and the treatments that will work best for them. - Primary human hepatocytes are still considered the “gold standard” for evaluating in vitro liver disease models.
Growing Investment in Liver Disease Research
The increasing prevalence of liver diseases such as hepatitis and non-alcoholic fatty liver disease (NAFLD) is driving investment in research efforts. Primary hepatocytes play a crucial role in these research activities, facilitating the exploration of disease mechanisms and the development of new therapies.
Market Restraints and Challenges:
- Limited Availability and Donor Variability: Primary hepatocytes are isolated from human livers, making their availability a major challenge. Donor livers are scarce, often obtained from surgical resections or deceased donors with limited suitability for cell isolation. Additionally, inherent variability exists between donors in terms of age, health status, and ethnicity. This variability can significantly impact the functionality and performance of isolated hepatocytes, affecting research results and downstream applications.
- High Cost and Complex Isolation Procedures: Isolating primary hepatocytes is a complex and labor-intensive process requiring specialized expertise and facilities. This complexity translates to high production costs, making these cells an expensive resource for researchers and pharmaceutical companies. Additionally, the viability and functionality of isolated hepatocytes diminish over time in culture, necessitating frequent isolation procedures, further adding to the overall cost burden.
- Limited Proliferation and Short Lifespan: Unlike some other cell types, primary hepatocytes have a limited capacity for self-renewal and proliferation in culture. This restricts the availability of sufficient cell numbers for large-scale studies and drug discovery applications. Furthermore, primary hepatocytes have a relatively short lifespan in culture, typically lasting only a few days to a few weeks. This limited lifespan poses challenges for long-term studies and drug screening assays.
- Ethical Considerations and Regulatory Hurdles: The use of human tissues for research purposes raises ethical concerns that require careful consideration and adherence to strict regulations. Obtaining informed donor consent, ensuring proper donor anonymity, and complying with bioethical guidelines add complexity to the procurement process. Additionally, regulatory requirements for handling and transporting human-derived tissues can further complicate research activities.
- Competition from Alternative In Vitro Models: The limitations associated with primary hepatocytes are driving the development and adoption of alternative in vitro models for drug discovery and liver disease research. These alternatives include immortalized human liver cell lines, stem cell-derived hepatocytes, and microfluidic organ-on-a-chip platforms. While these models may not fully replicate the functionality of primary hepatocytes, they offer advantages like scalability, lower costs, and potentially longer lifespans in culture.
Recent Developments:
- In August 2023, The recent announcement by the business indicates that the Phase III LITESPARK-005 research demonstrated that Merck's Welireg (belzutifan) successfully achieved its primary objective of a significant enhancement in progression-free survival for patients diagnosed with advanced renal cell carcinoma.
- In March 2023, Thermo Fisher Scientific established a cell therapy facility at UCSF to expedite the advancement of innovative therapeutic interventions. The anticipated collaboration between Thermo Fisher and UCSF in 2021 presented an opportunity to explore the hypothesis that the proximity of scientists, doctors, and patients to a manufacturing facility could enhance the efficiency of breakthrough drug development.
Segmentation Analysis:
Application:
- Drug Discovery and Development: The largest application segment for primary hepatocytes. These cells are used for in vitro drug metabolism and toxicity studies, playing a crucial role in identifying and developing new drugs with minimal side effects.
- Toxicity Testing: Primary hepatocytes are employed to assess the potential hepatotoxic (liver-damaging) effects of drugs, chemicals, and other substances. This helps ensure the safety of these products before human trials.
- Liver Disease Modeling and Research: Primary hepatocytes are vital tools for researchers studying liver diseases like hepatitis, cirrhosis, and fatty liver disease. They allow scientists to model disease processes and test potential therapeutic interventions.
- Regenerative Medicine: A growing application area with the potential to use primary hepatocytes for liver cell transplantation therapies to treat patients with end-stage liver disease.
Segments:
By Product
- Cryopreserved Suspension Hepatocytes
- Fresh suspension hepatocytes
- 3D (spheroid) hepatocytes
- Expanded Hepatocytes (Plateable)
- Non-characterized Hepatocytes
By Species
- Humans
- Rats
- Mice
- Dogs
- Monkeys
- Horses
- Others
By Application/Assay
- Cell Viability Assays
- Cytochrome Enzyme Activity
- High-content cytotoxicity
- Transporter Inhibition Assays
- In Vitro Intrinsic Clearance
- Phospholipids Assays
- Others
By End User
- Biopharmaceutical Companies
- Academic and Research Institutes
- Contract Research Organizations
By Region
- North America
- The U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- The U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of Middle East and Africa
Key player:
- Thermo Fisher Scientific, Inc.
- Merck KgAa
- Corning Incorporated
- Lonza Group
- Charles River Laboratories, Inc.
- PromoCell Gmbh
- American Type Culture Collection (ATCC)
- Cell Biologics, Inc.
- Zen-Bio, Inc.
- Stemcell Technologies, Inc.
- AllCells
- iXCells Biotechnologies
- Neuromics
- Axol Bioscience Ltd.
- StemExpress
- Bioivt
- ScienCell Research Laboratories, Inc.
- AMSBIO
- ProMab Biotechnologies, Inc.
- Creative Bioarray
- Bps Bioscience, Inc.
- Epithelix
- Reachbio Research Labs
- AcceGen
- Kosheeka
Regional Analysis:
North America, currently the leader in the primary hepatocyte market, maintains its dominant position owing to several factors. These include an established research infrastructure with a concentration of pharmaceutical and biotechnology companies, high government funding for liver disease research, and an increasing adoption of primary hepatocytes in drug discovery and development. Europe, a strong contender, is expected to retain a robust market presence due to the presence of leading life science research centers, a growing focus on personalized medicine, and in vitro toxicology testing. Additionally, stringent regulatory requirements for drug development drive the demand for high-quality primary hepatocytes in the region.
Asia-Pacific emerges as an emerging market and is anticipated to be the fastest-growing regional market. This growth is attributed to rising disposable income, increasing investments in healthcare infrastructure, a growing burden of liver diseases in the region, and government initiatives promoting domestic research and development activities. The rest of the world, encompassing Latin America, the Middle East, and Africa, holds promising potential for future growth. Factors contributing to this potential include growing awareness of liver diseases, increasing investments in the healthcare sector, and the development of biobanking facilities to improve access to primary hepatocytes.
Future Outlook:
- Rising Demand for Drug Discovery and Development: The increasing prevalence of chronic liver diseases and the growing focus on personalized medicine will propel the demand for primary hepatocytes in drug discovery and development processes.
- Expanding Applications in Liver Disease Modeling: Advancements in 3D cell culture technologies and microfluidic systems will create new avenues for utilizing primary hepatocytes in liver disease modeling and drug screening, further accelerating market growth.
- Growing Adoption in Toxicity Testing: The rising need for reliable and efficient preclinical toxicity testing is expected to drive the adoption of primary hepatocytes as a viable alternative to traditional methods.
- Government Funding and Support: Continued government funding initiatives for liver research and drug discovery programs will provide a significant boost to the primary hepatocyte market.
- Increasing Focus on Personalized Medicine: The growing emphasis on personalized medicine approaches, including cell-based therapies, is likely to create new opportunities for the utilization of primary hepatocytes in regenerative medicine applications.
- Technological Advancements and Improved Isolation Techniques: Advancements in isolation and cryopreservation techniques will enhance the viability and functionality of primary hepatocytes, making them a more attractive option for research applications.
- Growing Awareness of Liver Diseases: Rising public awareness of liver diseases like hepatitis and non-alcoholic fatty liver disease (NAFLD) will likely fuel the demand for improved diagnostic tools and treatment options, ultimately benefiting the primary hepatocyte market.
- Strategic Collaborations and Mergers and Acquisitions: The market is expected to witness an increase in strategic collaborations and mergers and acquisitions between key players to expand product portfolios and geographical reach.
- Focus on Standardization and Regulatory Landscape: Regulatory bodies worldwide are likely to implement stricter guidelines and standardization protocols for primary hepatocytes, ensuring their quality and consistency for research purposes.
- Regional Market Expansion: The Asia Pacific region is expected to experience the fastest growth in the primary hepatocyte market due to factors like rising government investments in healthcare infrastructure and increasing research activities.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What factors contribute to the substantial growth of the primary hepatocyte market, increasing from USD 248.13 million in 2023 to USD 4859.25 million by 2032 with a CAGR of 6.48%?
How have technological advancements played a pivotal role in shaping the primary hepatocyte market?
What role do primary hepatocytes play in drug discovery and development, and why are they increasingly preferred in these processes?
How does the prevalence of liver diseases and the shift toward personalized medicine impact the demand for primary hepatocytes on the market?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Primary Hepatocyte Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (the historical period; forecast to the forecast period)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Primary Hepatocyte Market Snapshot
- 2.1.1 Market Size – Historical (the historical period) & Forecast (the forecast period) (base year: USD 248.13 million → forecast year: USD 4,859.25 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Primary Hepatocyte Market Segmentation Snapshot
- 2.2.1 Market Split by Region – vs.
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share –
- 2.3.2 Top 10 Players by Volume Share –
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Primary Hepatocyte Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Primary Hepatocyte Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Primary Hepatocyte Market Drivers
- 3.3 Primary Hepatocyte Market Restraints & Challenges
- 3.4 Primary Hepatocyte Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Primary Hepatocyte Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Primary Hepatocyte Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Primary Hepatocyte category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Primary Hepatocyte Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through the forecast period
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through the forecast period
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Primary Hepatocyte Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (the historical period)
- 5.1.2 Global Export Volume by Country (the historical period)
- 5.1.3 Global Import Value by Country (the historical period)
- 5.1.4 Global Import Volume by Country (the historical period)
- 5.1.5 Net Trade Balance by Country (the historical period)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (the historical period)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Primary Hepatocyte market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Primary Hepatocyte Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs.
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Primary Hepatocyte Market Share Analysis –
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. )
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Primary Hepatocyte Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Primary Hepatocyte (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Primary Hepatocyte Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Primary Hepatocyte Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel ( & )
- 7.1.2 Channel Mix Evolution (the forecast period)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through the forecast period
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Primary Hepatocyte Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Primary Hepatocyte Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Primary Hepatocyte Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Primary Hepatocyte Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Primary Hepatocyte Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Primary Hepatocyte Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Primary Hepatocyte Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
