
Market Overview
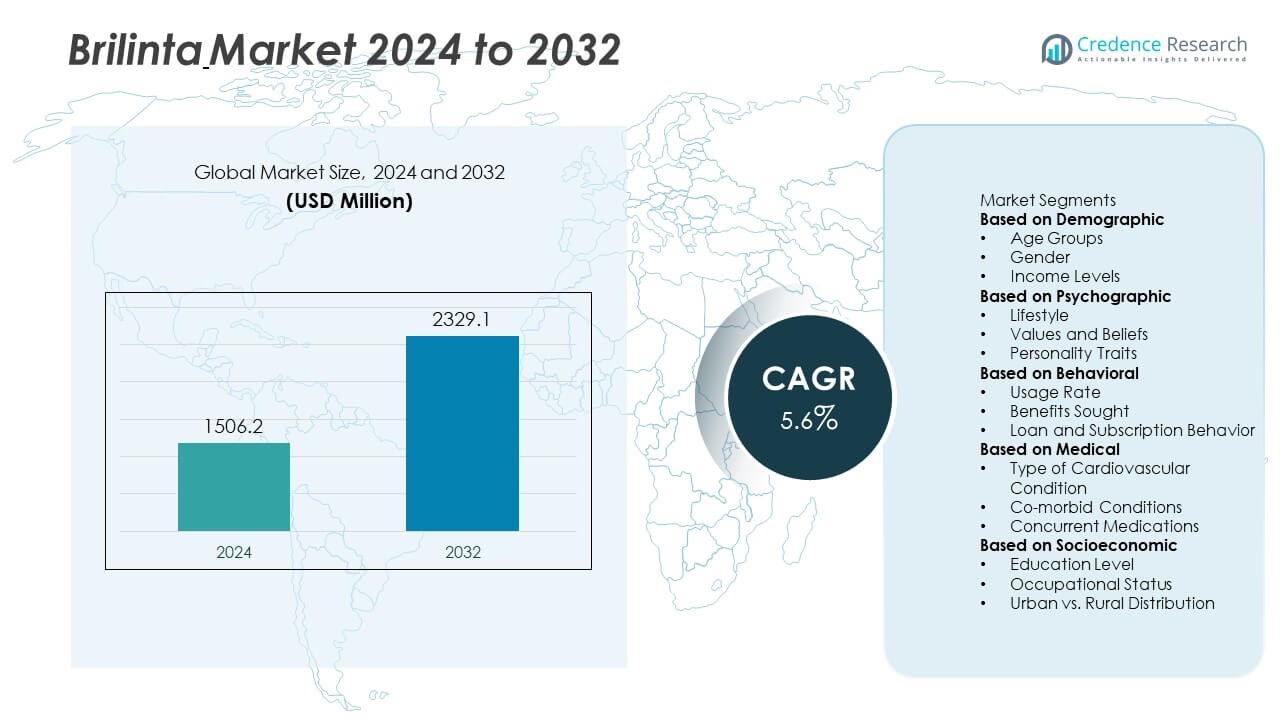
The Brilinta Market was valued at USD 1,506.2 million in 2024 and is projected to reach USD 2,329.1 million by 2032, growing at a CAGR of 5.6% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2024 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Brilinta Market Size 2024 | USD 1,506.2 Million |
| Brilinta Market, CAGR | 5.6% |
| Brilinta Market Size 2032 | USD 2,329.1 Million |
The Brilinta Market is driven by the rising prevalence of cardiovascular diseases, growing adoption of advanced antiplatelet therapies, and strong clinical evidence supporting its efficacy in reducing recurrent thrombotic events. Expanding indications, including long-term secondary prevention and potential stroke prevention, enhance its clinical relevance.
The Brilinta Market spans North America, Europe, Asia-Pacific, Latin America, and the Middle East & Africa, each demonstrating distinct adoption patterns influenced by healthcare infrastructure, treatment guidelines, and disease prevalence. North America leads adoption due to strong integration of Brilinta into cardiovascular care protocols and broad insurance coverage. Europe maintains high prescription rates supported by established clinical guidelines and centralized healthcare systems. Asia-Pacific shows rapid growth with expanding cardiac care facilities and improving access to advanced therapies in urban centers. Latin America and the Middle East & Africa are gradually increasing uptake through hospital modernization and physician education. Key players influencing the market include AstraZeneca, the manufacturer of Brilinta; Pfizer, with extensive cardiovascular therapy portfolios; Amgen, focusing on innovative cardiovascular solutions; and Merck, leveraging its global distribution and research capabilities to strengthen therapeutic reach in antiplatelet treatments.
Market Insights
- The Brilinta Market was valued at USD 1,506.2 million in 2024 and is projected to reach USD 2,329.1 million by 2032, growing at a CAGR of 5.6% during the forecast period.
- Rising prevalence of cardiovascular diseases, an aging population, and updated clinical guidelines are driving adoption of Brilinta for acute coronary syndrome and long-term secondary prevention.
- Expanding use in stroke prevention trials, patient-centric dosing strategies, and integration into extended treatment protocols are shaping current market trends.
- The market is influenced by strong competition among major pharmaceutical companies that invest in clinical trials, regulatory approvals, and physician education to strengthen therapeutic positioning.
- High treatment costs, varying reimbursement coverage, and potential side effects such as dyspnea and bleeding risks remain key restraints affecting consistent adoption across regions.
- North America leads adoption due to advanced healthcare infrastructure and strong treatment integration, Europe maintains high prescription rates through guideline adherence, Asia-Pacific shows rapid uptake with expanding cardiac care facilities, and Latin America and the Middle East & Africa see gradual growth through hospital modernization.
- Opportunities emerge from expanding healthcare access in emerging markets, regulatory approvals for new indications, and collaborative research that can extend Brilinta’s role in broader cardiovascular disease management.
Market Drivers
Rising Prevalence of Cardiovascular Diseases Driving Demand
The Brilinta Market benefits from the growing incidence of acute coronary syndrome and other cardiovascular conditions worldwide. An aging global population and lifestyle-related risk factors increase the need for effective antiplatelet therapy. Healthcare systems integrate Brilinta into treatment protocols to reduce the risk of thrombotic events following percutaneous coronary interventions. It is widely prescribed for secondary prevention in high-risk patients. Clinical guidelines from leading cardiology associations support its inclusion in standard care pathways. This expanding patient pool strengthens consistent demand across both developed and emerging regions.
- For instance, The US FDA expanded Brilinta’s indication to allow long-term use in patients with a history of myocardial infarction, aligning labeling with sustained secondary prevention.
Strong Clinical Evidence Supporting Efficacy and Safety
Extensive clinical trial data reinforces the therapeutic value of Brilinta in improving cardiovascular outcomes. Trials such as PLATO and PEGASUS-TIMI 54 demonstrated significant reductions in major adverse cardiovascular events compared to traditional therapies. Physicians value its ability to provide rapid platelet inhibition with reversible binding properties. It supports superior long-term management strategies in patients with prior myocardial infarction. The continuous release of post-marketing surveillance data enhances physician confidence in prescribing it. Such strong evidence base drives adoption across hospital and outpatient settings.
- For instance, in the PLATO trial, Brilinta demonstrated a 16% relative risk reduction in cardiovascular death, myocardial infarction, or stroke compared to clopidogrel, benefiting over 18,000 acute coronary syndrome patients worldwide.
Expanding Indications and Regulatory Approvals
Regulatory authorities in multiple countries have approved Brilinta for broader cardiovascular applications. It now covers indications beyond acute coronary syndrome, including long-term secondary prevention in patients with established coronary artery disease. Expansion into stroke prevention segments adds to its clinical relevance. Pharmaceutical strategies focus on submitting new data to health agencies to secure additional label extensions. Hospitals and cardiology centers respond by incorporating it into wider patient management plans. This expanded clinical footprint directly supports market growth potential.
Growing Access Through Healthcare Infrastructure Development
Improved healthcare infrastructure in emerging markets increases patient access to advanced cardiovascular therapies. Governments and private insurers enhance reimbursement frameworks for essential cardiovascular drugs, including Brilinta. It benefits from inclusion in national essential medicine lists in certain regions. Expansion of specialist cardiac care facilities supports higher diagnosis and treatment rates. Distribution networks adapt to reach rural and underserved areas, ensuring consistent supply. These improvements in access accelerate uptake among newly diagnosed and high-risk patient populations.
Market Trends
Increasing Use in Long-Term Secondary Prevention Protocols
The Brilinta Market is witnessing a shift toward extended treatment durations for patients with prior myocardial infarction. Physicians incorporate it into long-term therapy plans to reduce recurrent cardiovascular events. This approach aligns with evolving clinical guidelines that emphasize sustained platelet inhibition in high-risk populations. Real-world data supports its tolerability and sustained efficacy over multiple years of therapy. Hospitals adapt their discharge protocols to ensure continued outpatient prescription. This trend strengthens its role in chronic cardiovascular care pathways.
- For instance, the PEGASUS–TIMI 54 trial showed ticagrelor 60 mg twice daily, continued beyond one year after MI, reduced the composite of CV death, MI, or stroke by ~15–16% versus placebo, with an expected increase in major bleeding.
Rising Integration into Stroke Prevention Strategies
Clinical research is expanding Brilinta’s potential in ischemic stroke prevention and management. Trials investigate its efficacy in reducing recurrent stroke risks when used in specific patient groups. It attracts interest from neurologists for use in secondary prevention settings alongside standard therapies. Regulatory submissions in multiple regions seek label expansion to include these new indications. Academic centers actively participate in large-scale, multicountry trials to validate its broader role. This trend could expand its market beyond core cardiology applications.
- For instance, the THALES trial demonstrated that Brilinta plus aspirin reduced the risk of stroke and death by 17% compared to aspirin alone in patients with acute non-cardioembolic ischemic stroke or high-risk TIA.
Growing Adoption of Patient-Centric Dosing Strategies
Pharmaceutical development focuses on optimizing Brilinta’s dosing schedules to improve adherence and reduce side effects. Lower-dose regimens are evaluated for long-term use in patients requiring extended antiplatelet therapy. It supports the goal of minimizing bleeding risks while preserving cardiovascular protection. Personalized medicine approaches match dosing intensity with patient-specific risk profiles. Hospitals integrate pharmacist-led counseling programs to reinforce adherence. This trend enhances patient outcomes and treatment continuity.
Expansion of Collaborative Research and Real-World Evidence Generation
Global healthcare networks and pharmaceutical companies collaborate to produce extensive real-world evidence on Brilinta’s performance. Data from electronic health records and large patient registries offer insights into effectiveness in diverse clinical settings. It helps refine treatment guidelines and identify optimal patient segments for therapy. Post-marketing studies assess comparative outcomes against other antiplatelet agents. Regulatory agencies increasingly value such evidence in decision-making processes. This trend accelerates market confidence and supports broader prescribing practices.
Market Challenges Analysis
High Treatment Costs and Reimbursement Limitations
The Brilinta Market faces challenges from the high cost of therapy, which can limit access in price-sensitive regions. Branded formulations often remain beyond the reach of uninsured or underinsured patients. Limited reimbursement coverage in certain healthcare systems restricts broader adoption. It places financial pressure on hospitals and clinics in low- and middle-income countries. Health authorities may prioritize lower-cost generic antiplatelet agents, reducing its market share potential. These economic barriers can slow uptake despite strong clinical evidence supporting its benefits.
Adverse Effects and Patient Compliance Issues
Side effects such as dyspnea and bleeding risks present significant hurdles for long-term therapy adherence. Some patients discontinue treatment prematurely due to intolerance or perceived discomfort. It requires careful patient selection and monitoring to balance efficacy with safety. Physicians may opt for alternative antiplatelet therapies in cases with high bleeding risk. Poor compliance undermines clinical outcomes and reduces the overall effectiveness of prevention strategies. This challenge emphasizes the need for enhanced patient education and tailored dosing regimens to maintain sustained use.
Market Opportunities
Expansion into Emerging Cardiovascular Care Markets
The Brilinta Market holds strong growth potential in emerging economies with increasing cardiovascular disease prevalence. Expanding healthcare infrastructure and broader access to diagnostic services create more opportunities for early intervention. Governments are investing in specialized cardiac care centers, which drives demand for advanced antiplatelet therapies. It benefits from inclusion in updated national treatment guidelines in several developing regions. Partnerships with local distributors can improve reach in underserved areas. This expansion supports both patient outcomes and long-term market sustainability.
Diversification of Indications Through Ongoing Clinical Research
Extensive clinical trials exploring Brilinta’s role in stroke prevention, peripheral artery disease, and other thrombotic conditions could widen its therapeutic scope. Positive trial results may lead to regulatory approvals for new patient segments, strengthening its competitive positioning. It has the potential to serve as a core therapy in multidisciplinary cardiovascular management. Integration into combination regimens with other agents offers opportunities for personalized treatment approaches. Collaborative research with academic institutions can accelerate adoption in new specialties. These developments create a pathway for expanding market relevance beyond its current cardiovascular focus.
Market Segmentation Analysis:
By Demographic
The Brilinta Market serves a wide demographic spectrum, with primary demand concentrated among adults over the age of 50 who face elevated cardiovascular risk. This group includes patients with acute coronary syndrome, history of myocardial infarction, or established coronary artery disease. It also addresses younger patients with genetic or lifestyle-related predispositions to cardiovascular events. Gender-specific studies have shown consistent efficacy in both male and female patients, though dosing and monitoring requirements may vary based on comorbidities. Elderly populations often require careful management to balance efficacy with bleeding risk, making patient selection critical.
- For instance, in PEGASUS-TIMI 54 (mean age 65), adults ≥50 with prior MI on aspirin had primary events of 7.8% on ticagrelor 60 mg twice daily vs 9.0% on placebo over a median 33 months; TIMI major bleeding was 2.3% vs 1.1%.
By Psychographic
Psychographic segmentation in the Brilinta Market focuses on patient attitudes toward preventive healthcare, adherence to long-term medication, and trust in advanced pharmaceutical solutions. Patients who value proactive cardiovascular risk management are more likely to remain compliant with prescribed regimens. It appeals to individuals who prioritize evidence-based therapies backed by strong clinical trial data. Physicians often target health-conscious segments with comprehensive counseling to reinforce the importance of continuous therapy. In markets where awareness campaigns have improved patient knowledge about cardiovascular risks, adoption rates are higher.
- For instance, AstraZeneca’s PLATO trial reported a lower 12-month rate of vascular death/MI/stroke with ticagrelor vs. clopidogrel (9.8% vs. 11.7%), reinforcing appeal among evidence-seeking patients and physicians.
By Behavioral
Behavioral segmentation captures patterns related to prescription initiation, adherence, and long-term therapy continuation. The Brilinta Market shows strong uptake in hospital discharge protocols for post-acute coronary syndrome patients, where immediate initiation is critical for reducing recurrent event risks. It is often included in structured follow-up programs to ensure consistent use during the high-risk period after intervention. Patient adherence is influenced by perceived side effects, ease of dosing, and quality of physician-patient communication. Behavioral targeting also considers the role of pharmacy-led interventions and digital reminder systems to improve compliance. This approach enables healthcare providers to identify and engage patients most likely to benefit from sustained antiplatelet therapy.
Segments:
Based on Demographic
- Age Groups
- Gender
- Income Levels
Based on Psychographic
- Lifestyle
- Values and Beliefs
- Personality Traits
Based on Behavioral
- Usage Rate
- Benefits Sought
- Loan and Subscription Behavior
Based on Medical
- Type of Cardiovascular Condition
- Co-morbid Conditions
- Concurrent Medications
Based on Socioeconomic
- Education Level
- Occupational Status
- Urban vs. Rural Distribution
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- France
- Germany
- Italy
- Spain
- Russia
- Belgium
- Netherlands
- Austria
- Sweden
- Poland
- Denmark
- Switzerland
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- Thailand
- Indonesia
- Vietnam
- Malaysia
- Philippines
- Taiwan
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Peru
- Chile
- Colombia
- Rest of Latin America
- Middle East
- UAE
- KSA
- Israel
- Turkey
- Iran
- Rest of Middle East
- Africa
- Egypt
- Nigeria
- Algeria
- Morocco
- Rest of Africa
Regional Analysis
North America
North America accounts for 42% of the Brilinta Market, supported by advanced healthcare infrastructure, high awareness of cardiovascular disease prevention, and favorable reimbursement policies. The United States dominates regional sales, driven by strong integration of Brilinta into treatment guidelines for acute coronary syndrome and secondary prevention. High diagnosis rates, widespread access to interventional cardiology, and robust insurance coverage enable broad adoption. Canada contributes through centralized healthcare initiatives that prioritize evidence-based antiplatelet therapies. It benefits from consistent physician education programs and ongoing real-world evidence studies validating clinical outcomes. Strategic collaborations between pharmaceutical companies and hospital networks further enhance prescribing rates in this region.
Europe
Europe holds 31% of the Brilinta Market, with leading demand from the United Kingdom, Germany, France, and Italy. The region’s strong focus on clinical guideline adherence and government-funded healthcare systems supports high prescription volumes. European cardiology associations endorse Brilinta for secondary prevention in high-risk patients, reinforcing its position in standard care protocols. It benefits from centralized procurement in several countries, improving accessibility in both urban and rural hospitals. Ongoing clinical trials in the region explore expanded indications, including stroke prevention. Investment in cardiovascular research infrastructure allows rapid adoption of new therapeutic strategies, strengthening market penetration.
Asia-Pacific
Asia-Pacific represents 17% of the Brilinta Market, fueled by growing cardiovascular disease incidence, expanding healthcare access, and rising awareness of advanced therapies. China, Japan, India, and Australia lead the regional adoption curve, supported by urbanization and increased availability of interventional cardiology facilities. It gains momentum from national healthcare reforms that improve access to prescription drugs in emerging economies. Localized physician training programs promote correct patient selection and monitoring. Expansion of generic and branded supply channels ensures consistent availability across metropolitan and secondary cities. The region’s large patient base presents significant potential for long-term growth as diagnostic capabilities expand.
Latin America
Latin America holds 6% of the Brilinta Market, with Brazil, Mexico, and Argentina driving demand. Rising investments in public healthcare systems and private hospital networks improve access to modern cardiovascular treatments. It benefits from gradual inclusion into treatment protocols for post-myocardial infarction and high-risk coronary artery disease patients. Efforts to expand interventional cardiology services in urban centers further increase uptake. Pharmaceutical companies focus on physician education and awareness campaigns to improve adoption rates. However, variations in reimbursement and economic constraints limit consistent penetration across all markets in the region.
Middle East & Africa
The Middle East & Africa account for 4% of the Brilinta Market, supported by targeted investments in tertiary care hospitals and specialized cardiac centers. Gulf countries, including Saudi Arabia and the United Arab Emirates, lead in adoption due to advanced healthcare systems and high cardiovascular disease burden. It benefits from government-backed initiatives to modernize treatment protocols and improve access to branded antiplatelet therapies. In Africa, uptake remains concentrated in urban hospitals with advanced cardiology departments. International partnerships with healthcare NGOs and training programs for cardiologists support gradual expansion. The region’s market potential remains underdeveloped but is expected to grow with continued infrastructure improvements.
Key Player Analysis
- Amgen
- Boehringer
- Merck
- Ingelheim Pfizer
- AstraZeneca
- Roche
- Eli Lilly
- Pfizer
- GSK
- Ingelheim
Competitive Analysis
The competitive landscape of the Brilinta Market is shaped by the presence of major pharmaceutical companies with strong cardiovascular therapy portfolios. Leading players include AstraZeneca, Pfizer, Amgen, Merck, and GSK, each leveraging global distribution networks, clinical expertise, and regulatory strategies to strengthen market position. AstraZeneca, as the originator of Brilinta, maintains dominance through extensive clinical trial programs, post-marketing surveillance, and strategic collaborations with healthcare institutions to expand usage across approved and emerging indications. Pfizer supports its cardiovascular portfolio with comprehensive physician outreach, ensuring integration into treatment protocols for acute coronary syndrome and secondary prevention. Amgen focuses on innovation in cardiovascular care, aligning with collaborative research to enhance patient outcomes. Merck emphasizes its global presence and market access capabilities, ensuring consistent supply and regional penetration. GSK contributes through research partnerships and targeted market expansion efforts. Competitive strategies include investment in real-world evidence, label extensions, and expansion into high-growth regions with evolving healthcare infrastructure.
Recent Developments
- In May 2025, Teva Pharmaceuticals launched an AB-rated generic version of Brilinta (ticagrelor) tablets in the U.S
- In August 2024, The U.S. FDA accepted the Biologics License Application (BLA) for bentracimab, a novel specific reversal agent for ticagrelor (Brilinta), granting it priority review status with a target action date in early 2025
Market Concentration & Characteristics
The Brilinta Market exhibits moderate concentration, with a limited number of multinational pharmaceutical companies influencing global supply, regulatory strategy, and clinical adoption. AstraZeneca leads through direct product ownership, while other key industry participants impact market dynamics via distribution partnerships, competitive therapies, and ongoing cardiovascular research. It is characterized by high entry barriers due to stringent regulatory requirements, extensive clinical trial obligations, and the need for strong physician outreach programs. The market relies heavily on evidence-based positioning supported by large-scale trials and post-marketing surveillance. Patient outcomes, safety profiles, and guideline endorsements significantly shape prescribing behavior. It shows strong alignment with specialized cardiovascular care networks and benefits from integration into hospital discharge protocols for acute coronary syndrome. The competitive environment is defined by continuous investment in label expansions, development of reversal agents, and the pursuit of long-term treatment indications to strengthen market sustainability.
Report Coverage
The research report offers an in-depth analysis based on Demographic, Psychographic, Behavioral, Medical, Socioeconomic and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The market will expand with broader adoption of Brilinta in long-term secondary prevention therapies.
- Clinical trial outcomes will support new indications, including stroke prevention and peripheral artery disease.
- Healthcare infrastructure improvements in emerging markets will drive higher prescription volumes.
- Regulatory approvals for label extensions will strengthen its clinical positioning.
- Real-world evidence will enhance physician confidence and guide optimal prescribing practices.
- Patient-centric dosing strategies will improve adherence and treatment continuity.
- Development of reversal agents will increase physician comfort in managing bleeding risks.
- Integration into more hospital discharge protocols will boost early initiation rates.
- Digital health tools will support patient monitoring and compliance.
- Strategic collaborations will expand access in underserved regions and diversify market reach.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Rising Prevalence of Cardiovascular Diseases
The increasing global incidence of acute coronary syndrome and other cardiovascular conditions, especially among aging populations, is driving demand for effective antiplatelet therapies like Brilinta. This trend is further supported by lifestyle-related risk factors and higher diagnosis rates.
Strong Clinical Evidence and Updated Guidelines
Extensive clinical trial data and real-world evidence have reinforced Brilinta’s efficacy and safety, leading to its inclusion in major cardiology guidelines for acute coronary syndrome and secondary prevention. This endorsement boosts physician confidence and prescription rates.
Expanding Indications and Regulatory Approvals
Regulatory bodies in multiple countries have approved Brilinta for broader cardiovascular applications, including long-term secondary prevention and stroke prevention. These label extensions increase its clinical relevance and expand the eligible patient pool.
Healthcare Infrastructure Development in Emerging Markets
Improvements in healthcare infrastructure, reimbursement frameworks, and access to advanced cardiac care in emerging economies are enabling greater adoption of Brilinta. Government investments and hospital modernization are key contributors to this growth.
Patient-Centric Dosing and Adherence Strategies
The development of optimized dosing regimens and patient support programs is improving long-term adherence to Brilinta therapy. Personalized medicine approaches and pharmacist-led interventions help minimize side effects and enhance treatment continuity.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Brilinta, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Brilinta market projected to grow between 2025 and 2032?
Which Brilinta market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Brilinta market?
Who are the leading companies in the Brilinta market?
Which region commanded the largest share of the Brilinta market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Medical
- 1.2.1 Type of Cardiovascular Condition
- 1.2.2 Co-morbid Conditions
- 1.2.3 Concurrent Medications
- 1.3 By Behavioral
- 1.3.1 Usage Rate
- 1.3.2 Benefits Sought
- 1.3.3 Adherence Patterns
- 1.4 By Demographic
- 1.4.1 Age Groups
- 1.4.2 Gender
- 1.4.3 Income Levels
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 1,506.2 million → 2032: USD 2,329.1 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Brilinta Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Brilinta Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Brilinta Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Brilinta Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Brilinta Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Brilinta Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Brilinta Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Brilinta Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 1,506.2 million → 2032: USD 2,329.1 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Brilinta Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Medical - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Type of Cardiovascular Condition
- 12.3.7.2 Co-morbid Conditions
- 12.3.7.3 Concurrent Medications
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By Behavioral - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Usage Rate
- 12.4.7.2 Benefits Sought
- 12.4.7.3 Adherence Patterns
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Demographic - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Age Groups
- 12.5.7.2 Gender
- 12.5.7.3 Income Levels
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Brilinta Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Brilinta Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Brilinta Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 AstraZeneca
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Pfizer
- 17.4 Amgen
- 17.5 Merck
- 17.6 GSK
- 17.7 Roche
- 17.8 Eli Lilly
- 17.9 Teva Pharmaceuticals
- 17.10 Boehringer Ingelheim
- 17.11 Sanofi
- 17.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

