
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
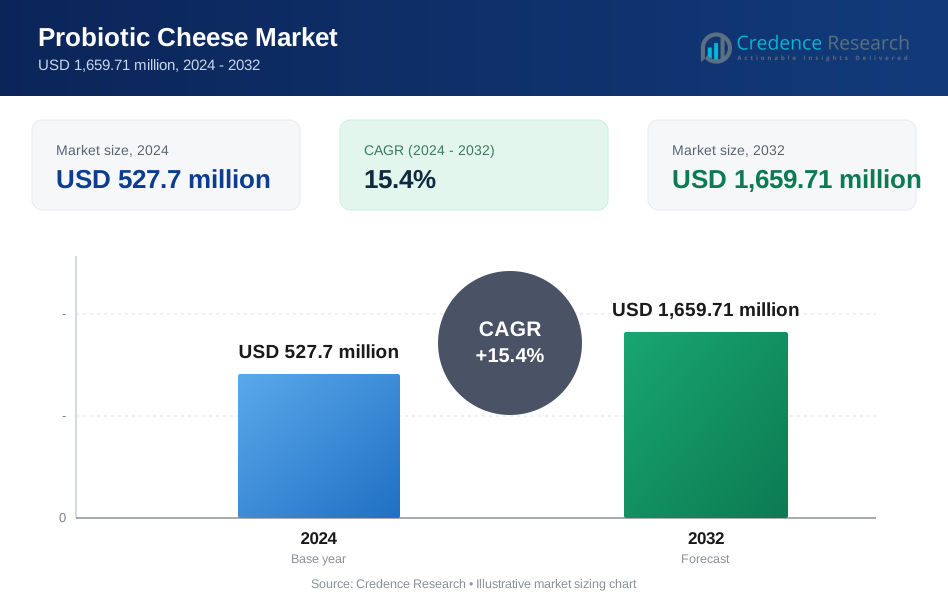
| Probiotic Cheese Market Size 2024 | USD 527.7 Million |
| Probiotic Cheese Market, CAGR | 15.4% |
| Probiotic Cheese Market Size 2032 | USD 1659.71 Million |
Market Overview:
The Probiotic Cheese Market is projected to grow from USD 527.7 million in 2024 to an estimated USD 1659.71 million by 2032, with a compound annual growth rate (CAGR) of 15.4% from 2024 to 2032.
Several factors are driving the growth of the probiotic cheese market. A key driver is the growing consumer awareness of the health benefits of probiotics, which include improved digestion, enhanced immunity, and better nutrient absorption. The rising prevalence of digestive disorders and lifestyle-related illnesses has further propelled demand for functional food products like probiotic cheese. Additionally, advancements in food technology have enabled manufacturers to incorporate probiotics into cheese without compromising taste or texture. Increasing adoption of clean-label and natural food trends has also played a significant role in market expansion. Furthermore, the aging global population, which seeks functional foods to maintain health and wellness, is a notable demographic influencing demand. Supportive government regulations and endorsements by health organizations have boosted consumer confidence in probiotic-rich products, creating a favorable market environment.
Regionally, Europe dominates the probiotic cheese market, driven by high consumer awareness and a well-established dairy industry. Countries like Germany, France, and the Netherlands lead in production and consumption, supported by robust innovation and research activities. North America follows closely, with increasing adoption of functional foods and rising health-consciousness among consumers in the U.S. and Canada. In the Asia-Pacific region, rapid urbanization, changing dietary preferences, and growing awareness of probiotics have fueled demand, particularly in countries like China, Japan, and India. The Middle East and Africa, though smaller in market share, show promising potential due to increasing disposable income and the growing popularity of functional foods. Latin America is also witnessing steady growth, with Brazil and Argentina emerging as key markets. Overall, regional variations in consumer preferences and purchasing power continue to shape the dynamics of the probiotic cheese market.
Market Drivers:
Increasing Consumer Awareness of Gut Health:
The rising consumer awareness about gut health and its impact on overall well-being has significantly driven the probiotic cheese market. Probiotics, known for their ability to promote healthy digestion and enhance immunity, have gained considerable attention. For instance, a study by the Center for Dairy Technology in Brazil identified specific strains of Lactobacillus in traditional cheeses that enhance gut health without altering the cheese's composition. Consumers are actively seeking functional foods that provide health benefits beyond basic nutrition, and probiotic cheese perfectly aligns with this trend. The integration of beneficial microorganisms in cheese offers a palatable and convenient option for maintaining gut health, thereby boosting its market appeal among health-conscious individuals.
Growing Demand for Functional and Fortified Foods:
The global shift towards functional and fortified foods has further propelled the probiotic cheese market. Modern consumers are increasingly looking for food products that cater to specific health needs, such as improving digestion, reducing inflammation, and boosting the immune system. Probiotic cheese, with its dual advantage of being a nutrient-rich dairy product and a carrier of probiotics, fulfills these demands effectively. For example, Turkish white cheese ripened with probiotic cultures such as Lactobacillus acidophilus and Bifidobacterium bifidum maintained probiotic levels above the effective threshold (≥10^7^ cfu/g) throughout the ripening process. This growing preference for functional foods has encouraged manufacturers to innovate and diversify their probiotic cheese offerings, further fueling market growth.
Expansion of the Dairy Industry and Innovations in Cheese Production:
The expansion of the dairy industry and advancements in cheese production technology have significantly contributed to the growth of the probiotic cheese market. Producers are leveraging state-of-the-art fermentation techniques and microbial research to ensure the viability and efficacy of probiotics in cheese products. This focus on innovation has resulted in better-tasting, longer-lasting probiotic cheeses with enhanced health benefits. Additionally, the rising investments in research and development by key players have made probiotic cheese more accessible to a broader consumer base, encouraging market expansion.
Increasing Popularity in Emerging Markets:
The probiotic cheese market is witnessing substantial growth in emerging markets, where rising disposable incomes and urbanization have led to increased consumer interest in premium and health-focused food products. Countries in Asia-Pacific and Latin America are particularly showing robust demand for probiotic cheese, driven by their growing awareness of probiotics' health benefits and the influence of global dietary trends. The availability of probiotic cheese in modern retail outlets, coupled with targeted marketing campaigns, has further enhanced its adoption in these regions.
Market Trends:
Rising Preference for Plant-Based and Non-Dairy Probiotic Cheese:
A notable trend in the probiotic cheese market is the increasing consumer demand for plant-based and non-dairy alternatives. With the growing prevalence of lactose intolerance and the rise of vegan diets, manufacturers are innovating to produce probiotic cheese from almond, soy, coconut, and cashew bases. For instance, In April 2024, Mane developed comprehensive plant-based cheese alternatives with specific flavor profiles including mozzarella, Emmental, cheddar, gouda, blue cheese, and goat cheese. These products not only cater to dietary restrictions but also appeal to environmentally conscious consumers who prioritize sustainable food choices. The plant-based probiotic cheese segment is expected to grow at a rapid pace, driven by the expanding vegan population and increasing availability of high-quality, flavorful options in both developed and emerging markets.
Customization and Expansion of Flavored Probiotic Cheeses:
The trend of customization and flavor innovation has gained significant traction in the probiotic cheese market. Consumers today seek unique and exotic flavors, spurring manufacturers to diversify their product portfolios with options like herb-infused, spiced, and smoked probiotic cheeses. Additionally, personalization trends are emerging, with brands offering customizable cheese packs that allow consumers to choose specific probiotic strains tailored to their health needs. This focus on flavor and customization is broadening the appeal of probiotic cheese to a wider audience, including younger consumers and food enthusiasts.
Growth of E-Commerce and Digital Marketing:
The proliferation of e-commerce platforms has transformed the way probiotic cheese reaches consumers. Online retail channels have become essential for the distribution of niche and specialized food products, including probiotic cheese. The convenience of doorstep delivery, coupled with digital marketing strategies, has allowed manufacturers to target health-conscious consumers more effectively. Brands are leveraging social media, influencer collaborations, and interactive content to highlight the benefits of probiotic cheese, making it a staple for health-oriented consumers. This shift has particularly benefited small and emerging players, enabling them to compete in a market traditionally dominated by established dairy companies.
Focus on Sustainable and Clean-Label Products:
Sustainability and clean-label demands are reshaping the probiotic cheese market, as consumers increasingly scrutinize product ingredients and production methods. Manufacturers are responding by adopting environmentally friendly practices, such as reducing carbon footprints, using renewable energy in production, and incorporating recyclable packaging. At the same time, clean-label probiotic cheeses, made with minimal processing and natural ingredients, are gaining traction among health-conscious consumers. For instance, Clean-label preferences have become pronounced, with 63% of US consumers preferring products with easily understood ingredients in 2023. This trend reflects a broader shift toward transparency and environmental responsibility, aligning with consumer preferences for ethical and health-driven food choices.
Market Restraints and Challenges:
High Production Costs and Limited Accessibility:
One of the key restraints in the probiotic cheese market is the high cost associated with production. Incorporating live probiotic cultures into cheese requires advanced fermentation techniques, stringent quality control measures, and specialized storage solutions to ensure the viability of probiotics. These factors significantly increase production costs, making probiotic cheese more expensive than conventional alternatives. This price disparity limits its accessibility, particularly in cost-sensitive markets, thereby constraining overall market penetration.
Short Shelf Life of Probiotic Products:
Maintaining the viability of probiotics throughout the product's shelf life poses a significant challenge for manufacturers. Probiotic microorganisms are sensitive to environmental factors such as temperature, humidity, and packaging conditions, which can reduce their effectiveness over time. Ensuring the survival of probiotics while retaining the flavor, texture, and nutritional quality of the cheese requires sophisticated preservation methods, which add to the complexity and cost of production. This limitation impacts both product reliability and consumer confidence.
Regulatory and Labeling Challenges:
The probiotic cheese market faces stringent regulatory requirements across different regions, particularly concerning health claims and labeling standards. Regulatory authorities often require extensive scientific evidence to validate the health benefits of probiotic products, which can be time-consuming and expensive to obtain. Inconsistent regulations across markets further complicate international trade, limiting the expansion of probiotic cheese in global markets. These challenges demand significant resources and expertise, creating barriers for smaller manufacturers and new entrants.
Consumer Skepticism and Lack of Awareness:
Despite growing interest in probiotics, many consumers remain skeptical about the claimed health benefits of probiotic cheese. A lack of widespread understanding regarding the role of probiotics in overall health, coupled with limited education on how probiotic cheese differs from regular cheese, hampers adoption. This challenge underscores the need for robust marketing strategies and consumer education to build trust and awareness.
Market Segmentation Analysis:
The probiotic cheese market is segmented based on cheese type, bacteria type, and sales channel, each playing a pivotal role in shaping the market dynamics.
By cheese type, varieties such as Swiss, Feta, Parmesan, Cheddar, Cottage, Provolone, Gouda, and others cater to diverse consumer preferences. Cheddar and Gouda dominate the market due to their widespread popularity and adaptability to probiotic integration, while Feta and Cottage cheese appeal to health-conscious consumers seeking lower-fat options. Specialty types like Swiss and Parmesan also hold a niche market, driven by premiumization trends.
By bacteria type, the market includes Lactobacillus, Streptococcus, Bifidobacterium, Bacillus Coagulants, Saccharomyces, Lactococcus Lactis, and others. Lactobacillus and Bifidobacterium are the most commonly used strains due to their proven health benefits and stability in dairy products. Innovations in bacterial formulations are enabling producers to tailor probiotic profiles to meet specific health needs, further expanding consumer appeal.
By sales channel, hypermarkets and supermarkets lead the distribution network, offering a wide variety of probiotic cheese options under one roof. Specialty stores and health and wellness outlets cater to niche consumer segments seeking premium or organic variants. E-commerce is rapidly gaining traction, driven by the convenience of online shopping and the availability of detailed product information. Other channels, such as convenience and departmental stores, also contribute to the market, ensuring accessibility across urban and rural regions.
Segmentation:
By Cheese Type:
- Swiss
- Feta
- Parmesan
- Cheddar
- Cottage
- Provolone
- Gouda
- Others
By Bacteria Type:
- Lactobacillus
- Streptococcus
- Bifidobacterium
- Bacillus Coagulants
- Saccharomyces
- Lactococcus Lactis
- Others
By Sales Channel:
- Hypermarkets / Supermarkets
- Specialty Stores
- E-commerce
- Health & Wellness Stores
- Convenience Stores
- Departmental Stores
- Others
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis:
The probiotic cheese market exhibits distinct regional trends, with Europe holding the largest market share, accounting for approximately 35% of the global market in 2023. The region’s dominance is driven by its mature dairy industry, high consumer awareness, and strong emphasis on health and wellness. Countries like Germany, France, and the Netherlands are at the forefront, with robust production capacities and innovative product launches catering to diverse consumer preferences.
North America follows as the second-largest market, capturing around 30% of the global share. The U.S. and Canada have witnessed a surge in demand for functional foods, driven by increasing health consciousness and rising incidences of digestive disorders. The region also benefits from a well-established retail infrastructure and growing penetration of premium and organic probiotic cheese products.
The Asia-Pacific region represents a rapidly growing market, accounting for approximately 20% of the global share. Countries such as China, Japan, and India are driving growth through urbanization, changing dietary habits, and increased awareness of probiotic benefits. The expanding middle-class population and rising disposable incomes further bolster demand in this region.
Latin America, the Middle East, and Africa collectively account for the remaining 15% of the global market. While these regions have smaller market shares, they show promising potential due to rising consumer interest in health-oriented products and increasing investments in retail and distribution networks. Brazil and South Africa are emerging as key markets within these regions, with growth fueled by improved economic conditions and heightened awareness of functional foods.
Key Player Analysis:
- Beehive Cheese
- BelGioioso
- Cabot Creamery
- Danone SA
- East Hill Creamery
- Good Culture
- The probiotic cheese Co.
- Vermont Farmstead Cheese Co.
Competitive Analysis:
The probiotic cheese market is characterized by intense competition, with both global and regional players vying for market share. Key players such as Nestlé, Arla Foods, and Danone dominate the landscape, leveraging their robust distribution networks and strong brand equity. These companies focus on continuous product innovation and strategic partnerships to maintain their competitive edge. Regional players, particularly in Europe and Asia-Pacific, also contribute significantly by offering niche and locally adapted products. The growing demand for premium and organic probiotic cheese has encouraged new entrants, further intensifying competition. Companies are increasingly investing in marketing campaigns and educational initiatives to promote the health benefits of probiotic cheese, thereby expanding their consumer base.
Recent Developments:
- In October 2023, Probi (Sweden) unveiled new synbiotic solutions in collaboration with Clasado (UK) at Supply Side West. They launched Bimuno GOS combined with Probi Defendum and Probi Digestis, marking a strategic entry into the growing synbiotics sector.
- In February 2024, AB Biotics SA (Netherlands) expanded its presence in Asia by partnering with Wonderlab to introduce Shape100, a probiotic blend focusing on cardiometabolic health, to the Chinese market.
Market Concentration & Characteristics:
The probiotic cheese market is moderately concentrated, with a mix of established dairy giants and emerging players contributing to its competitive landscape. Key industry leaders leverage their extensive distribution networks, advanced production capabilities, and strong brand recognition to maintain dominance. At the same time, smaller and regional manufacturers are carving out niches by offering innovative and specialized probiotic cheese products, such as plant-based or customized variants. The market is characterized by high innovation intensity, as companies focus on improving product quality, extending shelf life, and incorporating diverse probiotic strains to cater to evolving consumer preferences. Regulatory compliance and adherence to quality standards play a pivotal role in shaping market dynamics, adding a layer of complexity for new entrants. Additionally, increasing investments in research and development, coupled with strategic partnerships and acquisitions, are defining features of this market, as players aim to expand their product portfolios and geographic presence.
Report Coverage:
The research report offers an in-depth analysis based on By Cheese Type, By Bacteria Type and By Sales Channel. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook:
- The probiotic cheese market is expected to witness robust growth due to rising consumer demand for functional foods promoting gut health.
- Technological advancements in fermentation and preservation will enhance product quality and shelf life.
- Plant-based probiotic cheese will emerge as a significant growth segment, driven by the increasing popularity of vegan diets.
- Expansion into emerging markets like Asia-Pacific and Latin America will provide substantial opportunities due to rising urbanization and disposable incomes.
- Innovations in flavor profiles and customizable probiotic blends will attract younger and health-conscious consumers.
- E-commerce platforms will play a pivotal role in market penetration, enabling wider access to niche probiotic cheese products.
- Sustainability efforts, such as eco-friendly packaging and clean-label ingredients, will shape consumer preferences and industry practices.
- Strategic collaborations between dairy producers and biotech firms will accelerate the development of advanced probiotic strains.
- Increasing government initiatives supporting health-focused food products will boost market adoption globally.
- Enhanced consumer education campaigns will help overcome skepticism and build trust in the health benefits of probiotic cheese.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the projected size of the probiotic cheese market by 2032?
What is the expected CAGR for the probiotic cheese market during 2024–2032?
What is driving the growth of the probiotic cheese market?
Which regions dominate the probiotic cheese market?
What challenges does the probiotic cheese market face?
Table of Content
Chapter 1. Report Introduction
- 1.1 Report Description & Purpose
- 1.1.1 Report Title & Market Definition
- 1.1.2 Unique Selling Propositions (USP) & Key Differentiators
- 1.1.3 Value Proposition for Stakeholders
- 1.2 Research Objectives
- 1.2.1 Market Sizing Objectives (Volume & Revenue)
- 1.2.2 Segmentation Objectives
- 1.2.3 Competitive Intelligence Objectives
- 1.2.4 Forecast & Scenario Objectives
- 1.3 Report Scope
- 1.3.1 Probiotic Cheese Scope – Types & Subtypes Covered
- 1.3.2 Geographic Scope – Regions & Countries Covered
- 1.3.3 Historical Period, Base Year & Forecast Period (2024; forecast to 2032)
- 1.3.4 Inclusions & Exclusions
- 1.4 HS Code & Classification Framework
- 1.5 Currency, Units & Pricing Basis
- 1.6 Target Stakeholders
- 1.7 Limitations & Assumptions
Chapter 2. Executive Summary
- 2.1 Global Probiotic Cheese Market Snapshot
- 2.1.1 Market Size – Historical (2024) & Forecast (2024-2032) (2024: USD 527.7 million → 2032: USD 1,659.71 million)
- 2.1.2 Volume & Revenue – Global Totals
- 2.1.3 Key Market Highlights – Top Five Facts
- 2.2 Probiotic Cheese Market Segmentation Snapshot
- 2.2.1 Market Split by Region – 2024 vs. 2032
- 2.3 Competitive Snapshot
- 2.3.1 Top 10 Players by Revenue Share – 2024
- 2.3.2 Top 10 Players by Volume Share – 2024
- 2.3.3 Recent Strategic Developments (18-Month Summary)
- 2.4 Key Investment Highlights & Strategic Conclusions
Chapter 3. Probiotic Cheese Market Dynamics & Industry Analysis
- 3.1 Market Overview & Context
- 3.1.1 Probiotic Cheese Market Position in the Broader Automotive Value Chain
- 3.1.2 OEM vs. Replacement Market Dynamics
- 3.1.3 Market Maturity & Development Stage by Region
- 3.2 Probiotic Cheese Market Drivers
- 3.3 Probiotic Cheese Market Restraints & Challenges
- 3.4 Probiotic Cheese Market Opportunities
- 3.5 Porter's Five Forces Analysis
- 3.5.1 Threat of New Entrants
- 3.5.2 Bargaining Power of Suppliers
- 3.5.3 Bargaining Power of Buyers
- 3.5.4 Threat of Substitutes
- 3.5.5 Competitive Rivalry – Intensity Assessment
- 3.6 Probiotic Cheese Value Chain Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.6.1.1 Raw Material/Input 1
- 3.6.1.2 Raw Material/Input 2
- 3.6.1.3 Raw Material/Input 3
- 3.6.2 Midstream – Production/Manufacturing/Service Delivery
- 3.6.2.1 Production/Process Overview
- 3.6.2.2 Key Facility Locations & Capacity by Manufacturer
- 3.6.3 Downstream – Distribution & End Consumer
- 3.6.3.1 Primary Channel – B2B/OEM
- 3.6.3.2 Secondary Channels – Dealer, Retail, Online, Direct
- 3.6.4 Value Chain Profitability Analysis
- 3.6.1 Upstream – Raw Material/Input Suppliers
- 3.7 PESTEL Analysis
- 3.7.1 Political Factors
- 3.7.2 Economic Factors
- 3.7.3 Social Factors
- 3.7.4 Technological Factors
- 3.7.5 Environmental Factors
- 3.7.6 Legal Factors
- 3.8 Probiotic Cheese Supply Chain Analysis
- 3.8.1 Raw Material/Input Supply Risk Assessment
- 3.8.2 Manufacturing Concentration Risk (Geographic Exposure)
- 3.8.3 Trade Disruption Impact Analysis
- 3.9 Regulatory & Policy Landscape
Note: The regulatory and policy landscape section covers regulations based on their applicability to the market, Probiotic Cheese category, geography, and scope of the study. Only regulatory frameworks with a material impact on operations, compliance, trade, sustainability, or market access are analyzed in detail.
Chapter 4. Key Investment Pockets & Opportunity Analysis
- 4.1 Probiotic Cheese Market Attractiveness Analysis
- 4.1.1 By Region – Investment Attractiveness Matrix (Volume × CAGR)
- 4.2 Absolute Revenue Growth Opportunity
- 4.2.1 By Region – Absolute USD Growth Through 2032
- 4.3 Incremental Volume Opportunity
- 4.3.1 By Region – Incremental Volume Through 2032
- 4.3.2 Segment – Incremental Volume
- 4.4 Emerging Submarket Opportunity Deep Dive (Subject to Applicability)
- 4.5 Emerging Market Opportunity Scorecards
- 4.5.1 United States
- 4.5.2 Europe
- 4.5.3 Asia
- 4.5.4 Middle East & Africa
Note: Emerging Market Opportunity Scorecards will be included based on relevance and strategic importance. Regions listed are indicative and may vary depending on data availability and market dynamics.
Chapter 5. Probiotic Cheese Import-Export Analysis & Trade Flows
- 5.1 Global Trade Overview
- 5.1.1 Global Export Value by Country (2024)
- 5.1.2 Global Export Volume by Country (2024)
- 5.1.3 Global Import Value by Country (2024)
- 5.1.4 Global Import Volume by Country (2024)
- 5.1.5 Net Trade Balance by Country (2024)
- 5.2 Export Analysis – Segment
- 5.2.1 Type 1 (HS Code)
- 5.2.2 Type 2 (HS Code)
- 5.2.3 Type 3 (HS Code)
- 5.2.4 Type 4 (HS Code)
- 5.2.5 Type 5 (HS Code)
- 5.3 Import Analysis – Segment
- 5.3.1 Type 1 (HS Code)
- 5.3.2 Type 2 (HS Code)
- 5.3.3 Type 3 (HS Code)
- 5.3.4 Type 4 (HS Code)
- 5.3.5 Type 5 (HS Code)
- 5.4 Average Unit Trade Prices
- 5.4.1 Average Export Price – Segment & Country
- 5.4.2 Average Import Price – Segment & Source Country
- 5.4.3 Price Trends (2024)
- 5.5 Key Trade Route Analysis
- 5.5.1 Trade Route 1
- 5.5.2 Trade Route 2
- 5.5.3 Trade Route 3
- 5.5.4 Trade Route 4
- 5.5.5 Trade Route 5
- 5.6 Trade Policy Impact Assessment
- 5.6.1 US Anti-Dumping & Section 301 Tariffs
- 5.6.2 EU Customs Union Impact
- 5.6.3 Major Free Trade Agreements
- 5.6.4 USMCA Rules of Origin
Note: Trade policy analysis will be included only where relevant to the Probiotic Cheese market.
Chapter 6. Competitive Landscape & Company Benchmarking
- 6.1 Probiotic Cheese Market Concentration & Structure
- 6.1.1 Herfindahl-Hirschman Index (HHI) – vs. 2024
- 6.1.2 Tier 1, Tier 2 & Tier 3 Market Structure
- 6.1.3 Global, Regional & Local Player Dynamics
- 6.2 Probiotic Cheese Market Share Analysis – 2024
- 6.2.1 Global Revenue Share by Company
- 6.2.2 Global Volume Share by Company
- 6.2.3 Regional Revenue Share
- 6.2.4 Market Share Evolution ( vs. 2024)
- 6.2.5 OEM Segment Share by Company
- 6.2.6 Replacement Segment Share by Company
- 6.3 Production/Delivery Capacity & Facility Analysis
- 6.3.1 Global Installed Capacity
- 6.3.2 Capacity Utilization Rates
- 6.3.3 Production/Output Volume
- 6.3.4 Facility Locations & Capacity Map
- 6.3.5 Planned Capacity Additions
- 6.4 Probiotic Cheese Competitive Benchmarking Matrix
- 6.4.1 Revenue, Volume, CAGR & Profitability Comparison
- 6.4.2 Channel Revenue Mix
- 6.4.3 Geographic Revenue Exposure
- 6.4.4 R&D Intensity
- 6.4.5 Sustainability Maturity
- 6.5 Strategic Developments in Probiotic Cheese (Last 24 Months)
- 6.5.1 Mergers, Acquisitions & Divestments
- 6.5.2 New Probiotic Cheese Launches
- 6.5.3 Facility Expansions
- 6.5.4 Strategic Alliances, Joint Ventures & Partnerships
- 6.5.5 Distribution Expansion & Market Entry
- 6.5.6 Sustainability & ESG Initiatives
- 6.6 Competitive Strategy Mapping
- 6.6.1 Leader, Challenger, Follower & Niche Classification
- 6.6.2 Pricing Strategy Comparison
- 6.6.3 Channel Strategy Matrix
Note: Strategic developments are included based on their materiality and the availability of reliable information.
Chapter 7. Global Probiotic Cheese Market – By Distribution Channel
- 7.1 Segment Overview
- 7.1.1 Volume & Revenue Split by Channel (2024 & 2032)
- 7.1.2 Channel Mix Evolution (2024-2032)
Chapter 8. Regional Market Analysis – Global Overview
- 8.1 Global Regional Overview
- 8.1.1 Regional Volume Share
- 8.1.2 Regional Revenue Share
- 8.1.3 Regional Volume by Region
- 8.1.4 Regional Revenue by Region
- 8.1.5 Regional Forecast Through 2032
- 8.2 Cross-Regional Segment Analysis
- 8.2.1 By Distribution Channel
- 8.2.2 By Brand/Price Tier
Chapter 9. North America Probiotic Cheese Market
- 9.1 United States
- 9.2 Canada
- 9.3 Mexico
Chapter 10. Europe Probiotic Cheese Market
- 10.1 Germany
- 10.2 France
- 10.3 Italy
- 10.4 United Kingdom
- 10.5 Spain
- 10.6 Poland
- 10.7 Russia
- 10.8 Netherlands
- 10.9 Belgium
- 10.10 Sweden
- 10.11 Denmark
- 10.12 Norway
- 10.13 Rest of Europe
Chapter 11. Asia Pacific Probiotic Cheese Market
- 11.1 China
- 11.2 India
- 11.3 Japan
- 11.4 South Korea
- 11.5 Thailand
- 11.6 Indonesia
- 11.7 Vietnam
- 11.8 Malaysia
- 11.9 Australia
- 11.10 Rest of Asia Pacific
Chapter 12. Latin America Probiotic Cheese Market
- 12.1 Brazil
- 12.2 Argentina
- 12.3 Colombia
- 12.4 Chile
- 12.5 Rest of Latin America
Chapter 13. Middle East Probiotic Cheese Market
- 13.1 Saudi Arabia
- 13.2 United Arab Emirates
- 13.3 Turkey
- 13.4 Israel
- 13.5 Iran
- 13.6 Rest of the Middle East
Chapter 14. Africa Probiotic Cheese Market
- 14.1 South Africa
- 14.2 Egypt
- 14.3 Nigeria
- 14.4 Morocco
- 14.5 Rest of Africa
Chapter 15. Probiotic Cheese Company Profiles
- 15.1 [Company 01]
- 15.1.1 Company Overview
- 15.1.2 Key Management Personnel
- 15.1.3 Products & Services Portfolio
- 15.1.4 Financial Performance
- 15.1.5 Key Market Focus & Geographic Presence
- 15.1.6 Recent Developments & Strategic Initiatives
Note: The company profile list is preliminary and may change based on research findings, market developments, data availability, and client requirements.
Chapter 16. Appendices
- Appendix A – List of Abbreviations & Acronyms
- Appendix B – Industry Classification Code Reference – Full Series
- Appendix C – Production & Capacity Data Tables
- Appendix D – End-Use & Demand Base Tables
- Appendix E – Consumption & Replacement Rate Assumptions
- Appendix F – ASP Reference Tables
- Appendix G – Manufacturing & Facility Database
- Appendix H – Import-Export Data Tables
- Appendix I – Regulatory Summary Tables
- Appendix J – Primary Research Participant List (Anonymized)
- Appendix K – Primary Research Questionnaire Framework
- Appendix L – Data Sources & Bibliography
- Appendix M – Market Size Divergence & Source Comparison
Chapter 17. Research Methodology
- 17.1 Research Framework & Philosophy
- 17.2 Secondary Research – Sources, Hierarchy & Data Extraction
- 17.3 Data Modeling – Bottom-Up & Top-Down Market Sizing
- 17.4 Primary Research – Stakeholder Framework, LOI & Sample Sizes
- 17.5 Forecast Methodology – Regression, Scenario & Sensitivity Analysis
- 17.6 Quality Control – Four-Layer Validation Framework
- 17.7 Limitations & Standard Assumptions
- 17.8 Disclaimer
