
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2019-2022 |
| Base Year | 2023 |
| Forecast Period | 2024-2032 |
| Produce Bag Market Size 2024 | USD 658.1 million |
| Produce Bag Market, CAGR | 5.2% |
| Produce Bag Market Size 2032 | USD 987.22 million |
Market Overview
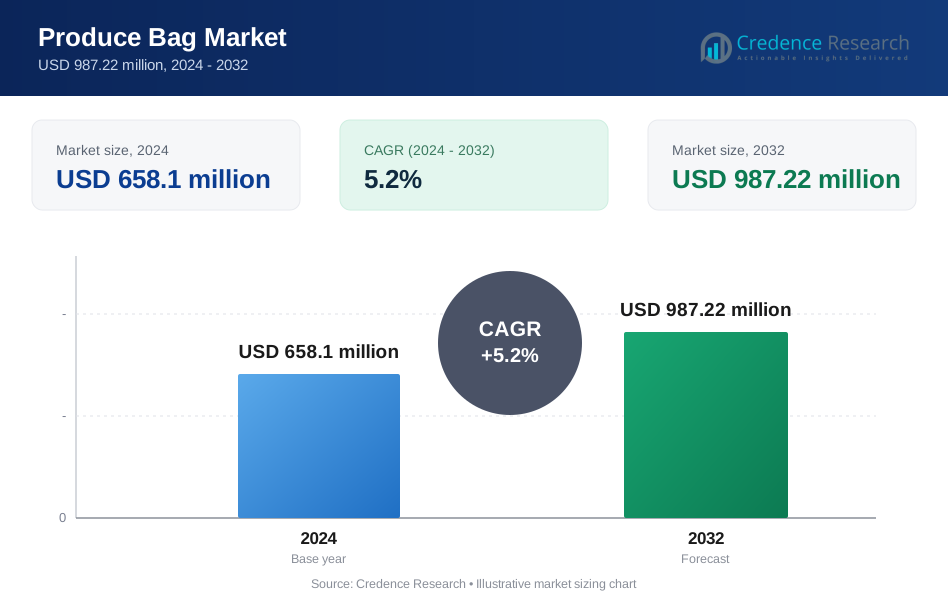
The global produce bag market is projected to grow from USD 658.1 million in 2024 to USD 987.22 million by 2032, reflecting a compound annual growth rate (CAGR) of 5.2% during the forecast period.
The produce bag market is driven by increasing consumer demand for sustainable and reusable packaging solutions amid growing environmental concerns. The shift towards reducing single-use plastics, supported by stringent government regulations, has fueled the adoption of eco-friendly produce bags. Rising awareness about food safety and hygiene further boosts market growth, as these bags help extend the freshness of fruits and vegetables. Additionally, advancements in biodegradable materials and innovative designs, such as breathable or moisture-resistant bags, are enhancing product appeal. The expanding retail sector and preference for convenient shopping solutions are also key trends propelling the market's steady growth trajectory.
The global produce bag market is witnessing significant growth across various regions, with North America and Asia-Pacific leading the charge due to rising environmental awareness and increasing demand for sustainable packaging. Key players such as Mondi Group, DS Smith Plc, Amcor PLC, and Smurfit Kappa Group are spearheading innovation in eco-friendly produce bags, offering alternatives like biodegradable and reusable materials. Other prominent companies, including Sealed Air Corporation, WestRock Company, and Berry Global Group, are also contributing to market expansion by developing sustainable solutions that cater to both retail and household demands.
Market Drivers
Retail Sector Trends
Retailers are adopting innovative approaches to align with zero-waste initiatives and meet the growing demand for sustainable packaging options. The promotion of reusable bags, including produce bags, is a central aspect of their strategies to minimize single-use plastic consumption. For instance, a report by IFCO Systems notes that rising consumer awareness is driving companies towards the adoption of circular packaging solutions. Retailers are also responding to consumer preferences by offering eco-friendly produce bags made from sustainable materials, enhancing customer satisfaction and brand loyalty. This trend underlines the retail sector's pivotal role in encouraging environmentally conscious consumer behavior.
Government Regulations and Bans on Single-Use Plastics
Stringent government regulations targeting plastic pollution are significantly influencing the produce bag market. Many countries have enacted bans on single-use plastic bags, creating a strong demand for reusable alternatives. For instance, India's Plastic Waste Management Amendment Rules, 2021, prohibit the manufacture, import, stocking, distribution, sale, and use of identified single-use plastic items. Additionally, government incentives and subsidies for eco-friendly practices are further boosting the adoption of produce bags. These measures not only support sustainable product innovation but also foster a broader cultural shift towards environmental responsibility.
Growing Environmental Awareness and Sustainability Initiatives
The increasing global emphasis on sustainability is a key driver for the produce bag market. Consumers and governments alike are prioritizing eco-friendly alternatives to mitigate the environmental impact of plastic waste. This shift has significantly boosted demand for biodegradable and reusable produce bags, offering a sustainable solution to conventional plastic bags. The growing awareness of plastic pollution's harmful effects on ecosystems and marine life has further accelerated this movement. By providing reusable and environmentally responsible options, produce bags contribute to global efforts to reduce plastic consumption and promote greener practices.
Rising Consumer Preference for Organic and Fresh Produce
The rising health consciousness among consumers is fostering a preference for organic and fresh produce, directly influencing the need for effective and sustainable packaging solutions. Organic products, which often require specialized packaging to preserve their freshness and quality, benefit from the use of produce bags. These bags ensure product integrity during storage and transportation while minimizing the ecological footprint. As consumers increasingly align their purchasing decisions with health and environmental priorities, the role of produce bags in supporting these preferences continues to expand.
Market Trends
Shift Towards Sustainable Materials and Innovative Features
The produce bag market is experiencing a transformative shift towards sustainability, driven by the adoption of eco-friendly materials and innovative designs. Biodegradable and compostable bags, made from materials like cornstarch or plant-based polymers, are gaining traction as they naturally decompose over time, reducing environmental impact. For instance, a report by the European Bioplastics Association highlights that biodegradable plastics made from renewable resources are increasingly being used in packaging. Additionally, recycled materials, such as those derived from post-consumer plastics or paper, offer a practical alternative for eco-conscious consumers. Reusable bags crafted from durable materials like cotton or jute are becoming increasingly popular for their washable, long-lasting attributes, making them a sustainable choice for everyday use. Meanwhile, innovative designs such as mesh bags, which improve airflow to reduce spoilage, and zippered bags, offering secure closures to prevent leaks, are enhancing functionality. Multi-purpose bags are also emerging as a versatile solution, suitable for storing not just produce but also toiletries or electronics, catering to diverse consumer needs.
Growth Through E-Commerce and Regulatory Support
The rise of e-commerce and online grocery shopping is significantly reshaping the produce bag market. Retailers are now offering customizable and eco-friendly packaging solutions tailored to individual consumer preferences, promoting sustainability throughout the supply chain. By adopting biodegradable or recyclable produce bags, online platforms are aligning with growing consumer demand for responsible practices. Concurrently, government regulations banning single-use plastic bags are driving the market toward reusable alternatives. Consumer education campaigns further amplify this trend by raising awareness about the harmful effects of plastic pollution and the advantages of eco-friendly bags. Geographically, the Asia-Pacific region leads the market due to its burgeoning population and expanding middle class, while North America and Europe continue to champion sustainable practices, accelerating the demand for eco-conscious produce bags.
Market Challenges Analysis
Material Costs and Economic Pressures
Fluctuations in the cost of raw materials, particularly biodegradable and organic materials, present a significant challenge in the produce bag market. The prices of materials like plant-based polymers or recycled plastics can vary substantially due to economic factors, including supply chain disruptions, labor shortages, and global trade dynamics. For instance, the Vietnamese Biodegradable Plastics Association notes that biodegradable plastics can be 2-3 times more expensive than traditional plastics. These fluctuations not only impact production costs but also make it difficult for manufacturers to maintain consistent pricing. Additionally, the volatility of these raw material costs puts pressure on companies to balance affordability with sustainability, potentially limiting the widespread adoption of eco-friendly bags. As the market faces increasing demand for sustainable options, companies must adapt to these economic challenges, which could ultimately affect their competitiveness in the marketplace.
Competition and Consumer Challenges
Despite the growing awareness of sustainability, conventional plastic bags remain a formidable competitor due to their low cost, widespread availability, and consumer familiarity. Overcoming consumer habits and preferences that have been ingrained for decades is a significant hurdle for the industry. Additionally, regulatory hurdles related to evolving environmental standards and compliance costs can increase operational overhead. Manufacturers must navigate complex labeling, certification, and testing requirements, which can further raise costs. Furthermore, promoting consumer education around the benefits of reusable and eco-friendly produce bags remains a challenge, as convincing consumers of the long-term value and environmental impact of these alternatives requires ongoing efforts. Balancing these challenges along with ensuring the durability, longevity, and functionality of eco-friendly bags while maintaining cost-effectiveness is crucial to the market’s success.
Market Segmentation Analysis:
By Material:
The produce bag market is segmented by material, with each type catering to different consumer preferences and sustainability goals. Organic cotton bags are highly valued for their natural, eco-friendly properties and are popular among environmentally conscious consumers. These bags offer durability and reusability, making them a preferred choice for shoppers looking to reduce plastic waste. Hemp bags, another sustainable option, are gaining traction due to their strength, biodegradability, and low environmental impact in cultivation. Mesh bags, known for their breathability, are commonly used for storing fresh produce, as they help maintain freshness by allowing air circulation. Plastic bags, though less sustainable, continue to be prevalent due to their low cost and widespread availability. However, their environmental impact is prompting a shift toward more eco-friendly alternatives. Compostable bags, made from plant-based materials, are increasingly popular as they offer a sustainable solution that decomposes naturally, minimizing waste. Each material segment caters to specific market needs, with eco-friendly materials driving the demand for sustainable packaging solutions.
By End Use:
The produce bag market is also segmented based on end use, with key sectors including retail, household, food service, and agriculture & farming. In the retail sector, the demand for produce bags is driven by consumer preferences for sustainable shopping options. Retailers are increasingly offering eco-friendly bags made from materials like organic cotton and compostable plastics to meet consumer expectations for greener alternatives. Household use of produce bags is growing as consumers adopt reusable options for storing fresh produce at home, reducing reliance on disposable plastic. In the food service industry, the need for produce bags is linked to the packaging of fruits and vegetables for restaurants and cafes, where freshness and sustainability are key considerations. Agriculture and farming also contribute to the market, with produce bags used to protect harvested goods during transportation and storage. As sustainability becomes more integral across industries, each segment is witnessing growth driven by increasing awareness of environmental issues and the demand for eco-friendly solutions.
Segments:
Based on Material:
- Organic Cotton
- Hemp
- Mesh
- Plastic
- Compostable Material
Based on End Use:
- Retail
- Household
- Food Service
- Agriculture & Farming
Based on Type:
- Reusable
- Disposable
Based on the Geography:
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- U.K.
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- South-east Asia
- Rest of Asia Pacific
- Latin America
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- GCC Countries
- South Africa
- Rest of the Middle East and Africa
Regional Analysis
North America
North America holds a significant share of the global produce bag market, accounting for approximately 30%. This region is at the forefront of the sustainable packaging movement, driven by stringent government regulations and heightened environmental awareness. The growing demand for eco-friendly alternatives in the retail and household sectors is fueling the market, as consumers increasingly prefer reusable and biodegradable produce bags over single-use plastic. Retailers in North America are responding to these consumer preferences by expanding their range of sustainable products, including produce bags made from organic cotton, hemp, and compostable materials. Additionally, state and local governments in North America are imposing bans on single-use plastics, further driving the adoption of reusable bags. With a robust focus on sustainability, North America is likely to continue leading the market, with growing support from both the government and consumers for eco-conscious initiatives.
Asia-Pacific
The Asia-Pacific region is estimated to hold around 25% of the global market share in 2024. A rapidly growing population and an expanding middle class are major factors driving this demand. As consumers in countries like China, India, and Japan become more aware of environmental issues, the preference for sustainable packaging solutions, including eco-friendly produce bags, is increasing. Additionally, there is a rising focus on reducing plastic waste, with governments and businesses in the region adopting stricter regulations and promoting the use of biodegradable and reusable bags. Retailers in Asia-Pacific are also beginning to cater to this shift by offering a wider variety of sustainable produce bag options. Given the large population base and rising environmental consciousness, the Asia-Pacific region represents a substantial market opportunity, with strong growth expected over the forecast period.
Key Player Analysis
- Amcor PLC
- Smurfit Kappa Group PLC
- Sealed Air Corporation
- WestRock Company
- Pactiv Evergreen Inc.
- Mondi Group
- DS Smith Plc
- Georgia Pacific LLC
- International Paper Company
- Berry Global Group, Inc.
Competitive Analysis
The competitive landscape of the produce bag market is shaped by major players like Mondi Group, DS Smith Plc, Amcor PLC, Sealed Air Corporation, WestRock Company, International Paper Company, Smurfit Kappa Group PLC, Berry Global Group, Inc., Pactiv Evergreen Inc., and Georgia Pacific LLC. These companies are focused on innovation and sustainability, with a strong emphasis on developing eco-friendly alternatives to traditional plastic bags. By utilizing materials like organic cotton, hemp, and compostable polymers, they are responding to the growing consumer demand for biodegradable and reusable produce bags. Leading players are also investing in new manufacturing technologies to improve the durability, functionality, and cost-effectiveness of their products. To maintain a competitive edge, these companies are expanding their product portfolios, offering customizable solutions to various industries such as retail, food service, and agriculture. Strategic partnerships and mergers are also a common strategy to enhance market presence and sustainability efforts.
Recent Developments
- In August 2023, Hefty reintroduced its limited-edition Hefty Cinnamon Pumpkin Spice Ultra Strong trash bags. These trash bags come in a festive Cinnamon Pumpkin Spice scent and offer features such as flex strength, secure-fit closure, odor control, and resistance to leaks, punctures, and rips. The product was available at select retailers, including Amazon and Walmart, in various pack sizes.
- In March 2023, Berry Global relaunched its Green Sack range of refuse sacks, which are made from over 90% recycled agricultural and post-consumer plastic waste. The range is packed in a more convenient-to-use dispenser box for cleaning, hospitality, and facilities management sectors. Green Sack range is used in a variety of applications from facilities management, and healthcare to local authorities. Sacks are manufactured using the CHSA Refuse Sack Standard and are available in a large variety of sizes. Besides, it is thinner, stronger, and more sustainable, and is manufactured from UK waste at Berry Global's UK facilities, helping to conserve resources and reduce landfill.
Market Concentration & Characteristics
The produce bag market exhibits moderate concentration, with a mix of large multinational companies and regional players driving competition. Leading companies such as Mondi Group, DS Smith Plc, Amcor PLC, and Smurfit Kappa Group dominate the market due to their extensive resources, global supply chains, and strong brand presence. These companies focus on innovation and sustainability, providing a diverse range of eco-friendly packaging solutions. The market is characterized by a growing demand for biodegradable, reusable, and compostable produce bags as consumers increasingly prioritize sustainability. Additionally, regulatory changes and rising awareness of environmental issues are pushing companies to develop alternatives to single-use plastic bags. Smaller, regional players often differentiate themselves through niche products or by focusing on specific materials like organic cotton or hemp. Overall, the market is evolving rapidly with a clear trend toward sustainable packaging, driven by both consumer preferences and stricter environmental regulations.
Report Coverage
The research report offers an in-depth analysis based on Material, End Use, Type and Geography. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- The demand for eco-friendly produce bags is expected to grow as consumers prioritize sustainability.
- Government regulations banning single-use plastics will continue to drive the adoption of reusable produce bags.
- Biodegradable and compostable materials will gain more market share due to their environmental benefits.
- The retail sector will see increased use of produce bags made from organic cotton, hemp, and recycled materials.
- Technological advancements will improve the durability and functionality of eco-friendly produce bags.
- Rising consumer awareness about the harmful effects of plastic pollution will boost market growth.
- E-commerce platforms will play a significant role in promoting sustainable packaging solutions.
- Retailers will expand their range of sustainable produce bags to meet growing consumer demand.
- Supply chain efficiencies will improve, reducing costs and making eco-friendly bags more affordable.
- The market will likely witness increased collaborations between manufacturers and retailers to promote eco-conscious products.
Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Market Dynamics
Retail Sector Trends
Retailers are increasingly adopting sustainable packaging solutions, including reusable and compostable produce bags, to align with zero-waste initiatives and meet consumer demand for eco-friendly shopping options. This shift is enhancing customer loyalty and driving market growth.
Government Regulations and Bans on Single-Use Plastics
Stringent regulations and outright bans on single-use plastic bags in many countries are compelling both retailers and consumers to switch to reusable and biodegradable produce bags, significantly boosting market adoption.
Growing Environmental Awareness and Sustainability Initiatives
Rising global awareness of plastic pollution and its environmental impact is pushing consumers and businesses toward sustainable alternatives, increasing demand for biodegradable and reusable produce bags.
Rising Consumer Preference for Organic and Fresh Produce
As consumers become more health-conscious and seek organic, fresh produce, the need for packaging that preserves freshness and reduces environmental impact is growing, supporting the adoption of specialized produce bags.
Advancements in Biodegradable Materials and Innovative Designs
Ongoing innovation in materials such as plant-based polymers and new bag designs (e.g., breathable mesh, moisture-resistant features) is making eco-friendly produce bags more functional and attractive, further driving market expansion.
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current size of the Produce Bag market?
What factors are driving the growth of the Produce Bag market?
What are the key segments within the Produce Bag market?
Who are the major players in the Produce Bag market?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
- 1.2 By Type
- 1.2.1 Reusable
- 1.2.2 Disposable
- 1.3 By End Use
- 1.3.1 Retail
- 1.3.2 Household
- 1.3.3 Food Service
- 1.3.4 Agriculture & Farming
- 1.4 By Material
- 1.4.1 Organic Cotton
- 1.4.2 Hemp
- 1.4.3 Mesh
- 1.4.4 Plastic
- 1.4.5 Compostable Material
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 658.1 million → 2032: USD 987.22 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Produce Bag Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Produce Bag Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Produce Bag Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Produce Bag Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Produce Bag Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Produce Bag Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Produce Bag Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Produce Bag Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 658.1 million → 2032: USD 987.22 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Produce Bag Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 By Type - Market Size and Forecast, 2024-2032
- 12.3.1 Segment Definition and Scope
- 12.3.2 Historical Market Size
- 12.3.3 Revenue Forecast, 2024-2032
- 12.3.4 Volume Forecast, 2024-2032
- 12.3.5 Base-Year Market Share, 2024
- 12.3.6 Segment CAGR and Growth Drivers
- 12.3.7 Subsegment Market Size and Forecast
- 12.3.7.1 Reusable
- 12.3.7.2 Disposable
- 12.3.8 Subsegment Pricing and Adoption Trends
- 12.3.9 Leading Suppliers and Competition
- 12.3.10 Regional Demand and Opportunities
- 12.4 By End Use - Market Size and Forecast, 2024-2032
- 12.4.1 Segment Definition and Scope
- 12.4.2 Historical Market Size
- 12.4.3 Revenue Forecast, 2024-2032
- 12.4.4 Volume Forecast, 2024-2032
- 12.4.5 Base-Year Market Share, 2024
- 12.4.6 Segment CAGR and Growth Drivers
- 12.4.7 Subsegment Market Size and Forecast
- 12.4.7.1 Retail
- 12.4.7.2 Household
- 12.4.7.3 Food Service
- 12.4.7.4 Agriculture & Farming
- 12.4.8 Subsegment Pricing and Adoption Trends
- 12.4.9 Leading Suppliers and Competition
- 12.4.10 Regional Demand and Opportunities
- 12.5 By Material - Market Size and Forecast, 2024-2032
- 12.5.1 Segment Definition and Scope
- 12.5.2 Historical Market Size
- 12.5.3 Revenue Forecast, 2024-2032
- 12.5.4 Volume Forecast, 2024-2032
- 12.5.5 Base-Year Market Share, 2024
- 12.5.6 Segment CAGR and Growth Drivers
- 12.5.7 Subsegment Market Size and Forecast
- 12.5.7.1 Organic Cotton
- 12.5.7.2 Hemp
- 12.5.7.3 Mesh
- 12.5.7.4 Plastic
- 12.5.7.5 Compostable Material
- 12.5.8 Subsegment Pricing and Adoption Trends
- 12.5.9 Leading Suppliers and Competition
- 12.5.10 Regional Demand and Opportunities
- 12.6 Segment Growth Comparison
- 12.7 Segment Attractiveness and Priority Matrix
Chapter 13 Global Produce Bag End-Use and Application Market Outlook
- 13.1 End-Use Industry and Customer Demand Structure
- 13.2 Leading Applications and Customer Groups
- 13.3 End-Use Market Size, Share and Forecast
- 13.4 Major End-Use Industry Deep Dives
- 13.4.1 Customer Requirements and Use Cases
- 13.4.2 Demand and Replacement Cycles
- 13.4.3 Technical and Regulatory Considerations
- 13.4.4 Purchasing and Procurement Models
- 13.4.5 Leading Vendors and Distribution Channels
- 13.4.6 Forecast and Commercial Opportunities
- 13.5 Emerging Applications and Cross-Segment Demand
- 13.6 End-Use Industry Investment Priorities
Chapter 14 Global Produce Bag Geographic Market Outlook, 2024-2032
- 14.1 Regional Market Size and Share, 2024
- 14.2 Regional Market Forecast, 2024-2032
- 14.3 Regional Pricing, Production and Demand Differences
- 14.4 North America
- 14.4.1 United States
- 14.4.2 Canada
- 14.4.3 Mexico
- 14.5 Europe
- 14.5.1 Germany
- 14.5.2 France
- 14.5.3 Italy
- 14.5.4 United Kingdom
- 14.5.5 Spain
- 14.5.6 Poland
- 14.5.7 Russia
- 14.5.8 Netherlands
- 14.5.9 Belgium
- 14.5.10 Sweden
- 14.5.11 Denmark
- 14.5.12 Norway
- 14.5.13 Rest of Europe
- 14.6 Asia Pacific
- 14.6.1 China
- 14.6.2 India
- 14.6.3 Japan
- 14.6.4 South Korea
- 14.6.5 Thailand
- 14.6.6 Indonesia
- 14.6.7 Vietnam
- 14.6.8 Malaysia
- 14.6.9 Australia
- 14.6.10 Rest of Asia Pacific
- 14.7 Latin America
- 14.7.1 Brazil
- 14.7.2 Argentina
- 14.7.3 Colombia
- 14.7.4 Chile
- 14.7.5 Rest of Latin America
- 14.8 Middle East
- 14.8.1 Saudi Arabia
- 14.8.2 United Arab Emirates
- 14.8.3 Turkey
- 14.8.4 Israel
- 14.8.5 Iran
- 14.8.6 Rest of the Middle East
- 14.9 Africa
- 14.9.1 South Africa
- 14.9.2 Egypt
- 14.9.3 Nigeria
- 14.9.4 Morocco
- 14.9.5 Rest of Africa
- 14.10 Regional Investment, Policy and Supply Chain Differences
- 14.11 Regional Competitive Landscape
- 14.12 Geographic Growth Hotspots
Chapter 15 Global Produce Bag Technology, Innovation and Sustainability Outlook
- 15.1 Technology Landscape and Maturity
- 15.2 Product, Process and Service Innovation
- 15.3 AI, Automation and Digital Tools in the Industry
- 15.4 Technology Adoption and Performance Benchmarking
- 15.5 Innovation Pipeline and R&D Investment
- 15.6 Patent and Intellectual Property Trends
- 15.7 Energy Efficiency and Resource Management
- 15.8 Sustainability, Recycling and Circularity
- 15.9 Technology Roadmap, 2024-2032
- 15.10 Risks of Obsolescence and Technology Substitution
Chapter 16 Global Produce Bag Market Key Strategic Imperatives
- 16.1 Growth and Market Entry Priorities
- 16.2 High-Return Products and Segments
- 16.3 Pricing, Profitability and Cost Optimization
- 16.4 Technology Investment and Product Differentiation
- 16.5 Supply Chain Localization and Resilience
- 16.6 Distribution and Customer Acquisition
- 16.7 Partnership, Acquisition and Capacity Strategy
- 16.8 Regional Expansion Priorities
- 16.9 Short-, Medium- and Long-Term Actions
Chapter 17 Competition Outlook
- 17.1 Industry Competition Characteristics
- 17.2 Market Structure and Concentration
- 17.3 Market Share and Competitive Positioning, 2024
- 17.4 Company-Wise Revenue and Product Benchmarking
- 17.5 Production and Service Capacity Benchmarking
- 17.6 Technology, Pricing and Differentiation
- 17.7 Regional Footprint and Distribution Strength
- 17.8 Mergers, Acquisitions and Strategic Alliances
- 17.9 New Entrants and Competitive Threats
- 17.10 Porter's Five Forces and Industry Attractiveness
- 17.11 Competitive Outlook, 2024-2032
Chapter 18 Company Profiles
- 18.1 Company Coverage and Selection Criteria
- 18.2 Mondi Group
- 18.2.1 Business Description
- 18.2.2 Company Ownership and Geographic Presence
- 18.2.3 Product and Service Portfolio
- 18.2.4 Manufacturing and Operating Footprint
- 18.2.5 Production Capacity and Expansion Plans
- 18.2.6 Financial Performance and Investment
- 18.2.7 Market Share and Competitive Position
- 18.2.8 Technology and Innovation Capabilities
- 18.2.9 Strategic Alliances or Partnerships
- 18.2.10 Recent Developments
- 18.2.11 Growth Strategy and Outlook
- 18.3 DS Smith Plc
- 18.4 Amcor PLC
- 18.5 Smurfit Kappa Group PLC
- 18.6 Sealed Air Corporation
- 18.7 WestRock Company
- 18.8 Berry Global Group, Inc.
- 18.9 Pactiv Evergreen Inc.
- 18.10 Georgia Pacific LLC
- 18.11 International Paper Company
- 18.12 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 19 Disclaimer
- 19.1 Research and Forecast Disclaimer
- 19.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

