
Market Overview
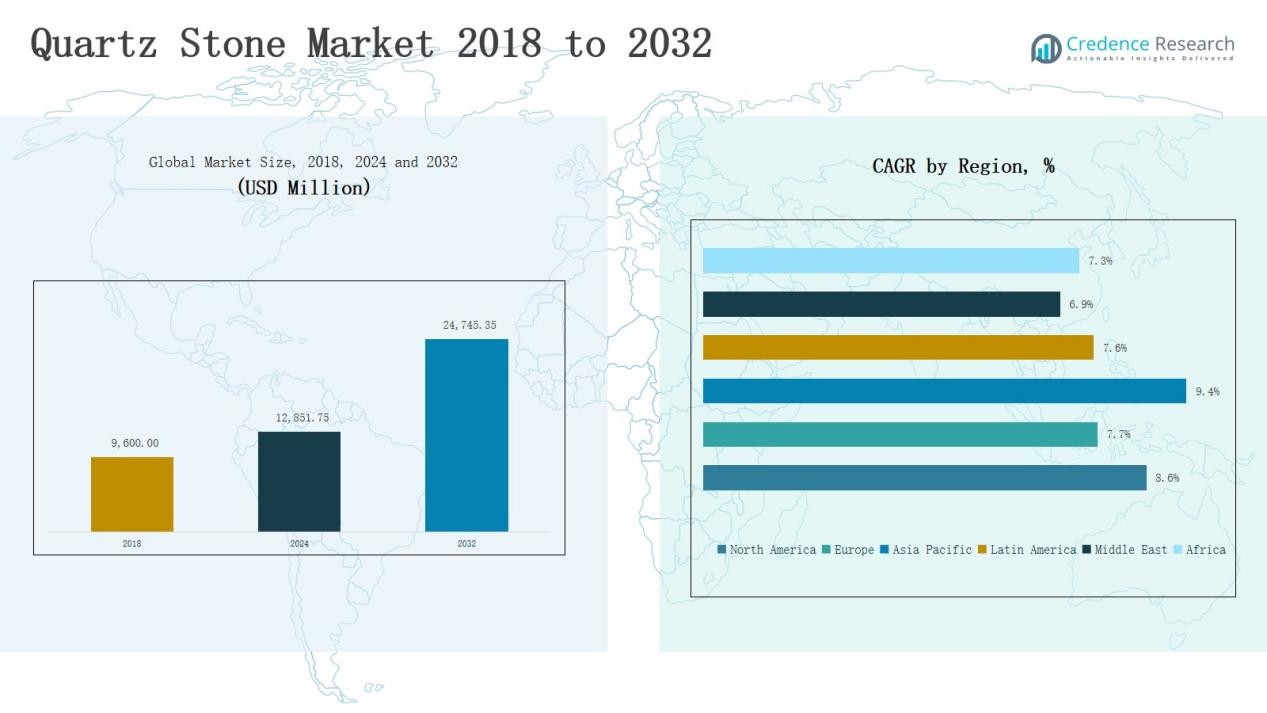
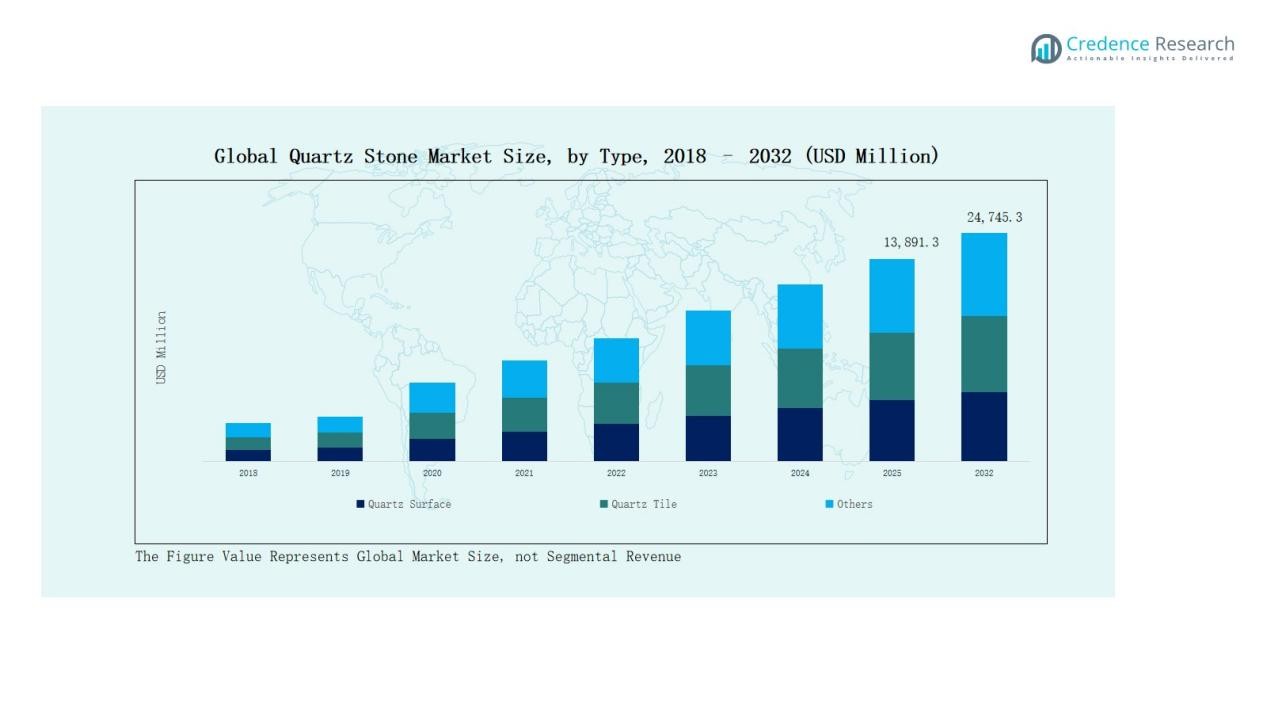
The Quartz Stone Market was valued at USD 9,600.00 million in 2018, increased to USD 12,851.75 million in 2024, and is projected to reach USD 24,745.35 million by 2032, growing at a CAGR of 8.60% during the forecast period.
| REPORT ATTRIBUTE | DETAILS |
|---|---|
| Historical Period | 2020-2023 |
| Base Year | 2024 |
| Forecast Period | 2025-2032 |
| Quartz Stone Market Size 2024 | USD 12,851.75 Million |
| Quartz Stone Market, CAGR | 8.60% |
| Quartz Stone Market Size 2032 | USD 24,745.35 Million |
The Quartz Stone Market is led by key players such as Caesarstone, Cambria, Hanwha L&C, LG Hausys, Vicostone, and DuPont, recognized for their innovation, product diversity, and advanced manufacturing capabilities. These companies focus on engineered quartz production featuring superior durability, aesthetic precision, and sustainable composition. Strategic initiatives such as product launches, capacity expansions, and partnerships strengthen their global footprint across residential and commercial segments. The Asia Pacific region emerged as the leading market in 2024, commanding a 44% share, driven by rapid urbanization, infrastructure expansion, and rising adoption of high-quality interior materials.
Market Insights
- The Quartz Stone Market grew from USD 9,600.00 million in 2018 to USD 12,851.75 million in 2024, projected to reach USD 24,745.35 million by 2032, at a CAGR of 8.60%.
- Asia Pacific led the market with a 44% share in 2024, driven by rapid urbanization, infrastructure growth, and rising use of premium interior materials.
- The Quartz Surface segment dominated by 58% share, fueled by strong demand for countertops, vanities, and wall claddings in residential projects.
- The Residential application segment held 64% share, supported by renovation trends and consumer preference for durable, low-maintenance surfaces.
- Engineered Quartz accounted for the largest 72% share, benefiting from its superior strength, design flexibility, and technological advancements in resin and pigment composition.
Market Segment Insights
By Type:
- For instance, LX Hausys expanded its Viatera Quartz range in South Korea, offering new marble-look designs tailored for premium interior remodeling projects.
By Application:
The Residential segment led the Quartz Stone Market with a 64% share in 2024. Rising home renovation activities and increased adoption of premium interior materials boost segment growth. Consumers prefer quartz for its stain resistance, longevity, and low maintenance, making it ideal for countertops and flooring. The Commercial segment, holding 36%, gains traction from hospitality and corporate construction projects emphasizing durable and aesthetic materials suitable for heavy-use environments and consistent visual appeal.
- For instance, Caesarstone launched its “Metropolitan Collection” in North America, showcasing industrial-inspired quartz slabs designed for modern residential kitchens.
By Material Composition:
The Engineered Quartz segment held a commanding 72% market share in 2024, driven by superior strength, consistent texture, and wide design range. Advancements in resin and pigment technology enhance its appeal across residential and commercial installations. Natural Quartz Stone accounted for 20%, valued for its authenticity and natural grain patterns, while Eco-friendly Quartz represented 8%, witnessing rising adoption due to growing sustainability awareness and increased use of recycled materials in construction and interior design.
Key Growth Drivers
Rising Demand for Premium Interior Applications
The Quartz Stone Market is driven by growing demand for premium interior solutions across residential and commercial spaces. Consumers increasingly prefer quartz for its aesthetic appeal, durability, and low maintenance compared to marble or granite. Expanding real estate construction and remodeling projects, especially in kitchens and bathrooms, fuel consumption. The availability of diverse textures, patterns, and finishes further enhances adoption, positioning quartz as a leading surface material for modern architecture and luxury interior design.
- For instance, Cosentino introduced its Silestone XM Series, which features sustainable, low-silica surfaces with enhanced scratch resistance.
Advancements in Engineered Quartz Technology
Continuous innovation in engineered quartz manufacturing strengthens market growth. Producers integrate advanced resin systems, automated fabrication, and color blending techniques to enhance quality and design flexibility. Improved resistance to stains, impact, and microbial growth increases its suitability for high-traffic and hygiene-sensitive environments. These advancements enable manufacturers to meet evolving consumer demands while maintaining sustainable production standards, resulting in higher efficiency, lower waste generation, and expanding applications in residential and commercial interior design projects globally.
- For instance, Santa Margherita S.p.A., a Verona-based manufacturer of engineered stone, produces and exports marble and quartz agglomerates using a blend of natural materials and resins, with a focus on sustainable manufacturing processes.
Sustainability and Green Building Initiatives
Growing focus on sustainability significantly drives quartz stone adoption. Eco-friendly quartz, incorporating recycled glass and waste materials, aligns with global green building certifications such as LEED and BREEAM. Manufacturers prioritize cleaner production processes and lower carbon footprints to meet environmental regulations. Rising consumer awareness about eco-conscious construction materials further supports segment expansion. This shift toward sustainable materials strengthens quartz stone’s market presence, appealing to environmentally responsible builders, designers, and consumers seeking performance with ecological compliance.
Key Trends & Opportunities
Growing Customization and Design Innovation
A key trend in the Quartz Stone Market is the increasing demand for customized textures, colors, and finishes. Manufacturers leverage digital printing and precision cutting technologies to offer personalized surface designs. The trend toward matte, concrete, and metallic finishes creates new aesthetic possibilities in modern architecture. This innovation-driven customization expands the market’s appeal among interior designers and builders, supporting greater product differentiation and premium pricing strategies in both residential and commercial applications.
- For instance, Cambria Company LLC unveiled Harlow™ Quartz, a premium matte-finish surface developed using precision laser texturing to achieve bespoke tone variations favored by contemporary designers.
Expansion Across Emerging Construction Markets
Rapid urbanization and infrastructure investments in Asia Pacific, Latin America, and the Middle East present major opportunities for market growth. Rising disposable income and lifestyle upgrades drive demand for durable, luxury materials in housing and commercial projects. Expanding retail chains, hotels, and office spaces in developing economies further boost quartz installation. Local production capacity expansion and improved distribution networks also enhance affordability, strengthening the regional foothold of global quartz manufacturers.
- For instance, Compac Surfaces has launched sustainable quartz collections, and The Big 5 is a relevant event in the Middle East, with the next Dubai event in November 2025.
Key Challenges
High Manufacturing and Installation Costs
Quartz stone production involves advanced machinery, precision fabrication, and imported raw materials, resulting in elevated manufacturing costs. Installation also requires skilled labor and specialized tools, increasing overall project expenses. These high costs restrict adoption in price-sensitive markets, particularly in developing regions. Small-scale players struggle to compete with established brands, creating market entry barriers and limiting widespread accessibility of premium quartz products among mid-range consumers.
Environmental Concerns During Production
Despite the shift toward sustainable quartz, environmental concerns persist due to energy-intensive manufacturing and resin emissions. Quartz production generates silica dust, posing occupational health risks when inadequately managed. Regulations on chemical resins and carbon emissions increase compliance costs for manufacturers. Companies must invest in cleaner technologies, filtration systems, and waste recycling to address these challenges, which can affect profitability and slow expansion in markets with strict environmental standards.
Competition from Alternative Surface Materials
The growing availability of alternative materials like porcelain slabs, sintered stone, and solid surfaces poses strong competition. These substitutes often offer comparable aesthetics, lower prices, or enhanced performance in specific applications. Consumer preference diversification challenges quartz producers to sustain market share. To remain competitive, manufacturers must innovate in design, durability, and sustainability while maintaining cost efficiency. The increasing adoption of hybrid and composite materials adds further pressure on quartz stone market penetration.
Regional Analysis
North America
The North America Quartz Stone Market was valued at USD 2,328.96 million in 2018, increased to USD 2,719.48 million in 2024, and is projected to reach USD 5,224.04 million by 2032, growing at a CAGR of 7.98%. The region accounted for 21% of the global market share in 2024. Growth is driven by strong demand for premium interior materials, rising home renovations, and advancements in engineered quartz technology. The United States leads regional adoption, supported by high consumer spending, sustainable building practices, and increasing residential and commercial construction activities.
Europe
The Europe Quartz Stone Market stood at USD 2,073.60 million in 2018, expanded to USD 2,644.54 million in 2024, and is forecast to reach USD 4,744.99 million by 2032, registering a CAGR of 7.09%. The region captured 21% of the global market share in 2024. Market growth is supported by the rising popularity of sustainable construction, aesthetic architecture, and increasing remodeling projects. Countries such as Germany, Italy, and the UK lead due to advanced manufacturing capabilities, high disposable income, and strong demand for energy-efficient, durable interior materials.
Asia Pacific
The Asia Pacific Quartz Stone Market dominated globally, valued at USD 4,113.60 million in 2018, rising to USD 5,646.36 million in 2024, and projected to reach USD 11,526.40 million by 2032, growing at a CAGR of 9.18%. The region held the largest 44% market share in 2024. Rapid urbanization, expanding residential and commercial construction, and the rise of local quartz manufacturing clusters drive growth. China, India, and Japan lead demand due to large-scale infrastructure projects and strong export capabilities. Increasing adoption of eco-friendly quartz surfaces further supports market expansion across Asia Pacific.
Market Segmentations:
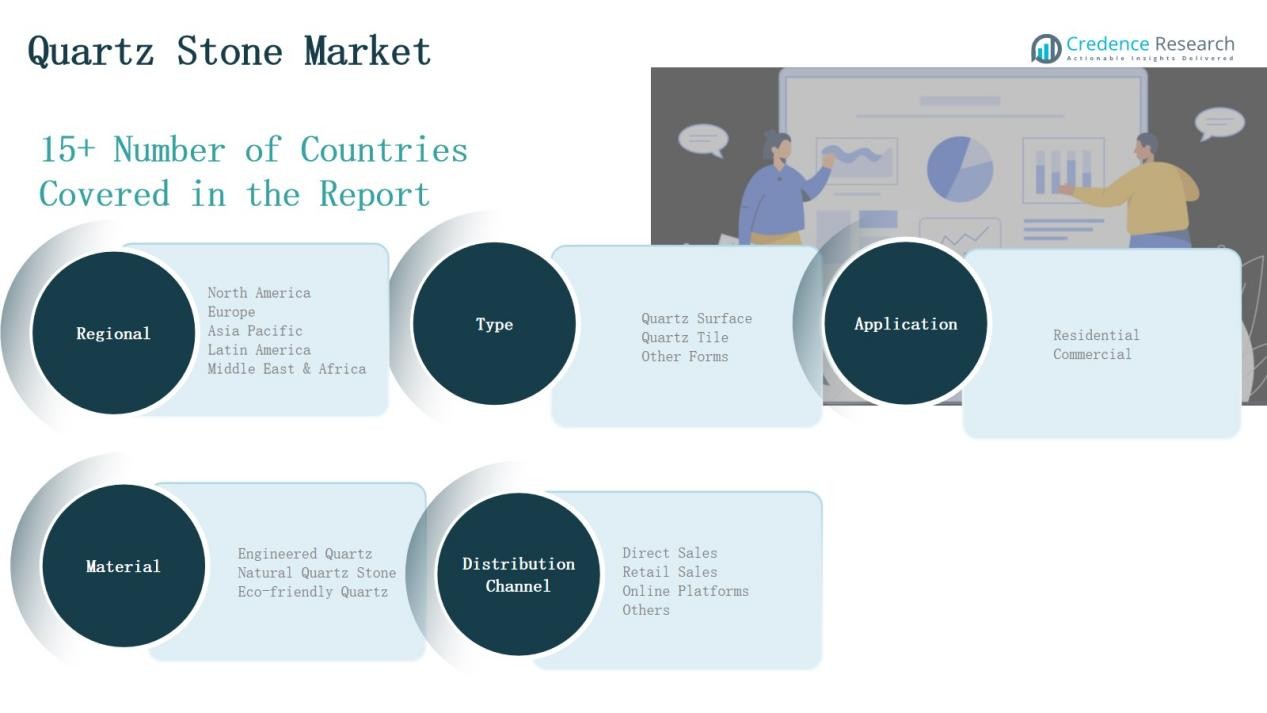
By Type
- Quartz Surface
- Quartz Tile
- Other Forms
By Application
- Residential
- Commercial
By Material Composition
- Engineered Quartz
- Natural Quartz Stone
- Eco-friendly Quartz
By Distribution Channel
- Direct Sales
- Retail Sales
- Online Platforms
- Others
By Region
- North America:S., Canada, Mexico
- Europe:UK, France, Germany, Italy, Spain, Russia, Rest of Europe
- Asia Pacific:China, Japan, South Korea, India, Australia, Southeast Asia, Rest of Asia Pacific
- Latin America:Brazil, Argentina, Rest of Latin America
- Middle East:GCC Countries, Israel, Turkey, Rest of Middle East
- Africa:South Africa, Egypt, Rest of Africa
Competitive Landscape
The Quartz Stone Market is highly competitive, characterized by the presence of global and regional manufacturers focusing on product quality, innovation, and design diversity. Key players such as Caesarstone, Cambria, Hanwha L&C, LG Hausys, Vicostone, and DuPont dominate through extensive distribution networks and advanced production technologies. These companies emphasize engineered quartz products that offer superior durability, aesthetic appeal, and sustainability. Strategic partnerships, capacity expansions, and product innovations enhance their market reach and brand positioning. Emerging players from Asia, particularly China and India, strengthen price competitiveness and expand export volumes. Sustainability-focused production using recycled materials and low-emission resins is gaining prominence, reflecting industry adaptation to green building standards. The competitive environment remains dynamic, with technological advancements, regional capacity growth, and rising brand consolidation shaping market behavior across residential, commercial, and architectural applications globally.
Key Players
- Caesarstone
- Hanwha L&C
- Compac
- Vicostone
- Wilsonart
- DuPont
- LG Hausys
- Cambria
- Santa Margherita
- Quarella
- Samsung Radianz
- Bitto (Dongguan)
- OVERLAND
- UVIISTONE
- Polystone
- Ordan
- Blue Sea Quartz
- Falat Sang Asia Co.
- Belenco Quartz Surfaces
- Prestige Group
Recent Developments
- In August 2025, Cambria announced an $80 million investment to reshore quartz processing and build a new manufacturing facility in Dakota County.
- In August 2025, CRL Stone launched its 2025 Quartz Collection brochure, featuring new designs such as Verona Gold and Arabescato Vagli.
- In April 2025, Stone Plus (India) expanded into quartz manufacturing with the opening of its QRocks facility in Udaipur, Rajasthan.
- In July 2025, Vicostone launched 10 new quartz colors for its Fall 2025 collection.
Report Coverage
The research report offers an in-depth analysis based on Type, Application, Material Composition, Distribution Channel and Region. It details leading market players, providing an overview of their business, product offerings, investments, revenue streams, and key applications. Additionally, the report includes insights into the competitive environment, SWOT analysis, current market trends, as well as the primary drivers and constraints. Furthermore, it discusses various factors that have driven market expansion in recent years. The report also explores market dynamics, regulatory scenarios, and technological advancements that are shaping the industry. It assesses the impact of external factors and global economic changes on market growth. Lastly, it provides strategic recommendations for new entrants and established companies to navigate the complexities of the market.
Future Outlook
- Demand for engineered quartz surfaces will continue increasing across residential and commercial sectors.
- Sustainability-focused production and recycling practices will gain stronger industry adoption.
- Advancements in digital design and surface finishing will enhance customization options.
- Growing investments in smart manufacturing will improve quality and production efficiency.
- Asia Pacific will remain the primary growth hub due to rapid urbanization and infrastructure expansion.
- The use of quartz in luxury interiors and modern architecture will strengthen market penetration.
- Strategic collaborations between builders and quartz manufacturers will expand distribution networks.
- Eco-friendly quartz products will gain traction among environmentally conscious consumers.
- Innovations in color, texture, and pattern replication will drive design diversification.
- Expansion of online retail platforms will boost accessibility and global brand visibility.

Request a Free Sample
Fill in your details and we'll send you a free sample report.
- Sample data tables & charts
- Research methodology
Need a Custom Version of This Report?
Tailor the scope, geography, or segments to your exact requirements.
- Custom geography or segment scope
- Direct access to our analyst team
Frequently Asked Questions
What is the current market size for Quartz Stone Market, and what is its projected size in 2032?
At what Compound Annual Growth Rate is the Quartz Stone Market projected to grow between 2025 and 2032?
Which Quartz Stone Market segment held the largest share in 2024?
What are the primary factors fueling the growth of the Quartz Stone Market?
Who are the leading companies in the Quartz Stone Market?
Which region commanded the largest share of the Quartz Stone Market in 2024?
Table of Content
Chapter 1 Market Segmentation
- 1.1 Segmentation Framework
- 1.1.1 Product and Service Classification
- 1.1.2 Application and End-Use Classification
- 1.1.3 Technology and Solution Classification
- 1.1.4 Customer and Distribution Channel Classification
- 1.1.5 Geographic Segmentation
- 1.1.6 Market Segment Definitions and Boundaries
Chapter 2 Introduction
- 2.1 Report Objectives and Scope
- 2.2 Product Definition and Industry Terminology
- 2.3 Market Inclusions and Exclusions
- 2.4 Research Process
- 2.4.1 Primary Research and Expert Interviews
- 2.4.2 Secondary Research and Source Review
- 2.4.3 Top-Down and Bottom-Up Estimation
- 2.4.4 Data Triangulation and Verification
- 2.5 Market Size Measurement Basis
- 2.5.1 2024: USD 12,851.75 million → 2032: USD 24,745.35 million
- 2.6 Historical and Forecast Reference Periods
- 2.6.1 Base Year: 2024
- 2.6.2 Forecast Period: 2024-2032
- 2.7 Research Assumptions and Limitations
Chapter 3 Executive Summary
- 3.1 Market Snapshot and Key Findings
- 3.2 Base-Year Market Size, 2024
- 3.3 Forecast Market Size, 2032
- 3.4 Revenue and Volume Growth Outlook
- 3.5 Key Demand and Supply Indicators
- 3.6 Leading Market Segments
- 3.7 Fastest-Growing Market Opportunities
- 3.8 Regional Performance Highlights
- 3.9 Technology and Industry Transformation
- 3.10 Competitive Landscape Summary
- 3.11 Analyst View and Strategic Implications
Chapter 4 Global Quartz Stone Market Trends and Developments
- 4.1 Historical Industry Development
- 4.2 Recent Market Trends and Developments
- 4.3 Demand and Customer Behavior Trends
- 4.4 Technology and Product Innovation
- 4.5 Artificial Intelligence, Automation and Digitalization
- 4.6 Local Manufacturing and Supply Chain Realignment
- 4.7 Industry Partnerships, Mergers and Acquisitions
- 4.8 Sustainability and Circular Economy Developments
- 4.9 Government and Private Sector Investment Trends
- 4.10 Emerging Business Models and Commercialization
- 4.11 Industry Developments and Announcements
Chapter 5 Global Quartz Stone Market Production, Supply and Demand Analysis
- 5.1 Demand Trend and Consumption Analysis
- 5.2 Demand Forecast, 2024-2032
- 5.3 Production and Output Trend
- 5.4 Production and Output Forecast, 2024-2032
- 5.5 Installed Capacity and Capacity Utilization
- 5.6 Company-Wise Production Plants and Statistics
- 5.6.1 Installed Production Capacity
- 5.6.2 Actual Production
- 5.6.3 Planned Capacity and Expansion Targets
- 5.7 Supply Chain Structure and Procurement Trends
- 5.8 Supply-Demand Gap and Bottlenecks
- 5.9 Import Dependence and Sourcing Structure
- 5.10 Contract Manufacturing and Outsourcing
- 5.11 Regional Supply and Demand Concentration
Chapter 6 Global Quartz Stone Market Pricing Analysis
- 6.1 Pricing Structure and Measurement
- 6.2 Historical Pricing Trends
- 6.3 Pricing Outlook, 2024-2032
- 6.4 Average Selling Price and Unit Economics
- 6.5 Pricing by Product and Market Segment
- 6.6 Geographic Pricing Differences
- 6.7 Key Input, Energy, Labor and Logistics Costs
- 6.8 Contract Pricing and Purchasing Models
- 6.9 Pricing Sensitivity and Competitive Positioning
- 6.10 Price, Margin and Profitability Implications
Chapter 7 Global Quartz Stone Market Dynamics
- 7.1 Market Growth Drivers
- 7.1.1 Demand-Side Drivers
- 7.1.2 Technology and Innovation Drivers
- 7.1.3 Infrastructure and Investment Drivers
- 7.1.4 Regulatory and Policy Drivers
- 7.2 Market Restraints
- 7.2.1 Cost and Affordability Constraints
- 7.2.2 Technology and Adoption Barriers
- 7.2.3 Supply Chain and Operational Constraints
- 7.3 Market Challenges
- 7.3.1 Competitive Pressure and Margin Erosion
- 7.3.2 Skills, Infrastructure and Implementation Gaps
- 7.4 Emerging Market Opportunities
- 7.5 Market Dynamics Impact and Time-Horizon Assessment
Chapter 8 Global Quartz Stone Value Chain Analysis
- 8.1 Industry Value Chain Overview
- 8.2 Upstream Suppliers and Critical Inputs
- 8.3 Technology and Component Providers
- 8.4 Manufacturing or Service Delivery
- 8.5 Distribution, Channel Partners and Integrators
- 8.6 Downstream Applications and End Users
- 8.7 Value Addition and Profit Pools
- 8.8 Vertical Integration and Outsourcing
- 8.9 Supplier Concentration and Risk
- 8.10 Supply Chain Localization and Resilience
Chapter 9 Global Quartz Stone Market Regulations and Policies
- 9.1 Relevant Laws, Standards and Compliance Frameworks
- 9.2 Product, Service, Safety and Quality Requirements
- 9.3 Government Policies, Incentives and Subsidies
- 9.4 Imports, Exports and Trade Barriers
- 9.5 Public Procurement and Local Content Requirements
- 9.6 Environmental and Sustainability Compliance
- 9.7 Upcoming Policy Changes and Market Implications
Chapter 10 Global Quartz Stone Market Hotspots and Opportunities
- 10.1 Market Opportunity Mapping and Growth Hotspots
- 10.2 High-Growth Applications and Customer Groups
- 10.3 Underserved Markets and White-Space Opportunities
- 10.4 Emerging Technology and Product Opportunities
- 10.5 New Capacity and Investment Hotspots
- 10.6 Market Entry and Expansion Opportunities
- 10.7 Distribution and Partnership Opportunities
- 10.8 Near-Term and Long-Term Commercial Potential
- 10.9 Opportunity Attractiveness and Execution Risks
Chapter 11 Global Quartz Stone Market Outlook, 2024-2032
- 11.1 Market Size and Analysis
- 11.1.1 Revenue (Market Measurement: 2024: USD 12,851.75 million → 2032: USD 24,745.35 million)
- 11.1.2 Market Volume and Quantity Sold
- 11.1.3 Historical Market Size
- 11.1.4 Base-Year Market Size, 2024
- 11.2 Market Forecast, 2024-2032
- 11.2.1 Revenue Forecast to 2032
- 11.2.2 Volume Forecast to 2032
- 11.2.3 CAGR and Year-on-Year Growth
- 11.2.4 Incremental Revenue Opportunity
- 11.3 Forecast Assumptions and Scenario Analysis
- 11.3.1 Base-Case Forecast
- 11.3.2 Optimistic and Conservative Scenarios
- 11.3.3 Technology, Pricing and Policy Sensitivities
- 11.4 Market Attractiveness and Growth Outlook
Chapter 12 Global Quartz Stone Market Segmentation and Outlook
- 12.1 Segmentation Summary and Market Shares, 2024
- 12.2 Largest and Fastest-Growing Segments
- 12.3 Segment Growth Comparison
- 12.4 Segment Attractiveness and Priority Matrix
Chapter 13 Global Quartz Stone Geographic Market Outlook, 2024-2032
- 13.1 Regional Market Size and Share, 2024
- 13.2 Regional Market Forecast, 2024-2032
- 13.3 Regional Pricing, Production and Demand Differences
- 13.4 North America
- 13.4.1 United States
- 13.4.2 Canada
- 13.4.3 Mexico
- 13.5 Europe
- 13.5.1 Germany
- 13.5.2 France
- 13.5.3 Italy
- 13.5.4 United Kingdom
- 13.5.5 Spain
- 13.5.6 Poland
- 13.5.7 Russia
- 13.5.8 Netherlands
- 13.5.9 Belgium
- 13.5.10 Sweden
- 13.5.11 Denmark
- 13.5.12 Norway
- 13.5.13 Rest of Europe
- 13.6 Asia Pacific
- 13.6.1 China
- 13.6.2 India
- 13.6.3 Japan
- 13.6.4 South Korea
- 13.6.5 Thailand
- 13.6.6 Indonesia
- 13.6.7 Vietnam
- 13.6.8 Malaysia
- 13.6.9 Australia
- 13.6.10 Rest of Asia Pacific
- 13.7 Latin America
- 13.7.1 Brazil
- 13.7.2 Argentina
- 13.7.3 Colombia
- 13.7.4 Chile
- 13.7.5 Rest of Latin America
- 13.8 Middle East
- 13.8.1 Saudi Arabia
- 13.8.2 United Arab Emirates
- 13.8.3 Turkey
- 13.8.4 Israel
- 13.8.5 Iran
- 13.8.6 Rest of the Middle East
- 13.9 Africa
- 13.9.1 South Africa
- 13.9.2 Egypt
- 13.9.3 Nigeria
- 13.9.4 Morocco
- 13.9.5 Rest of Africa
- 13.10 Regional Investment, Policy and Supply Chain Differences
- 13.11 Regional Competitive Landscape
- 13.12 Geographic Growth Hotspots
Chapter 14 Global Quartz Stone Technology, Innovation and Sustainability Outlook
- 14.1 Technology Landscape and Maturity
- 14.2 Product, Process and Service Innovation
- 14.3 AI, Automation and Digital Tools in the Industry
- 14.4 Technology Adoption and Performance Benchmarking
- 14.5 Innovation Pipeline and R&D Investment
- 14.6 Patent and Intellectual Property Trends
- 14.7 Energy Efficiency and Resource Management
- 14.8 Sustainability, Recycling and Circularity
- 14.9 Technology Roadmap, 2024-2032
- 14.10 Risks of Obsolescence and Technology Substitution
Chapter 15 Global Quartz Stone Market Key Strategic Imperatives
- 15.1 Growth and Market Entry Priorities
- 15.2 High-Return Products and Segments
- 15.3 Pricing, Profitability and Cost Optimization
- 15.4 Technology Investment and Product Differentiation
- 15.5 Supply Chain Localization and Resilience
- 15.6 Distribution and Customer Acquisition
- 15.7 Partnership, Acquisition and Capacity Strategy
- 15.8 Regional Expansion Priorities
- 15.9 Short-, Medium- and Long-Term Actions
Chapter 16 Competition Outlook
- 16.1 Industry Competition Characteristics
- 16.2 Market Structure and Concentration
- 16.3 Market Share and Competitive Positioning, 2024
- 16.4 Company-Wise Revenue and Product Benchmarking
- 16.5 Production and Service Capacity Benchmarking
- 16.6 Technology, Pricing and Differentiation
- 16.7 Regional Footprint and Distribution Strength
- 16.8 Mergers, Acquisitions and Strategic Alliances
- 16.9 New Entrants and Competitive Threats
- 16.10 Porter's Five Forces and Industry Attractiveness
- 16.11 Competitive Outlook, 2024-2032
Chapter 17 Company Profiles
- 17.1 Company Coverage and Selection Criteria
- 17.2 Leading Market Participants – Standard Profile Structure
- 17.2.1 Business Description
- 17.2.2 Company Ownership and Geographic Presence
- 17.2.3 Product and Service Portfolio
- 17.2.4 Manufacturing and Operating Footprint
- 17.2.5 Production Capacity and Expansion Plans
- 17.2.6 Financial Performance and Investment
- 17.2.7 Market Share and Competitive Position
- 17.2.8 Technology and Innovation Capabilities
- 17.2.9 Strategic Alliances or Partnerships
- 17.2.10 Recent Developments
- 17.2.11 Growth Strategy and Outlook
- 17.3 Other Relevant Market Participants
Note: Every listed company is profiled on the structure shown under the first company. The company list is preliminary and may change based on research findings, market developments, data availability and client requirements.
Chapter 18 Disclaimer
- 18.1 Research and Forecast Disclaimer
- 18.2 Data Source and Estimation Limitations
Note: The depth of individual sections depends on data availability for this market. Volume, capacity, trade and other unit-based metrics are included where applicable.

